
Walmart’s quick-commerce arm nearly tripled daily orders in nine months. Run the same numbers per dark store and Flipkart sits at roughly 45% of the throughput the market leader says the model actually needs.
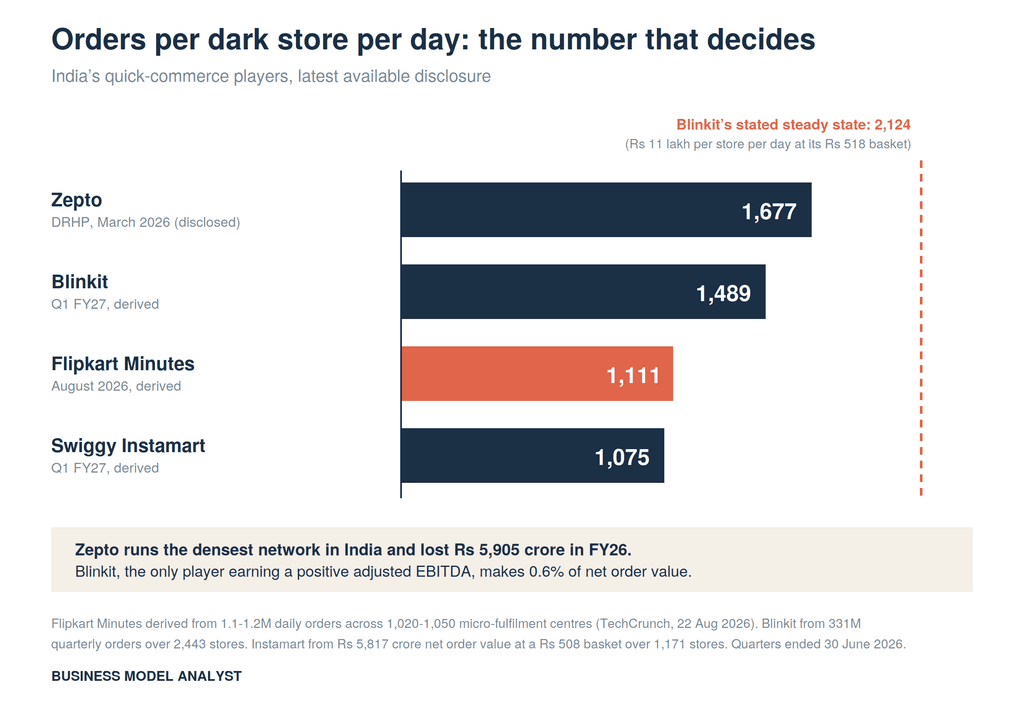
Flipkart Minutes now handles 1.1 million to 1.2 million orders a day across about 1,035 micro-fulfilment centres, which works out to roughly 1,111 orders per store per day. That is a real achievement in two years. It is also below Blinkit’s 1,489 and Zepto’s 1,677, and about 45% of the roughly ₹11 lakh of daily throughput per store that Blinkit has told investors it is building toward. India’s quick-commerce market has already tested whether order volume alone produces profit. Zepto has the densest store network in the country and lost about 26 paise on every rupee of revenue last year. Order count is the scoreboard everyone reports. It is not the scoreboard that decides.
Somebody at Flipkart has had a very good nine months. In November the company’s instant-delivery service was moving roughly 395,000 orders a day. It now moves close to 1.2 million. Delivery times fell from 13 minutes to 11. Two thirds of monthly buyers come back. Transactions per customer are up more than half.
Every one of those numbers is genuinely good, and every one of them measures demand. The problem in Indian quick commerce has never been demand. Consumers took to ten-minute grocery delivery faster than almost anyone forecast, and they are not going back. The problem is that the industry has spent five years and several billion dollars discovering that getting people to order is the easy half.
What happened
TechCrunch reported on August 22 that Flipkart Minutes, launched in August 2024, is now delivering 1.1 million to 1.2 million orders a day, up from about 390,000 to 400,000 in November. That puts Walmart’s quick-commerce venture within striking distance of Swiggy’s Instamart at roughly 1.4 million daily orders, and makes it a credible fourth entrant in a market that Blinkit (3.4 million to 3.6 million daily orders) and Zepto (2.4 million to 2.6 million) have led on volume.
The infrastructure numbers explain the volume. Minutes runs about 1,020 to 1,050 micro-fulfilment centres, up from roughly 600 in January and about 340 a year ago. It is adding around 100 a month and targeting 1,500 by the end of 2026. Baskets run ₹400 to ₹500, with fruit, vegetables, staples, dairy and meat growing fastest, and the company is layering in organic and artisanal lines to lift the ticket.
Datum Intelligence adviser Satish Meena told TechCrunch that Flipkart’s edge is the customer base it already paid to acquire, and that the service is now “already a serious player.” He also framed the expansion as defensive: once shoppers learn that groceries arrive in minutes, the incumbent e-commerce platforms lose those transactions permanently if they cannot match the speed.
Amazon is running the same play. Amazon Now, launched in June 2025, has doubled orders every quarter and is being pushed to more than 300 Indian cities with a planned network of more than 1,000 micro-fulfilment centres, sitting inside a $35 billion India commitment through 2030.
The backstory
The most useful context is not who launched first. It is what the three incumbents have already learned about where the money is, because all three now publish enough to check.
Blinkit, inside Eternal, is the only Indian quick-commerce operator producing a positive adjusted EBITDA. In the June 2026 quarter it delivered 331 million orders across 2,443 dark stores in more than 300 cities, on net order value of ₹17,132 crore. Adjusted EBITDA was ₹102 crore. That is 0.6% of net order value, the fifth consecutive quarter of improvement, and it is what winning looks like right now. Inventory shrinkage alone ran ₹308 crore in the quarter, three times the profit.
Instamart’s June quarter is the more instructive one. Swiggy reached contribution-margin breakeven in May 2026, arriving at minus 0.2% of gross order value from minus 4.6% a year earlier. It did not get there by scaling orders. It got there by lifting revenue per order from ₹97 to ₹108, adding just 28 dark stores in the whole quarter, and discontinuing service to more than four million users it had decided were unprofitable. Instamart deliberately shrank its customer base to fix its unit economics, and it worked.
Zepto is the control experiment. Its June 2026 draft prospectus discloses that its stores average 1,677 orders a day, up from 1,325 two years earlier. That is the highest density in the Indian market, better than Blinkit’s, comfortably better than Instamart’s. Zepto lost ₹5,905 crore in FY26 on revenue of ₹22,624 crore, roughly 26 paise on the rupee. Eternal chief executive Albinder Dhindsa has described pricing-led growth in this category as a “systemic trap,” and Zepto is the illustration: density bought with discounts does not convert into margin.
So the industry has already run three separate versions of the experiment. The densest network posts the biggest loss. The one that hit breakeven did it by adding almost no stores and removing customers. The one that makes money makes 0.6%.
The plan
Flipkart’s plan is to get to 1,500 stores by December and keep pulling its existing e-commerce base across. On the numbers, it is working: order growth of 2.9 times in nine months against store growth of about 1.7 times since January means throughput per store is rising, not just store count.
The question is what the finish line looks like, and Blinkit has helpfully published it. On its June-quarter call, Eternal raised its steady-state assumption for net order value per store per day from ₹7 lakh to ₹11 lakh, a 57% increase, and simultaneously raised its assumed steady-state capital expenditure per store, including warehousing, from ₹1 crore to ₹2.5 crore. Blinkit is deliberately building fewer, larger, deeper-assortment stores, and telling the market the model only clears at much higher throughput than anyone currently runs.
Measure everyone against that stated finish line and the ranking inverts.
At its ₹518 net average order value, Blinkit’s ₹11 lakh target implies roughly 2,124 orders per store per day. Blinkit itself runs at ₹7.71 lakh, about 70% of its own target. Instamart, from its disclosed net order value and ₹508 basket, runs at ₹5.46 lakh, about 50%. Flipkart Minutes, at 1,111 orders on a ₹450 midpoint basket, runs at roughly ₹5.00 lakh, about 45%.
Flipkart has not caught the leaders. It has caught the two players furthest from the economics the leader says the category requires, and it is carrying the lowest disclosed basket in the market, about 13% below Blinkit and 11% below Instamart.
The business model angle
Quick commerce presents as an app business and behaves as a retail real-estate business. The dark store has a fixed cost base that barely moves between 800 orders a day and 1,800: rent, pickers, packers, electricity, shelving, shrinkage. Every marginal order lands on the same fixed base. This is sales per square foot with a delivery rider attached, and it is why Zepto’s own prospectus makes orders per store per day the number it wants investors to watch.
That reframing matters most for Walmart, because it inverts the argument Walmart makes about itself everywhere else.
Walmart’s entire US omnichannel thesis is that it already owns the fulfilment network. Around 80% of its US e-commerce is fulfilled from stores it built decades ago for a different purpose, which is exactly the measurement problem covered in our piece on Walmart’s comp sales and store-fulfilled metric. The node was free. It was already paid for, already staffed, already stocked.
In India, Walmart owns no stores. Flipkart is a marketplace. So the node has to be bought, one micro-fulfilment centre at a time, roughly 100 a month.
Price that at Blinkit’s own disclosed figures and the bill becomes visible. At ₹2.5 crore of steady-state capital expenditure per store, 1,500 stores is ₹3,750 crore. Blinkit’s net working capital runs about ₹1.04 crore per store, which adds roughly ₹1,563 crore of inventory sitting in those buildings. Total capital tied up at Flipkart’s target network: roughly ₹5,313 crore, or about $560 million.
Now apply the leader’s current return. At today’s ₹5.00 lakh of throughput per store per day, 1,500 stores produce annual net order value of about ₹27,375 crore. At Blinkit’s current 0.6% margin, that is ₹164 crore of adjusted EBITDA on ₹5,313 crore of capital, a return of roughly 3%. Get to Blinkit’s ₹11 lakh steady state and hold a 4% margin, and the same capital base returns about 45%.
That gap is the entire investment case in Indian quick commerce, and it is not a market-share question. It is a throughput and monetisation question. The capital only works if density roughly doubles and revenue per order keeps climbing.
Here is the uncomfortable part for Flipkart. Density is rising across the industry. Revenue per order is where the two positive results came from, and basket sizes are flat to falling: Blinkit’s net average order value slipped to ₹518 from ₹521, and Instamart lifted its ticket 12% only by removing four million customers. Flipkart is scaling hardest on the variable that is already improving for everyone and starting furthest back on the variable that actually produced both profitable outcomes.
Which is why the gourmet and organic push buried at the bottom of the TechCrunch piece is the most strategically significant line in it. That is Flipkart aiming at the ticket, not the order count.
The risk
Four arguments cut against this reading, and two of them are strong.
The first and best: store age. Flipkart added roughly 435 stores since January, so about 42% of its network is under eight months old and still ramping. Blinkit’s network is years older on average. Strip the immature cohort out and Flipkart’s mature stores could plausibly be running at or above 1,400 orders a day, which would put them level with Blinkit rather than behind Instamart. Flipkart does not disclose a cohort split, so this cannot be settled from outside. It is the single most likely way this analysis is wrong, and if Flipkart ever publishes mature-store density, that is the number to check first.
The second: the balance sheet makes the return math less binding than it looks. A $560 million network build is about 2% of Walmart’s roughly $30 billion FY27 capital expenditure budget and under 3% of a single half-year of operating cash flow. Eternal answers to public shareholders every ninety days, Swiggy is under visible margin pressure, and Zepto pushed its IPO back and is raising a bridge round. Walmart can fund sub-cost density for as long as it takes and count the return in transactions it did not lose. Whether that is discipline or the absence of it is a fair argument, but Walmart’s own results show International operating income growth led partly by improving e-commerce economics in India, so this is not a business running blind.
The third: my Flipkart throughput number is derived, not disclosed. It rests on TechCrunch’s reported order and store ranges and a ₹450 midpoint basket, and Flipkart does not publish net order value per store. The order-count comparison is firmer than the rupee comparison.
The fourth, which I think is weak: that catching Instamart is worth something on its own. Instamart is the smallest of the three incumbents by volume and the one that just chose contraction over growth. Passing it is a milestone in a race, not evidence the model clears.
Quick questions
Is Flipkart Minutes profitable? Flipkart does not break out Minutes separately, and Walmart does not disclose it. Given that the market leader earns 0.6% of net order value at 1.5 times Flipkart’s throughput, and that Instamart only reached contribution-margin breakeven this year, a two-year-old network adding 100 stores a month is almost certainly losing money at the segment level.
Why does orders per dark store per day matter more than total orders? Because the dark store carries a fixed cost regardless of volume. Total orders tell you how many stores you opened. Orders per store tell you whether opening them was a good idea.
Who actually leads Indian quick commerce? On volume, Blinkit, at 3.4 million to 3.6 million daily orders and 2,443 stores. On store density, Zepto, at 1,677 orders per store per day. On profitability, Blinkit, and only just, at 0.6% of net order value.
Does Walmart owning Flipkart change the competitive dynamic? Materially. It is the only entrant whose parent generates tens of billions of dollars in annual operating cash flow and does not have to justify Indian dark-store losses as a standalone P&L every quarter.
What should I watch next? Basket size, not order count. Flipkart’s ₹400 to ₹500 ticket against Blinkit’s ₹518 and Instamart’s ₹508, and whether the gourmet and organic push moves it. Also watch Flipkart’s IPO disclosures, since a listing would force the first real Minutes segment reporting the market has seen.
The Business Model Analyst Take
Every operator eventually meets a version of this problem: the metric that is easiest to grow is rarely the metric that decides the outcome, and it takes discipline to keep reporting the second one while the first one is going up and to the right.
Flipkart’s nine months are genuinely impressive. Tripling volume and cutting delivery time simultaneously is hard operating work. But the category has already published the answer key. Zepto proved the densest network can be the biggest loser. Instamart proved the route to breakeven runs through revenue per order and, painfully, through removing customers. Blinkit proved the ceiling on getting it right is currently 0.6%.
The reason quick commerce keeps pulling capital anyway is that the arithmetic flips violently at scale. The same ₹5,300 crore of capital returns about 3% at today’s throughput and about 45% at the throughput Blinkit says is coming. Almost no other business model has that shape. It is why everyone is building and why nobody can stop.
If you run a business with a fixed-cost node, whether that is a store, a kitchen, a clinic, a warehouse or a truck, the discipline is the same. Publish your throughput per node, state the throughput the model requires, and report the gap every period. Blinkit does this. It is the reason its investors can price a business earning 0.6% at a premium: they can see the target, they can see the distance, and they can watch it close.
Flipkart is running the harder version of the same bet with a much larger balance sheet behind it and much less disclosure in front of it. Two years in, the orders say it belongs in the race. The stores are still the open question.