
The Wall Street Journal reviewed 212 TikTok accounts dispensing financial advice. About a fifth carry brand sponsorships. The other four-fifths are selling to the same customer the brands want.
A finfluencer’s product is not investment advice. It is proof that the advice worked, and that proof gets sold twice: to the audience as a course, and to financial brands as distribution. The channel is cheap because the creator produces trust with capital instead of credentials, and because the one time a US regulator put a price on the arbitrage, the bill came to about $21 per funded brokerage account.
A $100,000 car to sell a $300 course
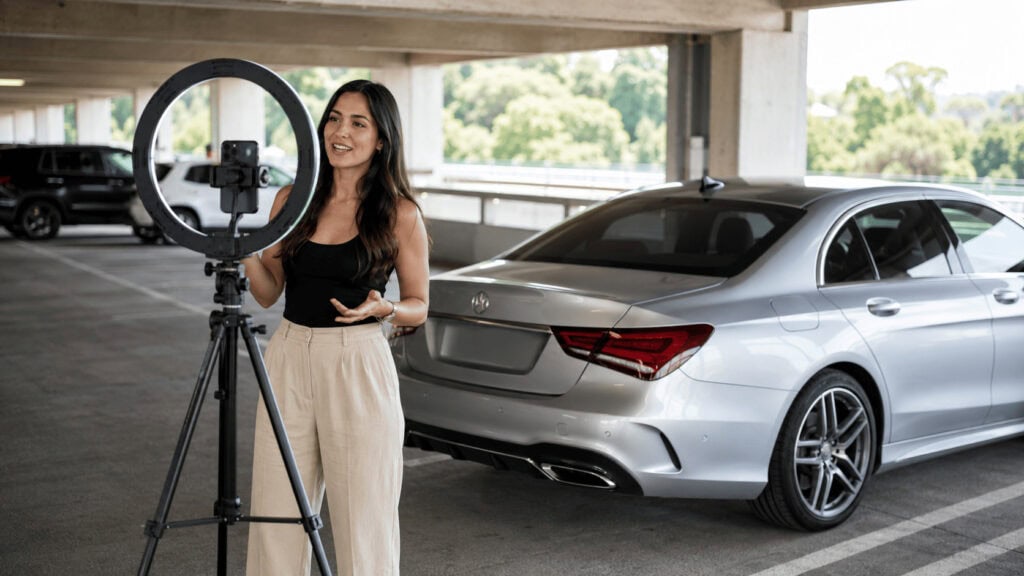
Brittany Bowen films money advice while she does her makeup. She told the Journal she bought a Mercedes for just over $100,000 as a marketing tactic, then posted about the purchase and shot videos in front of it. The car exists to sell a course for women priced just under $300.
Run the arithmetic on that and you get the shape of the business. At $299 a seat, Bowen needs roughly 335 sales to recover the sticker price of the car, before payment processing, ad spend, platform fees or tax. The car is not a reward for the course. It is an input to it.
Every seller of financial services has to solve the same problem: why should a stranger believe you with their money. A registered investment adviser answers by posting capital, carrying insurance, submitting to exams and accepting fiduciary liability. Bowen answers by buying a Mercedes. Both are collateral for the same claim. Only one of them is recoverable when the claim turns out to be wrong.
What happened
Nat Ives ran an interview in the WSJ CMO Today newsletter on August 17, 2026 with Elyse Goncalves, who reviewed close to 50 hours of financial content across 212 TikTok accounts for the Journal. Her sample runs from credentialed educators pushing index funds to unlicensed stock pickers and lifestyle creators selling paid courses. Most hold no formal license or certification.
Three findings matter for anyone selling financial products.
First, the tactics are borrowed wholesale from general creator growth playbooks. Timothy James, a 38-year-old stock picker, told the Journal he has used rage-baiting lines to drive views. UK creator Leo Gibson reached close to 500,000 views on a financial advice video by filming in a bedroom instead of an office, on the theory that a young man in a hoodie reads as more credible than a suit behind a desk.
Second, the brands are buying. Fidelity credits financial influencers in part for a 73% year-over-year jump in Gen Z Roth IRA contributions. Goncalves found that about a fifth of the 212 accounts posted sponsored videos or content naming specific companies, many of them financial brands.
Third, and this is the number the coverage skipped over: four-fifths of the sample carry no sponsorship at all. Those creators monetize by selling something to the audience directly. Courses, communities, coaching, affiliate links. They are not a media channel that Fidelity can rent. They are competing for the same wallet.
The backstory
Fidelity’s published Q1 2026 retirement analysis, drawn from more than 54 million accounts, put total Gen Z IRA contributions up 65% year over year against 31% for millennials. Roth accounts took 67% of all IRA contributions. Rita Assaf, Fidelity’s VP of retirement offerings, attributed the Gen Z surge to a mix of platform accessibility, workplace financial wellness programs and financial awareness shaped partly by social media.
Nobody at Fidelity can trace a Roth contribution back to a TikTok. The attribution is a reasonable inference, not a measurement, and one piece of evidence points the other way. Researchers at the Center for Retirement Research, cited by Financial Planning, found the Roth surge concentrated among higher-income households in the top third of earners. The FINRA Foundation’s profile of finfluencer followers describes a population that is younger, more male, and holding lower portfolio values. Those two groups do not obviously overlap. Different surveys, different definitions, so treat it as directional. But a brand crediting a channel for dollars that appear to be arriving from a different cohort is a brand marking its own homework.
The harder evidence sits in a FINRA Foundation brief published April 2, 2026, built on the 2024 National Financial Capability Study Investor Survey. Among retail investors, 29% use social media or message boards to inform investment decisions, rising to 60% among 18-to-34-year-olds. Twenty-six percent made an investment decision on a finfluencer’s recommendation, and among younger investors that figure hits 61%.
Then the part that should worry anyone buying this channel.

Social media users consulted an average of 7.6 information sources against 4.0 for non-users. They checked a financial professional’s background at 36% versus 14%. On an objective investing knowledge quiz they scored 42% correct against 47% for non-users, and finfluencer followers scored 41%. Among investors who reported being targeted by fraud, 68% of social media users and 69% of finfluencer followers lost money, against 29% and 26% for the comparison groups.
More sources. More verification. Lower knowledge. Roughly two and a half times the rate of losing money once a fraudster finds you. Gerri Walsh, who runs the FINRA Foundation, called the combination of low measured knowledge and high self-rated confidence a serious concern.
What the channel actually produces
Volume of research is a quantity metric, and the finfluencer economy is a quantity machine. Seven and a half sources that all reached the reader through the same recommendation algorithm are not seven and a half independent checks. They are one check, repeated, which feels like diligence and functions like reinforcement.
That is the product. Not information, which the buyer can get free from the SEC. Confidence, which nobody else was supplying to a 23-year-old who told a federal survey that people like her are not usually investors. Nearly half of the finfluencer followers in FINRA’s sample agreed with a version of that statement.
Confidence converts. It converts into a Roth IRA at Fidelity and it converts into a $299 course, using the same content, from the same creator, on the same afternoon.
The business model angle
Strip the personalities out and the finfluencer runs a three-line P&L on a single asset.
Revenue line one, the audience product. Courses, memberships, coaching. High gross margin, no licensing requirement, no capital requirement, no custody obligation, no fiduciary duty. This is where four-fifths of the Journal’s sample lives.
Revenue line two, brand sponsorship. A financial brand pays for placement. The going structure in the sector has often been performance-based, which matters, because it changes who owns the risk.
Revenue line three, affiliate and referral. Paid per funded account, per signup, per click.
The single asset funding all three is trust. And the cost of goods sold is the demonstration: the Mercedes, the apartment, the screenshotted brokerage balance, the get-ready-with-me framing that makes a wealth claim feel like a confession rather than a pitch.
Traditional finance also buys trust, and it does so by posting capital where a regulator can see it. Net capital requirements, E&O insurance, Series exams, ADV filings, compliance headcount. Those costs are large, boring, and produce something a customer can verify without believing anyone. The finfluencer moved that expense line from the balance sheet to the camera. It is cheaper, it converts better, and it produces nothing a customer can check.
Now price the difference.
What FINRA charged for it
On March 18, 2024, FINRA fined M1 Finance $850,000 in the first enforcement action against a broker-dealer for supervising social media influencers. The case came out of a targeted exam of how firms acquire customers through social channels.
The program worked like this. Between January 2020 and April 2023, M1 paid influencers to promote the firm and gave each one a unique link. The firm paid a flat fee for every account a customer opened and funded through that link, and set no cap on what an influencer could earn. M1 supplied graphics and a welcome guide. It did not review or approve the posts before they went out, and did not retain them.
One influencer told viewers that margin loans could be repaid at any time, with “no set time period.” M1 can raise maintenance margin requirements without warning, force a sale, and pick which securities to liquidate. FINRA found the posts were not fair and balanced under Rules 2210 and 2010, and that M1 had no reasonable supervisory system under Rules 3110 and 4511.
The program produced more than 39,400 funded accounts.
Divide the fine by the accounts and the regulatory cost of running an unsupervised influencer acquisition machine for 39 months comes to $21.57 per funded account.
Set that against what a funded retail brokerage account is worth. Robinhood reported $4.5 billion in net revenues for 2025 across 27.0 million funded customers, which works out to roughly $167 per funded customer per year. The entire FINRA penalty amounted to about 13% of a single year of revenue from a single account, on accounts that stay for years.
That is not a deterrent. That is a licensing fee, and a cheap one. The channel kept growing because the arbitrage survived being priced.
Two structural points fall out of the M1 order. The liability landed on the buyer, not the seller: FINRA has no jurisdiction over the influencers, only over the member firm that hired them. And the compensation structure, a flat fee per funded account with no ceiling, handed creators an uncapped incentive to overstate while handing the firm the entire supervisory obligation. If you are a CMO at a brokerage reading the WSJ piece and thinking about a creator program, that asymmetry is the thing to underwrite, not the CPM.
What happens next
FINRA published a broader report on social-media-influenced investing on December 11, 2025, noting that 45% of investors take financial advice from the internet and 24% get information from social media, with reliance running at 35% among under-30s against 13% for the 65-and-over group. NASAA filed a comment letter on May 13, 2026 pressing on the fraud-vulnerability findings. Two research briefs, one enforcement action and an open comment file is what a regulator looks like in the year before it writes a rule.
The creators are moving the other way, toward larger demonstrations. Bowen’s next car will cost more than the last one, because the proof has to keep escalating to stay legible against a feed that has seen the last version. That is the structural weakness in a business whose COGS is a lifestyle: it inflates.
The risk
The case against everything above is real and worth stating plainly.
The FINRA fraud numbers may be measuring the person, not the channel. Finfluencer followers skew younger, more male, and lower-balance. That demographic carries elevated fraud exposure on its own. Social media use could be a marker for risk appetite rather than a cause of loss. FINRA’s brief describes an association, not a mechanism, and the honest version of my argument concedes that.
The channel is doing real work that Fidelity’s marketing budget never did. Nearly half of finfluencer followers said people like them are not usually investors. Social media users reported far stronger non-monetary motives for investing: entertainment at 59% against 18%, social activity at 59% against 11%, values-based investing at 66% against 31%. A Roth IRA opened at 23 by someone who would otherwise have opened nothing compounds for forty years. That is a genuine gain, and it does not show up anywhere in a fraud statistic.
The knowledge gap is five points, and both groups failed. Forty-two percent versus 47% on an objective quiz is a weak margin on which to hang a story about ignorance. Neither cohort knows much.
One enforcement action in two years cuts both ways. Either firms cleaned up their influencer programs after M1, or FINRA is not looking hard. My reading assumes the second. The first is defensible.
The sample has limits. Two hundred and twelve TikTok accounts is one platform in one country. The revenue mix on YouTube or Substack may tilt far more toward sponsorship than the one-in-five the Journal found, which would weaken the claim that brands are funding a competitor.
Here is what would change my mind: if FINRA or the SEC brings a second influencer-supervision case at a penalty priced against program revenue rather than as a flat sum, the arbitrage closes and the channel reprices toward regulated CAC. Watch for that, not for more research briefs.
Quick questions
What is a finfluencer? A social media creator who publishes financial content, usually without a securities license or advisory registration. FINRA uses the term in its own research.
Is it legal to give investment advice on TikTok? General financial education is legal. Personalized advice for compensation, and promotional content paid for by a broker-dealer, both pull you into regulated territory. Paid promotion also triggers FTC disclosure rules.
Who gets fined when an influencer misleads viewers? The firm that paid them. FINRA’s authority runs to member firms, which is why M1 wrote the $850,000 check and its influencers wrote nothing.
How much do finfluencers make? The Journal’s sample points to two models: brand sponsorships for roughly a fifth of accounts, and direct audience sales for the rest, with course prices around $300 in the example the Journal documented.
Are finfluencer followers worse investors? They score slightly lower on objective knowledge tests and lose money to attempted fraud at more than twice the rate, according to the FINRA Foundation. They also research more sources and run more background checks, so the story is about the quality of the inputs rather than the effort.
The Business Model Analyst Take
Financial brands looking at the finfluencer boom keep asking the wrong question. They ask what the CPM is. The question is who holds the license when the content is wrong, and the answer is that they do.
The deeper lesson generalizes past finance. Any business whose real product is trust has to produce that trust somehow, and there are only two methods. You can guarantee, which means posting something recoverable that a customer can verify without believing you: capital, a warranty, an audited number, a refund policy, a regulator’s stamp. Or you can demonstrate, which means showing evidence and asking the customer to draw the inference themselves.
Demonstration is cheaper to start and far more expensive to sustain, because evidence depreciates. Last year’s Mercedes stops working. The screenshot has to get bigger. Your cost of goods sold inflates on a schedule you do not control, set by whatever the rest of the feed is showing that week.
If you are building something where customers have to trust you before they can evaluate you, price both paths honestly. Count what the demonstration will cost in year three, not year one. And check who carries the liability when the demonstration turns out to be a marketing tactic, because in this market the person who bought the car is not the one who pays.
Related reading: the Robinhood SWOT analysis on how a retail brokerage converts small accounts into large ones, the Robinhood business model breakdown of where commission-free revenue actually comes from, Fidelity’s competitors and how the incumbents are positioned against each other, how content creators make money across sponsorship, affiliate and product lines, and New York City’s investigation into prediction market advertising, where regulators went after the funnel rather than the product.