
Three automakers reported into a shrinking market this week. Their operating margins ran from 3% to 31%, and the spread is a lesson in pricing power every founder should steal.
Ferrari posted a 31.2% operating margin in the second quarter while shipping fewer cars than it did a year earlier. Magna, one of the biggest parts suppliers on earth, squeezed out 6.2%. Renault’s car business earned 3%. All three sell into the same shrinking global market, and the ten-fold gap between them comes down to a single decision: Ferrari grows by charging more, not by building more.
Look at the numbers and you stop seeing an “auto industry.” You see three unrelated businesses that happen to share a product.
What Happened
Ferrari reported Q2 2026 results on July 30 and raised its full-year guidance. Revenue rose 8% to 1.94 billion euros, operating profit hit 605 million euros, and the operating margin landed at 31.2%. Deliveries came in at 3,366 cars, a planned decrease as Ferrari rotated its model lineup. The stock ticked up around 1%.
The same week, two other names crossed the wire. Magna International lifted its adjusted operating margin to 6.2% on $10.98 billion in sales, a solid result for a supplier fighting falling production volumes. Renault reported a 5.2% group operating margin on 30.3 billion euros of first-half revenue, and its shares slipped.
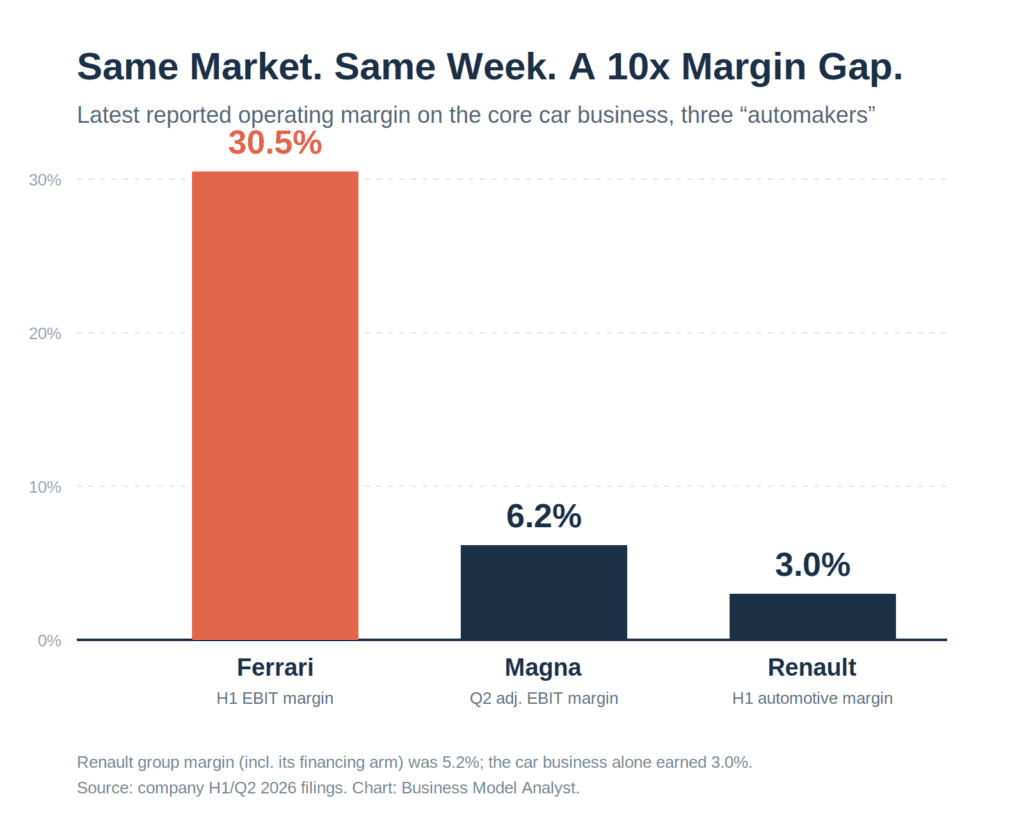
Then you read Renault’s fine print. The car-making business earned a 3.0% margin, down from a year earlier. Half of the group’s operating profit, 753 million euros of 1.567 billion, came from Mobilize Financial Services, its lending arm. Renault the manufacturer barely made money. Renault the bank carried the quarter.
The Backstory
The backdrop for all three is a market that is getting smaller. S&P Global expects global light-vehicle production to slip about 0.4% in 2026 to roughly 92.6 million units, with the deepest cuts in China and Europe and an oil-price shock from the Iran conflict threatening demand in the back half of the year.
A shrinking pie is a stress test. When volumes fall, a business model shows you what it is really made of. Companies that depend on cranking out units lose operating leverage the moment the line slows. Companies that depend on brand and scarcity barely notice.
Ferrari sells roughly 14,000 cars a year. Renault sold 1.16 million vehicles in the first half alone. Renault builds something like 165 cars for every one Ferrari ships, and earns a tenth of the margin doing it.
Three Answers to One Problem
Each company picked a different way to fight the same headwind.
Magna plays the efficiency game. As a supplier, it cannot set the price of a car, so it protects margin by winning new program launches, riding favorable currency swings, and cutting cost per part. TD Cowen’s analyst liked the free cash flow and sees room for the stock to re-rate. It is a real business, but the ceiling is low. A 6.2% margin is what you earn when your customer, the carmaker, holds the pricing power and you do not.
Renault plays the volume game, and it is grinding. The company grew revenue 9.5% and launched a wave of new EVs, yet its automotive margin fell because Chinese competition in Europe keeps pressure on prices. Berenberg flagged that even the earnings beat leaned on “lower-quality” items: capitalized software costs that flattered the margin, and a 300-million-euro partner prepayment that flattered cash flow. Strip those out and the picture is thinner. Renault’s own executives told analysts the group will not re-rate until margins stabilize.
Ferrari plays a game nobody else in autos can play. It caps supply on purpose. The order book is now full through the end of 2027, which means if you want a new Ferrari today, you wait until 2028. The F80 hypercar, priced at 3.6 million euros and limited to 799 units, sold out and is now dragging the whole revenue mix upward. Personalizations, the paint, the leather, the one-off commissions, crossed 20% of car and parts revenue. When Middle East tensions disrupted deliveries earlier in the year, Ferrari rerouted cars to other regions rather than discount a single one. That is the same scarcity playbook we broke down when Ferrari flirted with a manual gearbox: the fastest way to grow was never to sell more.
The Business Model Angle
Pricing power is the whole ballgame, and it comes from one of two places: you own something buyers cannot get elsewhere, or you do not.
Ferrari owns scarcity. It manufactures demand it deliberately refuses to fully satisfy, which lets it push price and personalization every year without chasing volume. That is why a 40% EBITDA margin on 14,000 cars beats a 3% margin on millions. The moat is the waiting list.
Magna and Renault both sit on the wrong side of that line. Magna is a price-taker to its own customers. Renault is a price-taker to the market, and its most profitable division is a lender, not a factory. This is the same lesson BYD is teaching Porsche and McLaren in Europe right now: heritage and scarcity are the only things holding premium prices up, and the moment a rival matches your product without your brand tax, the pricing power leaks away.
For an operator, the translation is blunt. Volume feels like growth, but volume without pricing power is a treadmill. You run faster every year and stay in place. Build the version of your business that mints money when growth disappears, the way Domino’s kept minting cash while its stock fell 40%. Ask what you sell that a competitor cannot copy or undercut, and if the answer is “nothing,” you are Renault: working harder for a thinner slice.
The Risk
Scarcity has a ceiling, and Ferrari is starting to bump it. The stock rose only about 1% on a 5% earnings beat, because the guidance raise matched what analysts already expected. When a business is priced for perfection, doing well is not enough. Ferrari also guided to a slightly softer second-half margin and told investors its 2026 to 2030 revenue growth will average around 5%, down sharply from the double-digit years. A scarcity model protects margins beautifully, but it caps how fast you can grow, because the second you flood the market with units, you break the exact thing that makes you special. Ferrari’s next test is the electric Ferrari Luce. An EV is easier to build at scale and easier for rivals to match, which is precisely where scarcity gets harder to defend.
Quick Questions
Did Ferrari really sell fewer cars and still make more money? Yes. Deliveries fell to 3,366 units in Q2 2026 as Ferrari rotated its lineup, yet revenue rose 8% and operating profit rose 10%, driven by a richer model mix and higher personalization spending.
Why is Renault’s margin so low if revenue grew? Renault’s car business earned only 3.0% because Chinese competition in Europe keeps pressure on prices. Half its operating profit came from Mobilize Financial Services, its lending arm, not from building cars.
What makes Ferrari’s margins so much higher than other automakers? Ferrari limits supply on purpose and sells scarcity. A full order book through 2027 and a sold-out 3.6-million-euro hypercar let it raise prices and personalization revenue without chasing volume.
Is Ferrari a car company or a luxury company? Financially, it behaves like a luxury house. Its roughly 40% EBITDA margin on about 14,000 cars a year looks nothing like a mass-market automaker and everything like a top-tier luxury brand.
The Business Model Analyst Take
The word “automaker” is close to useless. Ferrari, Magna, and Renault share a category and almost nothing else. One sells scarcity, one sells efficiency, one sells cars and quietly makes its money on loans. Put them side by side in a down market and the ranking is not about who builds the best vehicle. It is about who controls price.
Ferrari controls price because it controls supply, and it protects supply like the crown jewel it is. Renault cannot, so it competes on volume in a market where Chinese rivals will always undercut it, and leans on its bank to make the quarter look better. Magna cannot, so it fights for basis points on someone else’s product.
If you build anything, that is the question worth sitting with. Not “how do I sell more,” but “what do I own that lets me charge more.” Ferrari answered it a long time ago, and this quarter it got paid for the answer while everyone around it worked harder for less.