
Regular operators are buying HVAC shops and plumbing outfits at a fraction of what private equity pays, then selling into the same machine at three times the price. The gap is the whole business.
A wave of buyers has stopped waiting for the private-equity promotion. They raise money deal by deal through SBA loans, search funds, and independent-sponsor backers, buy small trades and manufacturing businesses at 1.8x to 5x earnings, and aim to sell into a roll-up market that pays 7x or more. That spread, not operational genius, is where the money sits.
Caroline Sabatt bought a Boston-area plumbing business in 2025 for 1.8 times EBITDA. A mid-market private-equity firm buying a platform in the same window paid closer to 7.2 times. She did not find a cheaper version of the same asset. She bought at the bottom of a ladder that runs all the way up to the buyers she hopes will take the company off her hands one day.
What Happened
The Wall Street Journal profiled a growing group of people building seven-figure net worths by buying small and midsize businesses outright, rather than climbing the associate-to-managing-director path inside a private-equity firm. The Journal calls it a shortcut to private-equity riches. The academic name is entrepreneurship through acquisition, and it now sits in the standard curriculum at schools like Harvard and Stanford.
Three figures anchor the story. Sabatt, a 35-year-old Navy veteran with Harvard government and business degrees, financed her plumbing deal with an SBA loan, personally guaranteed it, and took out a life-insurance policy as a condition. Minuteman Plumbing, Heating and Cooling brought in $2.2 million in revenue in 2025 after the merger and targets more than $6 million this year, with over $1 million in EBITDA. Rachel McGrath, a 38-year-old former oil-and-gas engineer, went through the Search Fund Accelerator, drew about $90,000 a year for two years while she hunted, and bought a Pennsylvania printing-chemicals maker called Tower Products in 2023. She put in none of her own capital and can collect up to a quarter of the profit on an eventual sale. Bakari Akil, 37, went from homeless college dropout to owner of two multimillion-dollar companies after a Harvard case study introduced him to search funds.
The Backstory
The vehicle is not new. Stanford researchers have tracked search funds for decades. What changed is the volume and the mix of ways in.
Investors backed 77 search funds in 2025, down from a 2023 peak of 101 but still high by historical standards. The bigger shift sits one category over. Firms doing deals as independent sponsors, without a committed fund, roughly doubled since 2019 to about 1,400, according to law firm McGuireWoods. Independent sponsors raise the equity for each deal separately, which lets an operator with a track record and no fund compete for the same targets a small buyout shop would chase.
Two forces pushed people toward the door at once. Business-school programs started teaching acquisition entrepreneurship as a real career, so a generation of MBAs left campus knowing search funds existed. At the same time, the traditional Wall Street path lost some of its shine. Private-equity firms have struggled to sell portfolio companies, and mid-level staff, unsure they will ever see performance pay, started leaving to buy their own.
The Plan
The mechanics separate this from a fund raising billions from pensions and endowments. A searcher finds one company, usually owned by a founder near retirement, and assembles financing per deal.
SBA loans do heavy lifting at the small end. They carry government backing, which lowers the rate against a conventional bank loan, and they let a buyer with limited capital control a real business. The tradeoff is personal: Sabatt guaranteed her loan and insured her own life to close it. Search funds sit a step up, paying a searcher a modest salary to look, then funding the acquisition and handing over a slice of equity that vests as the business performs. Independent-sponsor deals sit higher still. Akil bought a burlap-bag maker in 2023 backed by a Chicago private-equity firm, took an ownership stake, and joined the board.
The pay structure for independent sponsors reads like a scaled-down version of the fund economics they skipped. A typical deal carries a 2% closing fee, 5% of EBITDA a year, and 20% to 30% carried interest tied to how the deal performs. An operator captures fund-style economics on day one, in exchange for running an HVAC business and carrying personal risk a fund partner never touches.
The Business Model Angle
Strip away the grit narrative and one number drives the returns. Sabatt paid 1.8x EBITDA. The lower middle market as a whole told a consistent story in 2025: home-services businesses traded around 4x to 6x, deals under $10 million ran near 5.5x, sponsored platforms from $10 million to $500 million averaged about 7.2x, and platforms in the $100 million to $250 million range hit roughly 10x. US private-equity buyers averaged close to 12.8x across their deals.
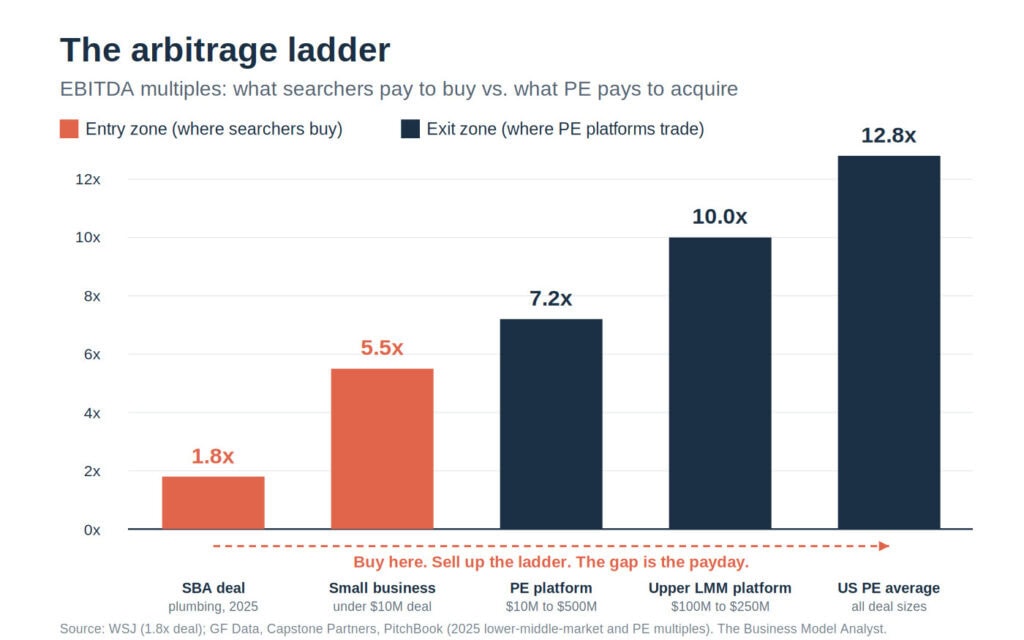
Read that ladder top to bottom and the trade becomes obvious. A searcher buys at the illiquid, no-competition, founder-is-retiring bottom, where a single motivated seller and a thin buyer pool suppress the price. The exit sits higher up, where a private-equity roll-up assembles small businesses into a platform that commands a fatter multiple. Buy a plumbing outfit at 1.8x, build it to a few million in EBITDA, and sell into a market pricing scale at 7x or more. The value creation from better operations is real, but the multiple expansion does the heavy lifting.
This is the same engine a private-equity partner runs, described plainly on our best-paying jobs in finance breakdown: acquire well, improve the earnings base, exit at a higher multiple. The searcher unbundles it. The capital comes deal by deal instead of from a fund, the sourcing and operations come from one person instead of a deal team, and the carried interest lands in an individual account instead of a partnership pool. The business model is private equity with the fund removed and the personal risk added back.
The Risk
The arbitrage depends on two things holding, and both are under pressure.
The exit market is jammed. Private-equity distributions back to investors fell to about 6% of assets under management in the first half of 2025, the lowest on record and well under the ten-year average near 14%. A large inventory of unsold mid-market companies is sitting on the books. If the buyers at the top of the ladder cannot clear their own shelves, the premium multiple a searcher is counting on for the exit may not be there when the time comes. The whole trade assumes a functioning roll-up market waiting on the other side, and that market is the one currently frozen.
The entry discount is also a crowding trade. With acquisition entrepreneurship now a standard course and 1,400 independent sponsors chasing the same fragmented industries, more buyers are competing for the same retiring-owner deals. Competition lifts entry multiples, and every turn paid on the way in comes straight out of the arbitrage on the way out. Roll-ups already carry a poor record. Research cited in the strategy literature finds more than two-thirds fail to create value, usually because a buyer assembled cheap add-ons into an incoherent company. Cheap entry does not lower the risk here. It buys a different, wider band of outcomes, and the dispersion in this corner of private equity is the widest there is.
Quick Questions
What is a search fund? A pool of money raised from specialized investors to pay an individual, usually an MBA, a small salary while they look for a company to buy, then to fund the acquisition. The searcher runs the business and earns equity that vests with performance, often up to about 25% of the eventual gain.
What is an independent sponsor? An operator who sources and negotiates an acquisition without a committed fund, then raises the equity for that specific deal from private-equity funds, family offices, or SBA-licensed investment companies. Standard pay runs a 2% closing fee, 5% of EBITDA a year, and 20% to 30% carried interest.
Why are the multiples so low? Small founder-owned businesses trade at a discount because they are illiquid, lack audited financials and management depth, depend on one owner, and attract a thin pool of buyers. That discount is the opportunity and the risk at once.
Is an SBA loan the same as venture funding? No. An SBA loan is government-backed debt that the buyer personally guarantees, often with a life-insurance requirement. Venture funding is equity with no personal guarantee. The SBA route hands over control cheaply and loads the downside onto the individual.
The Business Model Analyst Take
The headline sells grit. The spreadsheet sells arbitrage. These buyers are running the private-equity value-creation engine as solo operators, and the return math rests on buying trades businesses at 1.8x to 5x from sellers with no other options, then exiting into a market that pays 7x and up for scale.
The model works cleanly on paper and unevenly in practice, because it leans on two conditions that are both wobbling. The premium exit multiple assumes a private-equity roll-up market ready to buy, and that market is sitting on record-low distributions and a backlog of companies it cannot sell. The cheap entry multiple assumes a quiet field of retiring owners and few rival bidders, and that field now has 1,400 independent sponsors and a business-school pipeline pouring in. An arbitrage this legible does not stay this wide.
For anyone weighing the jump, the useful question is not whether people are getting rich doing this. Some are. The question is what you are underwriting: an operating business you can grow, or a bet that the multiple gap survives the crowd and the exit thaws in time for your turn. The first is a business. The second is a trade dressed as one.
Reporting by Miriam Gottfried for The Wall Street Journal, July 17, 2026. Market multiple data from GF Data, Capstone Partners, and PitchBook. Search fund figures from Stanford GSB; independent-sponsor count from McGuireWoods.