
The hosts of the Acquired podcast credited ESPN with funding Pixar, Marvel, Lucasfilm and two theme parks. Disney’s own capital budget shows the harvest never stopped.
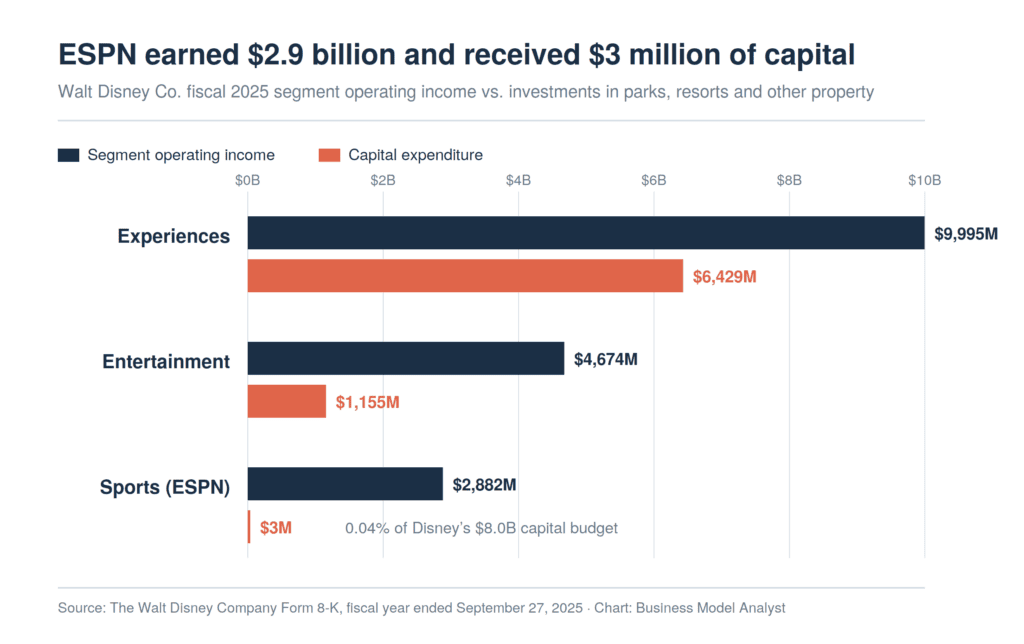
In fiscal 2025 the Sports segment delivered $2,882 million of operating income to Disney and received $3 million of capital expenditure. Experiences, the segment ESPN’s cash helped build, delivered $9,995 million and received $6,429 million. Disney is not debating whether to spin off ESPN. It is running ESPN as a mine.
Ben Gilbert and David Rosenthal published a piece in the Wall Street Journal on Thursday arguing that the biggest blockbuster Disney ever made was a cable channel in Bristol, Connecticut. They estimate ESPN threw off close to $75 billion of operating profit over 30 years, several times the combined cost of Pixar, Marvel, Lucasfilm and the Shanghai and Hong Kong parks. The argument is correct and the evidence is stronger than they used. It sits in the capital expenditure table of Disney’s most recent annual filing, where the Sports line reads $3 million against a company total of $8,024 million.
What Happened
The Acquired hosts laid out the mechanics of Disney’s acquisition run. Disney bought Capital Cities/ABC for $19 billion in 1995 and got ESPN inside it. Under Disney, ESPN raised average monthly carriage fees from under $1.00 per cable subscriber to close to $10.00, three times the rate of the next-highest cable channel, and reached 100 million US households by 2011 out of 115 million households in the country. By the mid-2000s analysts put ESPN at roughly 40% of the operating profit of all of Disney.
The clever part was the financing sequence. Bob Iger bought Pixar in 2006 for $7.4 billion in an all-stock deal that issued 279 million new shares. Disney then spent ESPN’s cash on buybacks and erased the dilution inside about 18 months. Disney ran the same play on Marvel in 2009 and Lucasfilm in 2012, and in the Lucasfilm year the buyback pace was heavy enough to shrink total shares outstanding.
Gilbert and Rosenthal close by noting that ESPN still generated close to $3 billion of operating income in fiscal 2025 and comparing it to a 41-year-old LeBron James: past his prime, still scoring.
The Backstory
Disney’s fiscal 2025 filing, for the year ended 27 September 2025, gives the exact figures. Total segment operating income came to $17,551 million: Experiences $9,995 million, Entertainment $4,674 million, Sports $2,882 million. Sports revenue was $17,672 million against Experiences revenue of $36,156 million.
Sports now contributes 16.4% of Disney’s segment operating profit. In the mid-2000s ESPN contributed around 40%. Experiences contributes 56.9%.
The distribution base explains part of that. ESPN peaked at 100.1 million linear homes in 2011 per Nielsen and industry estimates now put it near 55 million. Rights costs moved the other way. ESPN pays about $2.6 billion a year for NBA rights against roughly $1.5 billion under the previous deal, and about $2.7 billion a year for its NFL package, with the NFL renegotiation still ahead.
Disney’s board answered the question the numbers were asking. In February it elected Josh D’Amaro, who ran Experiences and its $36 billion of fiscal 2025 revenue, as chief executive. He took over on 18 March. Jimmy Pitaro, chairman of ESPN, was considered early and dropped from the shortlist. The person who ran the asset ESPN bought now runs the company; the person who runs ESPN does not.
The Plan
Disney told investors what fiscal 2026 looks like: roughly $9 billion of capital expenditure, $24 billion of content investment across Entertainment and Sports, and low-single-digit operating income growth for Sports. Almost all of the capital goes to cruise ships and park capacity.
The third-quarter print on 5 August confirmed the shape. Revenue rose 7% to $25,248 million and total segment operating income rose 21% to $5,555 million. Experiences delivered $3.02 billion on record revenue of $9.97 billion. Entertainment operating income rose 64% to $1.68 billion, and streaming ran a 12.9% margin. Sports revenue rose 4% to $4.5 billion while Sports operating income fell 17% to $858 million on higher programming costs and shorter NBA playoff series. ESPN posted its most-watched fiscal third quarter since 2016 and still earned less than the year before.
Disney also raised its fiscal 2026 buyback target to at least $9 billion, the largest in nine years, and earmarked the roughly $1.2 billion from selling its 50% stake in A+E Global Media to Hearst for more repurchases. The buyback engine the Acquired piece describes is running again. ESPN is no longer feeding it.
The Business Model Angle
Two lines in Disney’s cash flow statement carry the whole argument. Sports capital expenditure in fiscal 2025 was $3 million. Sports depreciation was $48 million. Disney wrote down ESPN’s asset base 16 times faster than it replaced it.
That is what a harvest looks like in accounting terms. Management collects the cash, funds nothing new, and lets the physical base run off. Every dollar Disney spent on Sports property in fiscal 2025 returned $961 of segment operating income for the year. Experiences returned $1.55. Entertainment returned $4.05. Those ratios do not measure quality. They measure intent.
The usual objection is that media is asset-light and parks are asset-heavy, so the comparison is unfair. Entertainment settles it. Entertainment is also asset-light and received $1,155 million, or 385 times what Sports received.
Run the arithmetic on the $75 billion figure and something else appears. Spread over 30 years it averages $2.5 billion a year. Fiscal 2025 came in at $2.88 billion, about 15% above ESPN’s own long-run mean, achieved on roughly half the households. The declining asset is currently earning more than its lifetime average. Disney extracted that by raising price per home faster than homes disappeared, for fifteen straight years, while refusing to reinvest.
The transferable lesson for anyone running a portfolio of business units sits in the comparison, not in Disney’s nostalgia. Disney’s celebrated flywheel of characters into merchandise into park attractions was not self-funding during the period everyone cites as proof it works. In 2006 Pixar carried a $6 billion market capitalisation and Disney held under $2 billion of cash. The flywheel could not buy its own fuel. A cable annuity bought it.
Most companies holding a melting annuity spend it on the annuity: better product, defensive pricing, one more rights cycle. Disney spent it somewhere else and ended up owning Toy Story, the Marvel slate, Star Wars and Shanghai. Check whether your best margin line is funding itself or being funded, because a subsidised flywheel looks identical to a self-funding one until the subsidy stops.
The Risk
The strongest counterargument to all of this is that ESPN’s real capital never touches the capex line. Sports rights are the investment, they run through the income statement as programming expense, and Disney’s $24 billion content budget covers Entertainment and Sports together. On that reading ESPN absorbs billions of capital a year and the $3 million figure is an accounting artefact.
The distinction still matters. Rights are rented. When the contract ends Disney owns nothing, which is why Warner Bros. Discovery’s linear operating expenses dropped 23% the moment the NBA came off its books. A cruise ship stays on the balance sheet for 30 years. Disney is spending heavily to keep ESPN’s revenue alive while putting nothing into ESPN’s own asset base, and those are different commitments.
The genuine risk runs the other way. Q3’s 17% decline in Sports operating income, on rising viewership, suggests rights inflation is now outrunning price increases. If the NFL renewal lands where the market expects, ESPN’s contribution could fall below $2 billion while Disney’s dependence on parks and cruise capacity grows. Experiences also has its own exposure: international attendance is soft, Shanghai and Hong Kong stayed weak through Q4 guidance, and D’Amaro is putting $9 billion a year into physical assets in a consumer environment nobody can forecast. A company that swapped a melting annuity for durable assets has to make sure the durable assets stay durable.
Quick Questions
Did ESPN actually pay for Pixar, Marvel and Lucasfilm? Indirectly. Disney bought them mostly with stock, then used ESPN’s cash flow to buy the stock back. The combined announced prices were $7.4 billion, $4 billion and $4.05 billion.
Is ESPN still Disney’s biggest profit centre? No. Experiences has been the largest for several years, at $9,995 million of fiscal 2025 operating income against Sports at $2,882 million.
Why does Disney spend almost nothing on Sports capex? ESPN’s costs are rights and production, which are expensed rather than capitalised, and Disney has chosen not to build new physical infrastructure for it. Sports capex was $3 million in fiscal 2025 and $10 million in fiscal 2024.
Will Disney spin off ESPN? Analysts keep asking. Nothing in the fiscal 2026 plan points that way, and companies rarely divest an asset while it still returns $961 of profit per dollar of capital invested.
The Business Model Analyst Take
Gilbert and Rosenthal wrote a victory lap for a trade that most companies never complete. Disney held an annuity with a visible expiry date and converted it into assets that keep earning after the annuity dies. Nokia held one and spent it on Symbian. Intel held one and spent it on defending x86 fabs. Kodak held one and spent it on film.
The conversion has a deadline, and Disney’s is close. Sports contributes 16.4% of segment profit and falling. The buyback engine now runs on park cash flow and asset sales. The chief executive came from the segment ESPN paid for.
Anyone sitting on a high-margin line with a shrinking customer base should read the Disney case as a clock rather than a compliment. The cash keeps arriving for years after the strategic position is gone, which is exactly what makes it easy to spend on the wrong thing. Disney spent it on Buzz Lightyear and a park in Shanghai. Ask what your version of that purchase is, and whether you are still early enough to make it.