
Equinox has spent 30 years convincing affluent professionals that a gym membership is a status object. The Wall Street Journal recently framed the payoff as a “$4,000-a-year habit,” the rough all-in cost of dues, initiation, and a little personal training. That number is real, but it badly undersells the strategy. For Equinox, $4,000 is the floor. The actual ambition runs an order of magnitude higher, and understanding why is the key to understanding the whole business.
What Equinox Actually Sells
Equinox does not compete on equipment, square footage, or price. It competes on identity. The product is the feeling of belonging to a high-performance class, delivered through curated lighting, hospitality-grade service, boutique classes, and an address that signals you can afford it. The gym is the wrapper. The margin lives in what the wrapper lets Equinox sell next.
This is the opposite of the volume game. The Planet Fitness business model works by packing millions of low-cost members into judgment-free boxes and betting most of them never show up. Equinox inverts every variable: fewer members, higher dues, heavy usage encouraged, and a relationship designed to deepen over years rather than lapse quietly. Planet Fitness monetizes absence. Equinox monetizes attachment.
That attachment is the asset. Once someone reorganizes their morning, their social life, and their self-image around a club, they are no longer a $250-a-month member. They are a lead for everything else Equinox can attach to the wellness identity they just bought.
The Real Model Is a Spend Ladder
The base membership is a customer-acquisition tool. What matters is average revenue per member, and Equinox has built a ladder designed to lift it relentlessly.
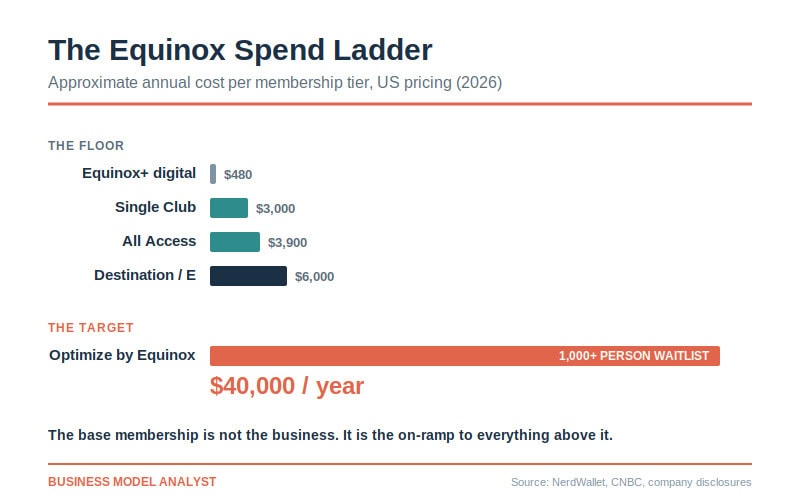
A single-club member paying roughly $3,000 a year is one personal-training package away from doubling their spend. In New York, training runs $150 to $250 per session, so a member training three times a week quietly turns a $3,000 relationship into a $25,000 one. Add spa, nutrition, and recovery services, and the “$4,000 habit” becomes a floor almost nobody who is engaged actually stays on.
Then comes the top of the ladder. Optimize by Equinox, launched in 2024, costs $40,000 a year and bundles personal training, nutrition, sleep coaching, massage, a health concierge, and twice-yearly testing of 100-plus biomarkers through a partnership with lab company Function Health. Executive Chairman Harvey Spevak has described demand as “insatiable,” pointing to a waitlist of more than 1,000 people. The pitch is explicit: health is the new luxury, and the wealthy now spend on invisible assets like sleep scores and metabolic markers the way they once spent on watches.
The Longevity Bet
Optimize is the sharp end of a broader wager that Equinox can move from selling fitness to selling measurable health. The wellness market is projected to reach nearly $10 trillion by 2030, up from roughly $6.8 trillion in 2024, and Equinox is positioning its brand as the premium on-ramp to it.
The GLP-1 wave has handed the model an unexpected tailwind. As drugs like Ozempic drive rapid weight loss and the muscle loss that comes with it, premium operators have launched muscle-preservation training tracks, repositioning the gym from weight-loss center to metabolic maintenance clinic. That reframing justifies clinical-grade pricing and locks in high-net-worth members through their own health data, which is a far stickier retention mechanism than a nice locker room.
Hotels, Residences, and the Real Estate Flywheel
The most capital-intensive layer of the model is hospitality. Equinox opened its first hotel at Hudson Yards in 2019, a 212-room property that took years to reach profitability and now serves as proof of concept. The plan is roughly 33 properties over the next decade, spanning urban clubs and resorts, with sites confirmed or in development in Nashville, Saudi Arabia’s Amaala on the Red Sea, and a marina resort in Anguilla.
The financial engineering here matters more than the marble. Equinox is majority-backed by Related Companies, the real estate developer behind Hudson Yards, and hotel deals increasingly lean on branded residences to make the numbers work. Equinox-branded apartments sell the lifestyle as real estate, generating development margin and a permanent, non-churning membership base attached to the building. It is the same recurring-access logic that Soho House proved: the room is almost secondary to the membership.
The Competitive Reality Check
Here is where the skeptic earns their keep. Equinox is private and discloses no financials, and outside estimates of its revenue range wildly from a few hundred million to a few billion depending on what gets counted. The one clean comparable is public. Life Time Group, the other premium operator, generated roughly $2.98 billion in 2025 revenue with EBITDA above $820 million, grew double digits, and did it with a country-club, suburban, family-oriented model that Wall Street can actually underwrite. Life Time is the proof that premium fitness can compound. It is also proof that Equinox does not own the category it defined.
The macro backdrop cuts both ways. Analysts describe a “K-shaped” economy in which affluent consumers keep spending on wellness while budget consumers pull back. That is pure tailwind for Equinox today. It is also the model’s single biggest vulnerability: a business built entirely on top-decile discretionary spending has no cushion if that decile ever flinches. Planet Fitness has a floor of price-sensitive members who return in downturns. Equinox has no such floor.
And the operational history is not spotless. Equinox’s budget arm, Blink Fitness, filed for bankruptcy in 2024 and was sold to PureGym for $121 million. SoulCycle, acquired in 2011, faded hard post-pandemic. The company paid a $600,000 settlement to New York in 2025 over hard-to-cancel memberships, and it carries the reputational residue of a 2019 boycott tied to an investor’s political fundraising. These are the frictions of a brand that sells virtue at a premium: every stumble is measured against the promise.
The Business Model Analyst Take
Equinox is not really a gym company, and reading it as one is the mistake. It is a luxury brand that happens to use fitness as its most efficient customer-acquisition channel. The clubs exist to manufacture attachment, and attachment is what gets monetized through an ever-lengthening ladder of training, longevity services, hotels, and residences. The “$4,000 habit” is the trailhead, not the destination.
The strategy is genuinely strong where the brand does the heavy lifting. Equinox has pricing power almost no fitness operator can match, a secular $10 trillion wellness tailwind, and a plausible path to Soho-House-style recurring revenue through real estate. That is a defensible flywheel, and it is the same “own the experience” logic visible in the Lululemon business model and, at the demand-led extreme, the economics of Hyrox.
But two hard truths sit underneath the gloss. First, Optimize is a brand halo, not yet a financial pillar: 1,000 members at $40,000 is roughly $40 million, a rounding error against a revenue base measured in hundreds of millions or more. Its job right now is to make the $6,000 tier feel reasonable, and it does that job beautifully. Second, the hotel push is slow, capital-hungry, and dependent on outside real estate money, with exactly one proven property to date and an open question about whether “high-performance hospitality” travels beyond Manhattan.
The honest read: Equinox has the best brand in the category and a monetization ladder most operators would envy, but its entire model is a leveraged bet on affluent wellness spending never cooling. In the current economy that bet is winning. Operators studying Equinox should copy the ladder logic, which is applicable anywhere, and treat the wealth-only positioning as the strategic choice it is, powerful on the way up and fragile on the way down.