
Reselling a ticket above face value was a misdemeanor in much of America for most of the last century. Today the biggest names in live events run the resale market themselves and take a cut from both sides of every trade. Here is how scalping got institutionalized, and why it became one of the best business models in entertainment.
Ticket resale is the secondary market for event tickets: the buying and selling of seats after their first sale, usually at a price the original seller no longer controls. For decades it lived on street corners and was treated as a petty crime. The economics flipped when platforms realized the resale itself was a fee-generating product. The key takeaway: the modern resale business is not about selling tickets, it is about owning the marketplace and charging a percentage of someone else’s markup, on both ends of the deal.
The reason this matters now is the 2026 World Cup. FIFA built its own resale marketplace, removed price caps in the United States and Canada, and applied a fee to the buyer and the seller. It is the clearest example yet of a once-illegal practice turned into a line item on a balance sheet.
Picture a season-ticket holder who can no longer make a game. Twenty years ago they either ate the cost or found a scalper outside the stadium. Today they list the seat on the same app that sold it, a stranger buys it at a markup, and the platform quietly skims a fee from each of them before either party knows what the other paid. Nobody broke a law. Everybody paid the house.
The core mechanic: primary versus secondary
Every ticket has two possible markets. Understanding resale economics starts with separating them, because the money behaves very differently in each.
| Primary market | Secondary market (resale) | |
|---|---|---|
| Who sets the price | Artist, team, promoter, venue | The reseller, or an algorithm |
| What the platform earns | Service and processing fees on face value | A fee on the resale price, often from both buyer and seller |
| Price ceiling | Set by the issuer | Set by demand, capped only where law requires |
| Inventory cost to platform | None, it is the issuer’s ticket | None, it is the reseller’s ticket |
| Risk carried by platform | Low | Low |
The structural insight sits in the bottom rows. The platform never owns the ticket and never carries inventory risk, yet it collects a percentage of a price that can run many times above face value. That is the whole game. Resale is an asset-light, demand-priced tollbooth, and the toll is paid twice.
Where the money actually comes from: the fee stack
The cleanest way to see resale economics is to follow a single transaction. Take a ticket listed at $1,000 on FIFA’s World Cup 2026 Resale Marketplace, which charges 15% to the buyer and 15% to the seller.
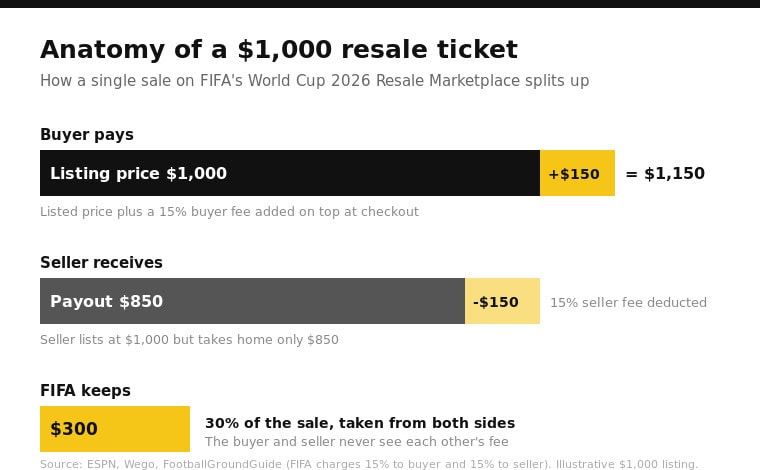
The seller lists at $1,000 but takes home $850. The buyer sees $1,000 but pays $1,150. FIFA collects $300 on a single resale, roughly 30% of the headline price, and it never touched the inventory. The two fees are invisible to each other, which is the point. Each party feels like they paid a reasonable 15%, while the platform’s effective take is double that.
This double-sided fee is the defining feature of modern resale, and it is exactly what street scalpers could never do. A scalper made a spread by buying low and selling high, carrying the risk that the ticket would not move. The platform carries no inventory risk and charges a percentage regardless of whether the reseller wins or loses on the trade.
Who skims the most
Not every platform takes the same cut, and a few are forced by law or competition to take nothing above face value. Lined up side by side, the spread is wide.
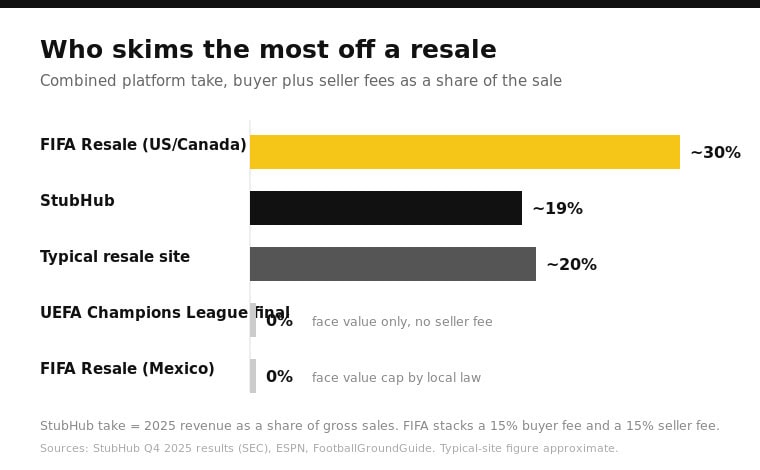
| Platform | Combined take | Price cap |
|---|---|---|
| FIFA Resale (US and Canada) | About 30% (15% + 15%) | None |
| Typical resale site | Around 20% | None in most states |
| StubHub | About 19% of gross sales | None |
| FIFA Resale (Mexico) | 0% above face | Face value, by local law |
| UEFA Champions League final | 0% above face | Face value, no seller fee |
The contrast inside FIFA’s own system is the tell. In the United States and Canada, where the law allows it, FIFA runs an uncapped market and charges 30%. In Mexico, where resale above face value is illegal, the very same organization runs a face-value-only marketplace and forgoes the markup entirely. The fee structure is not a moral position. It is whatever the local rules permit.
How it went from illegal to legal
The thing people forget is that resale used to be genuinely prohibited. The shift from misdemeanor to monetized product happened gradually, and mostly by deregulation rather than any grand policy decision.
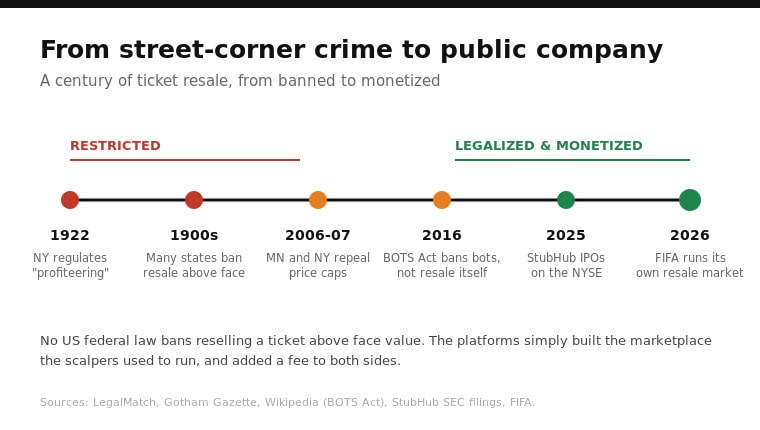
| Year | What changed | Effect |
|---|---|---|
| 1922 | New York first regulates ticket “profiteering” | Resale above a cap becomes a violation |
| Mid-1900s | Many states adopt anti-scalping laws | Resale above face restricted or banned |
| 2006 | Minnesota repeals a law that stood ~50 years | Most scalping becomes legal there |
| 2007 | New York scraps its 10% / $5 markup cap | No price ceiling on resale |
| 2016 | Federal BOTS Act passes | Bans buying bots, not resale itself |
| 2025 to 2026 | StubHub goes public, FIFA runs its own resale | Resale is now a public-company line item |
Two facts do the heavy lifting here. First, there is no federal law in the United States banning the resale of a ticket above face value. The BOTS Act, the one major federal intervention, targets the automated bots that hoard tickets, not the markup itself. Second, the states that once restricted resale mostly repealed those rules as unenforceable. The legal vacuum did not appear by accident. It was the opening the platforms walked through.
Case study one: FIFA turns the World Cup into a resale engine
The 2026 World Cup is the most aggressive version of this model yet. FIFA introduced dynamic ticket pricing at a World Cup for the first time, the same demand-based pricing airlines and hotels use, and paired it with a resale marketplace that takes 30% per trade.
The numbers got loud fast. Group-stage tickets that started near a $60 floor for some matches climbed steeply, and on FIFA’s resale market the average cheapest group-stage seat in Los Angeles ran past $1,000 two months out. Final listings reached into five and six figures, with some seats posted above $2 million. The attorneys general of New York and New Jersey subpoenaed FIFA over pricing that they said far exceeded any previous World Cup.
Here is the part the outrage coverage misses. Dynamic pricing cuts both ways. At the recent FIFA Club World Cup, some knockout tickets fell to as little as $13 when demand softened. The algorithm is not built to gouge, it is built to clear inventory at whatever the market will bear, up or down. FIFA wins either way, because its 15% plus 15% applies to the resale price no matter which direction it moves.
For contrast, the UEFA Champions League final the same year capped resale at face value with no seller fee at all. Same sport, same continent, opposite philosophy. That is what makes FIFA’s choice a business-model decision rather than an inevitability.
Case study two: Ticketmaster and the vertical integration play
If FIFA shows the model at an event, Live Nation shows it as a permanent machine. When Live Nation and Ticketmaster merged in 2010 under a Justice Department consent decree, the combined company ended up controlling both the primary sale and the resale of the same ticket, often through the same checkout. Critics call it legalized scalping, because a ticket can be resold at a steep markup on the very platform that issued it.
The mechanism is subtle and that is why it works. A 2019 Billboard investigation found Live Nation had at times moved tickets directly to resellers, at the request of the artists involved, instead of the open market. And in September 2025 the Federal Trade Commission, joined by seven states, accused Ticketmaster of letting resellers blow past the purchase limits artists set, alleging the company collected $3.7 billion in resale fees between 2019 and 2024.
Live Nation’s defense is revealing. The company says revenue from concert ticket resale is less than 2% of its total revenue, against roughly $25 billion in 2025 revenue overall. Both things can be true at once. Resale is a small slice of a giant pie, and $3.7 billion over six years is still an enormous amount of money to collect on inventory you do not own. Small percentage, large absolute number. That is what a tollbooth on a busy road looks like.
Case study three: StubHub, the pure-play
To see resale economics with nothing else attached, look at StubHub. It does not promote concerts or run venues. It is a two-sided marketplace, and almost nothing else, which makes its financials the cleanest x-ray of the model.
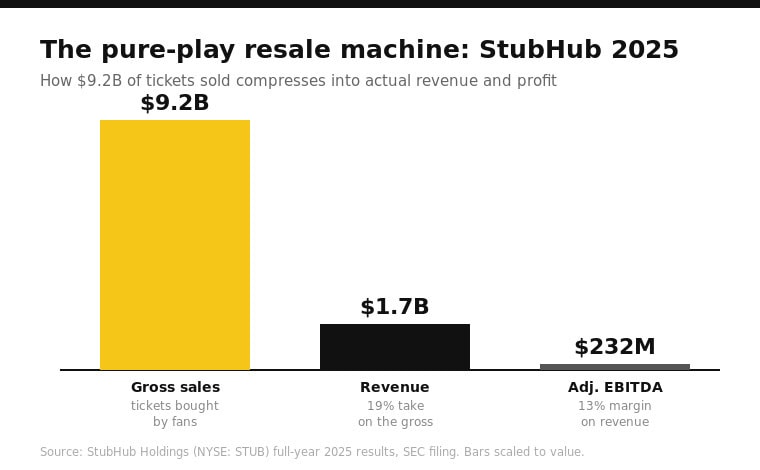
In 2025 StubHub moved $9.2 billion in gross merchandise sales, the total fans paid, and booked $1.7 billion of that as revenue. That is a 19% take on money flowing between strangers. Adjusted EBITDA was $232 million, a 13% margin, on more than 40 million tickets sold by over a million sellers across 200 countries. Average order value sits around $250.
StubHub went public on the NYSE in September 2025 at $23.50 a share. Worth noting: it posted a $1.9 billion net loss for the year, but the bulk of that was a one-time stock-compensation charge tied to the IPO, not a sign the marketplace itself loses money. The underlying engine throws off cash. The company guided to roughly $10 billion in gross sales for 2026.
The strategic lesson for founders sits in that 19% take on a business that owns no inventory. StubHub describes itself as the leader in an $18 billion North American secondary market and pegs the global secondary ticketing opportunity at over $150 billion in gross sales. Third-party analyst estimates of the market’s size vary wildly, so treat any single figure with caution, but the direction is not in doubt.
The business-model angle: why everyone wants in
Strip away the specifics and resale checks every box a marketplace founder dreams about. The pattern repeats across FIFA, Ticketmaster, StubHub, SeatGeek, and Vivid Seats for the same reasons.
| Property | Why it is attractive |
|---|---|
| Asset-light | The platform never buys inventory or carries unsold-ticket risk |
| Two-sided fees | A cut from the buyer and the seller on the same transaction |
| Demand-based pricing | Revenue rises with the markup, and the markup rises with scarcity |
| Emotional urgency | Fans buy under time pressure for a one-time event, which suppresses price sensitivity |
| Network effects | More sellers attract more buyers, which attracts more sellers |
| Recurring liquidity | Sports seasons and tours generate a steady stream of last-minute inventory |
The emotional-urgency point is underrated. A ticket is a perishable good with a hard deadline and no substitute. You cannot buy the final next week. That combination of scarcity, urgency, and irreplaceability is what lets the markup hold, and the platform monetizes the markup. It is one of the few consumer businesses where the customer’s desperation is a structural feature, not a bug.
The risk: regulation, fraud, and fan revolt
This is not a clean story, and pretending otherwise would be dishonest. The model has three live threats.
Regulation is circling. The United Kingdom proposed a price cap on resale tickets in 2025, and a US presidential executive order in March 2025 directed the FTC to intensify enforcement against ticket bots. Mexico’s face-value-only law already shows how a single jurisdiction can switch off the markup entirely. The 30% take exists at the pleasure of lawmakers who could change their minds.
Fraud is the dark side of liquidity. In May 2026 the FBI’s Internet Crime Complaint Center warned that criminals were cloning FIFA’s website to sell fake tickets. Every dollar of trust the official platforms build is a dollar the scammers try to steal, and high-profile fraud erodes confidence in the whole secondary market.
Then there is the fan. The same dynamic pricing that maximizes revenue also prices out the ordinary supporter and risks the cultural value of the event itself. When a group-stage World Cup seat in your own city costs more than a transatlantic trip to the Champions League final, the goodwill that makes the product valuable starts to leak. A business that monetizes its most passionate customers’ desperation is always one backlash away from a regulatory or reputational reckoning.
Quick questions
Is reselling tickets above face value illegal? In most of the United States, no. There is no federal ban on resale above face value, and most states have repealed or stopped enforcing their old anti-scalping caps. A handful still restrict it, and some countries like Mexico cap resale at face value, so the answer depends entirely on where the sale happens.
How does FIFA make money on resale? FIFA charges a 15% fee to the buyer and a 15% fee to the seller on its official 2026 World Cup Resale Marketplace, roughly 30% of the resale price combined. In the United States and Canada there is no price cap, so the fee scales with the markup.
What is the difference between a scalper and a resale platform? A scalper buys tickets and resells them at a spread, carrying the risk that they will not sell. A platform owns no inventory, carries no risk, and instead charges a percentage fee on other people’s resales, usually from both sides.
How much money is in ticket resale? StubHub alone processed $9.2 billion in gross ticket sales in 2025 and calls the global secondary ticketing market worth over $150 billion in gross sales. Estimates from analysts vary widely, but it is unambiguously a multi-billion-dollar industry.
The Business Model Analyst Take
The interesting thing about ticket resale is not that it is expensive. It is that the practice barely changed while the business model around it changed completely. The same fan reselling the same seat at the same markup was a criminal in 1980 and a customer in 2026. What moved was who captured the spread.
Scalpers took the risk and kept the markup. Platforms took none of the risk and kept a percentage of the markup, from both sides, at scale, on inventory they never owned. That is the entire innovation, and it is a genuinely elegant one. FIFA, Live Nation, and StubHub did not invent demand for sold-out events. They inserted a tollbooth into a transaction that was already happening, then made the tollbooth feel like a service.
For founders, the lesson is sharper than “ticketing is lucrative.” It is that the most durable margins often come from intermediating a transaction other people are already determined to complete, rather than from creating the demand yourself. The catch, and it is a real one, is that a business built on monetizing your customers’ urgency has no natural defense when those customers, or their elected representatives, decide they have had enough. The 30% take is the strategy. It is also the liability.