
Sellers negotiate earnouts backwards. They spend their leverage on the size of the payment and the length of the period, then sign whatever the buyer’s counsel drafted for the measurement clause. The size is the part that sounds like money. The measurement clause is the part that decides whether any money moves.
An earnout hands the buyer three things at once: the business, the books that record the business, and the right to define the number those books produce. The seller keeps a claim against that number. Everything that follows in this article is about what happens to a claim when the person on the other side owns the thing being claimed against.
Earnout: a portion of the purchase price the buyer pays after closing, and only if the acquired business hits performance targets defined in the acquisition agreement. The buyer records it at signing as contingent consideration. The seller records it as an unsecured, subordinated, unfunded claim that depends on someone else’s operating decisions and someone else’s accounting elections.
The instrument you are selling into
Ask what an earnout is and most advisers will tell you it bridges a valuation gap. That describes the negotiation, not the instrument.
Look at the cash flows instead. The seller transfers the asset at closing and receives a fixed payment plus a contingent right. The contingent right pays off on a number the seller no longer produces, no longer audits, and in most deals no longer sees. The seller has written a short-dated option and handed the counterparty the pen that writes the underlying.
That framing changes what you negotiate for. If an earnout were a payment plan, the interesting terms would be amount and timing. Because it is a claim on a controlled variable, the interesting terms are the definition of the variable, the constraints on the person controlling it, and the process for arguing about the result. In the sections below, those three sit at the center of every dollar of documented earnout shortfall.
What earnouts pay: 21 cents on the dollar
SRS Acquiom administers post-closing payments and shareholder representation on thousands of private-target deals, so it sees the settlement side that deal-terms studies never capture. Its market data puts earnout achievement at roughly 21 cents for every dollar of maximum earnout written into US private-target agreements outside life sciences. Fifty-nine percent of earnouts pay something. At least 28% get contested. Of the deals that pay, 17% required a renegotiation to keep the parties out of court.
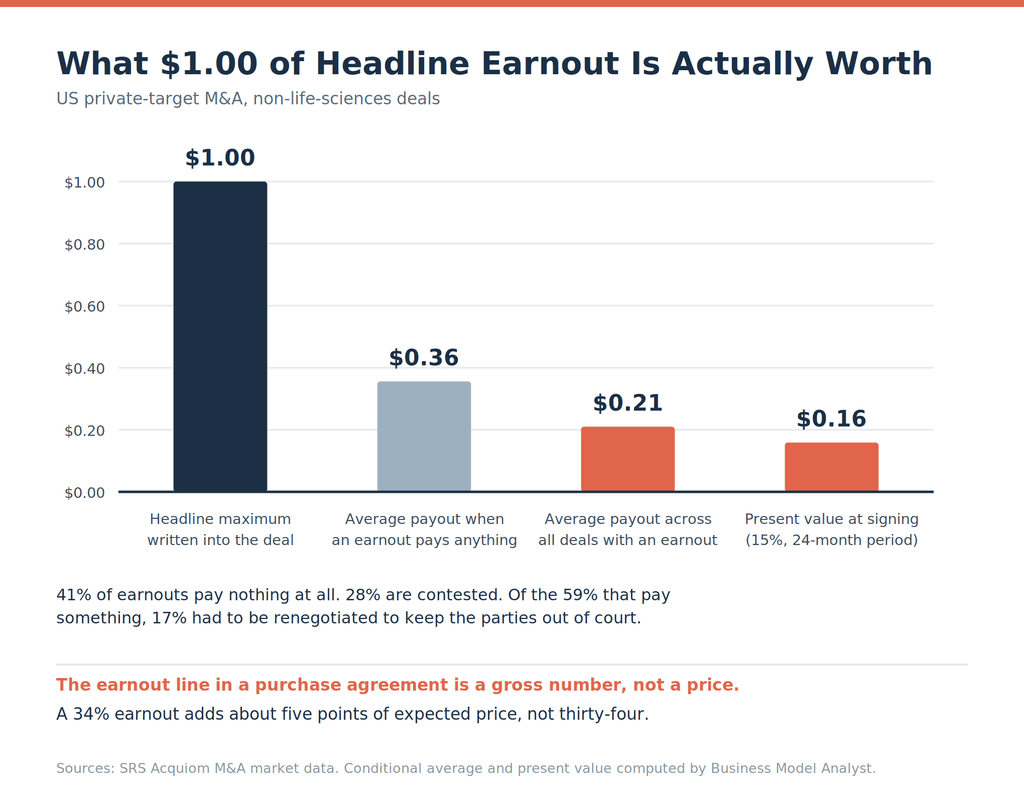
Run the arithmetic those figures imply. If the average across all earnout deals is 21 cents and 59% of them pay anything at all, the average payment among the deals that do pay is about 35.6 cents of the maximum. Two out of five earnouts pay zero. The modal outcome on the most-negotiated number in the agreement is nothing.
Now price it. The median earnout in the 2026 SRS Acquiom study runs 34% of the closing payment, up from 31% the year before, and the market has moved toward shorter windows: 38% of earnouts run one to two years, 23% run a year or less, 20% run two to three years. Take a 34% earnout over 24 months, apply the 21% expected payout, and discount at 15% for the risk that the counterparty controls the outcome. The earnout contributes about 5.4 points of expected price on top of the closing payment.
A seller who accepts $10 million at closing plus a $3.4 million earnout has not agreed to a $13.4 million deal. On the base rates, that seller has agreed to something closer to $10.5 million with a lottery ticket attached. Buyers know this. It is the reason earnouts get offered.
Two studies, opposite directions
Anyone quoting an earnout prevalence figure is quoting one of two studies, and in 2025 the two disagreed about which way the practice was moving.
The ABA’s Private Target Mergers and Acquisitions Deal Points Study, published December 16, 2025, found earnouts in 18% of its sample, down from 26% in the prior edition. Its 139 agreements all involve a private target bought by a public company, at prices between $25 million and $900 million, with most deals under $200 million. SRS Acquiom’s 2026 study, drawn from more than 2,300 transactions worth $569 billion that closed between 2020 and 2025, found earnouts in 24% of 2025 deals, up from 22% in 2024 and well above the roughly 20% long-run rate. Its separate lower middle-market report puts earnouts in 29% of deals up to $50 million and 35% of deals up to $25 million.
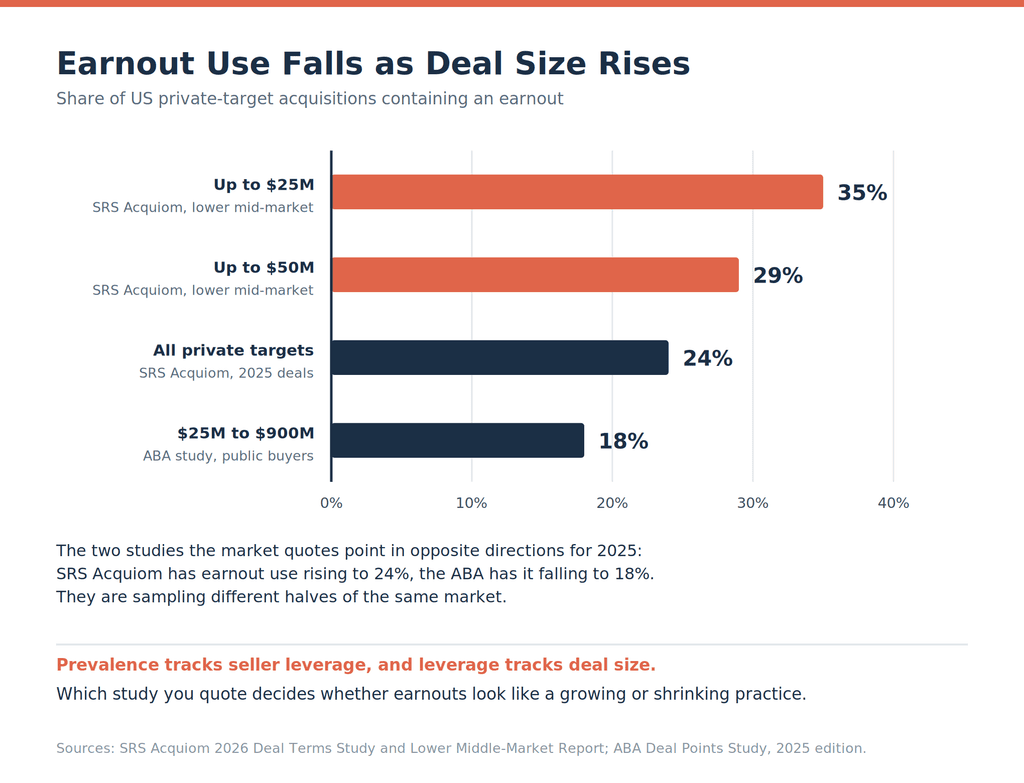
The two studies are not contradicting each other. They are sampling different halves of the market, and earnout prevalence sorts by deal size because it sorts by seller leverage. A founder selling a $12 million services business to a strategic buyer with three other targets in the pipeline takes the earnout. A sponsor running a competitive process on a $400 million asset does not.
Read the ABA number as a statement about the top of the middle market and the SRS number as a statement about everything below it. If you are buying or selling a business that a 7(a) loan could finance, the relevant base rate is 35%, not 18%.
The metric ladder
Pick a metric and you have picked how much discretion to hand over. The choice is usually framed as a fairness question, with revenue described as easier to hit and EBITDA described as harder to game. That gets it backwards.
Revenue is a line the buyer can influence through pricing decisions, revenue recognition policy, and which legal entity books a given sale. Three levers, all visible, all documented in the earnout dispute literature. Every line below revenue adds more.
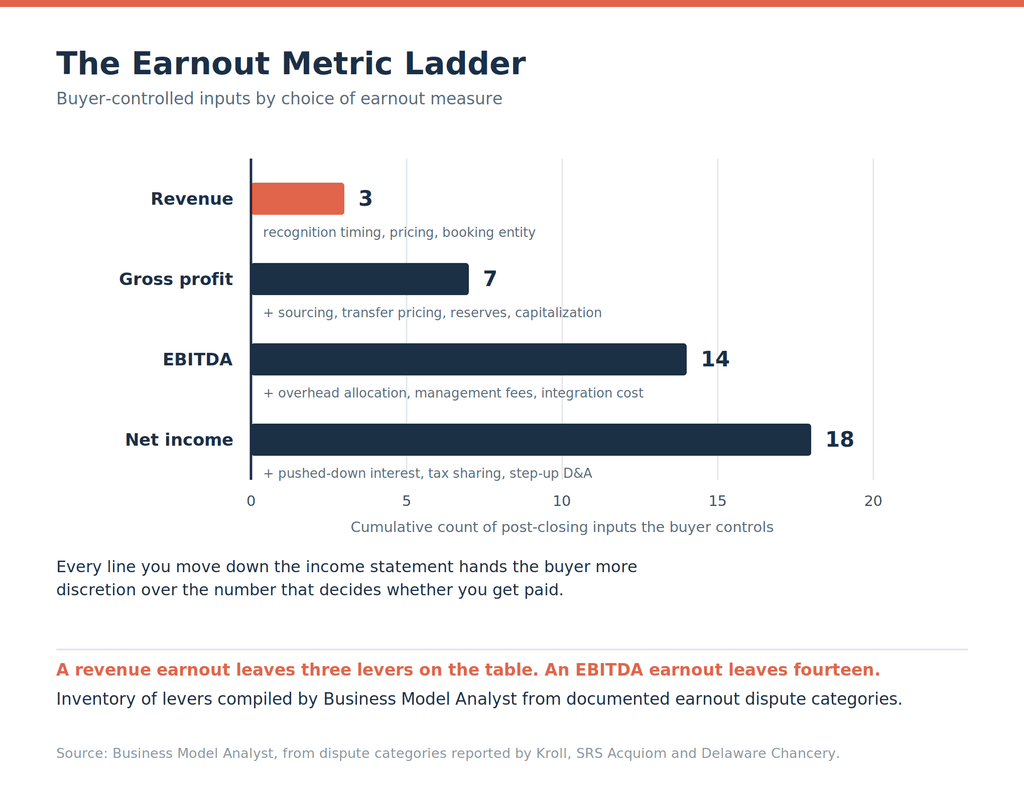
Kroll’s review of earnout deals found that between half and 80% use revenue or EBITDA as the primary measure. Sellers who take EBITDA in exchange for a bigger headline number are buying eleven extra levers of counterparty discretion at a price they never calculated.
The market has already solved this problem in the next clause over. Purchase price adjustments now specify a worksheet, meaning a pre-agreed calculation scheduled to the agreement, in 39% of deals in the 2026 SRS study, against 32% that still say GAAP consistently applied. Sellers fight for a worked example on the working capital true-up, a number worth a few hundred thousand dollars, and then accept an undefined EBITDA definition on the earnout, a number worth several million.
Control: the default is nothing
Absent an express clause, the buyer owes the seller no information about the business after closing. No monthly reporting, no access to the general ledger, no right to talk to the finance team, no right to inspect the calculation that produced the number. SRS Acquiom states the default plainly in its own guidance: the buyer has no legal obligation to provide anything the agreement does not require.
Operating covenants are rarer than sellers assume. Kroll’s data puts the share of earnouts containing a buyer commitment to run the target consistent with past practice at around 17%, with an express commitment to maximize the earnout rarer still. Roughly five in six earnouts leave the operating standard blank and rely on the implied covenant of good faith to fill it. Delaware spent 2026 explaining why that reliance fails.
The clauses worth spending leverage on:
| Clause | Effect |
|---|---|
| Accounting basis, with a worked example | Fixes the metric to the target’s historical method, not the buyer’s post-closing elections |
| Add-back schedule | Names integration costs, allocated overhead, management fees, and buyer-directed spend as excluded from the calculation |
| Operating covenant with a named standard | States whose past practice governs: the target’s, the buyer’s, or an industry benchmark |
| Anti-frustration clause | Bars conduct undertaken with the intent of reducing or avoiding the earnout |
| Information rights | Monthly or quarterly reporting, defined line-item detail, access to named finance personnel |
| Acceleration on change of control or on breach | Converts the contingent claim to a fixed one when the buyer sells or reorganizes the business |
| Dispute process | Expert determination for calculation disputes, with the expert’s mandate and the cost allocation defined |
What Delaware decided in 2026
Three decisions in the first half of 2026 mapped the outer edges of what sellers can expect from a court.
Johnson & Johnson v. Fortis Advisors (Del. Jan. 12, 2026) is the largest of them. J&J bought Auris Health in 2019 for $3.4 billion at closing plus up to $2.35 billion in earnout payments tied to regulatory and sales milestones for surgical robots, and paid none of it. The Court of Chancery awarded the sellers more than $1 billion in 2024. Writing for a unanimous en banc Supreme Court, Justice LeGrow reversed the roughly $300 million attributed to the first milestone. The agreement required J&J to seek one specific FDA clearance pathway. When that pathway closed, the sellers argued the implied covenant obliged J&J to pursue an alternative. The Court held that the regulatory risk was foreseeable at signing, so no gap existed for the implied covenant to fill. The rest of the judgment survived, including findings that J&J breached its commercially reasonable efforts obligations on the other milestones. That agreement contained ten negotiated factors calibrating the efforts standard and an express prohibition on acting with the intent of avoiding an earnout payment, which is why the sellers won anything.
Meyers v. Zimmer Biomet Holdings (Del. Ch. May 1, 2026) shows the other outcome. Vice Chancellor Bonnie David dismissed the commercially reasonable efforts and implied covenant claims at the pleading stage, noting that neither the agreement nor the plaintiff identified any standard against which to measure the buyer’s conduct: not the target’s historical practices, not the buyer’s own practices, not an industry norm. A fraud claim tied to a representation about budget approval survived. An undefined efforts standard is an unenforceable one.
Fortis Advisors LLC v. Krafton, Inc. (Del. Ch. Mar. 16, 2026) is the case sellers should read first, because the seller won and the remedy was operational rather than monetary. Vice Chancellor Lori Will found that Krafton terminated three key employees without contractual cause and seized operational control of Unknown Worlds Entertainment. She reinstated the CEO with full operational authority, extended the earnout period by the length of his ouster, and reserved money damages for a second phase.
Delaware Superior Court has separately allowed implied covenant and prevention-doctrine claims to proceed past dismissal in earnout disputes where sellers alleged affirmative interference, so the doctrine has not disappeared. It has been confined. Courts will police bad faith. They will not write the operating covenant a seller failed to negotiate.
The Krafton arithmetic
The Krafton opinion publishes the earnout formula, which purchase agreements rarely make public, and the formula explains the whole fight.
Krafton bought Unknown Worlds in October 2021 for $500 million at closing plus up to $250 million contingent on studio revenue through the end of 2025, extendable into June 2026. Above a revenue threshold of $69.8 million, Krafton owed $3.12 for every additional dollar of qualifying revenue, capped at $250 million.
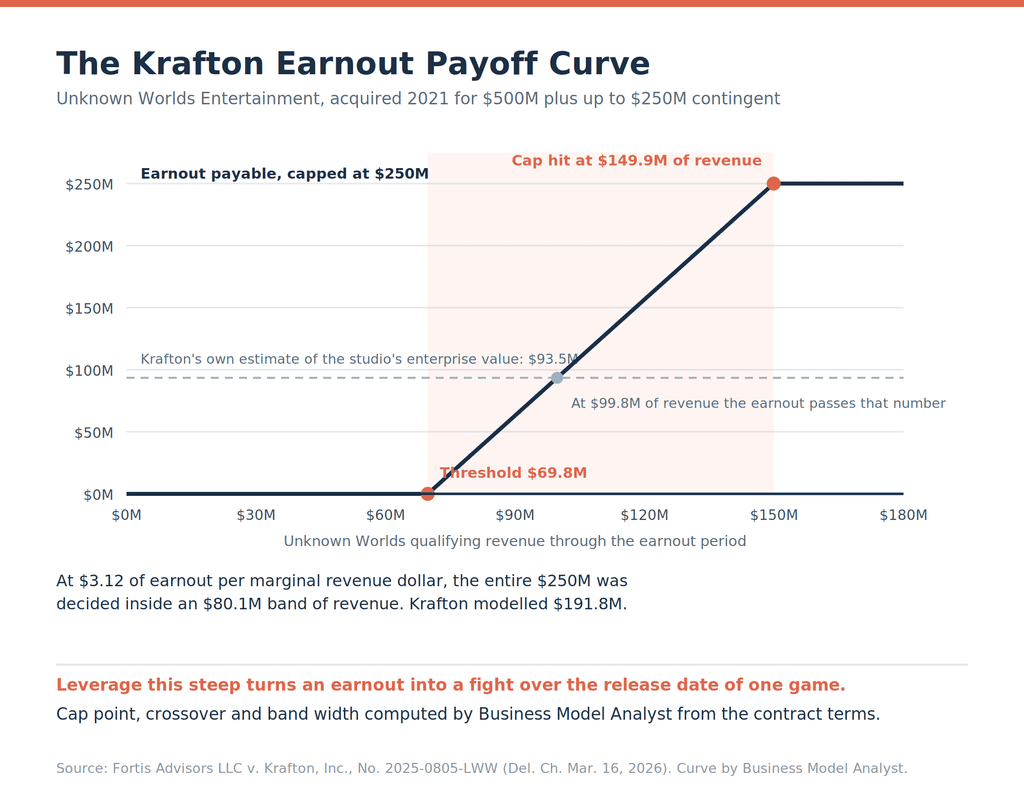
Three numbers fall out of that formula, and Business Model Analyst has not seen any of them published.
The cap is reached at $149.9 million of revenue. Divide the $250 million ceiling by the $3.12 slope and add the threshold. The entire quarter-billion-dollar question therefore lives inside an $80.1 million band of revenue. Below $69.8 million the sellers get nothing; above $149.9 million they get nothing extra. Leverage that steep converts a business-performance clause into a fight over the launch date of a single product, which is exactly what happened.
The earnout passes the buyer’s own view of the asset at $99.8 million of revenue. Krafton’s internal analysis, quoted in the opinion, put the studio’s enterprise value near $93.5 million against a projected $191.8 million earnout in the base case and $242.2 million in the best case. Work backwards through the slope and those projections imply revenue of $131.3 million and $147.4 million. Krafton had written a contract under which strong performance obliged it to pay roughly twice what it believed the whole studio was worth, and the CEO said so in writing before consulting a chatbot about how to escape it.
The founder lock-in was almost nonexistent. If a key employee left during the earnout period, qualifying revenue dropped by $1 million. At the $3.12 slope, that costs $3.12 million of earnout, or 1.25% of the cap. All three walking away would have cost 3.7%. Sellers assume an earnout chains them to the buyer’s org chart. This one priced departure at less than four cents on the dollar, which is why Krafton could not solve its problem by making the founders quit and went after their operational control instead.
Dispute mechanics
Calculation disputes and conduct disputes are different animals and need different forums. A disagreement over whether $2.1 million of allocated overhead belongs in EBITDA is an accounting question that an independent accounting firm can settle in weeks under an expert determination clause. A claim that the buyer moved a product line to a sister entity to suppress the number is a conduct question requiring discovery, and an expert with a narrow accounting mandate cannot reach it.
Agreements that route everything to an accounting expert leave sellers with no forum for the claim that matters. Agreements that route everything to litigation turn a $400,000 arithmetic disagreement into an 18-month case. Name both paths and define which questions go where.
Two procedural points from the 2026 decisions carry beyond their facts. Krafton lost partly on the mend-the-hold doctrine, which barred it from swapping in new justifications for the terminations once its original stated reason failed, and partly on the after-acquired evidence doctrine, which required any post-hoc ground to independently satisfy the negotiated definition of cause. Both doctrines punish a buyer whose contemporaneous paper trail says one thing and whose litigation position says another. Sellers should be documenting the buyer’s stated reasons in real time throughout the earnout period, in writing, while the buyer is still relaxed about giving them.
Accounting and tax push the same way
The buyer’s reported earnings move against the seller. Under ASC 805, contingent consideration goes on the balance sheet at fair value on the acquisition date, and a liability-classified earnout, which covers most cash-settled structures, gets remeasured at fair value every reporting period with the change running through the income statement. Strong performance by the target raises the expected payout, which raises the liability, which books a charge against the buyer’s earnings. A CFO watching an acquired business beat plan watches an expense appear at the same time. Nothing about that is improper, and it means the finance function reports a worse quarter when the sellers are winning.
Tax pushes on the structure from the other side. Where entitlement to an earnout payment depends on the seller staying employed, the accounting and tax analysis treats the payment as compensation for post-combination services rather than as purchase price. That converts capital gain into ordinary income for the seller and a deductible expense for the buyer. Sellers who ask for a retention condition thinking it protects their influence over the business are often asking for a worse tax outcome. Deferred purchase price also carries imputed interest, so part of what looks like sale proceeds is taxed as ordinary interest income. Both points belong in the conversation before the letter of intent, not after signing.
Frequently asked questions
What is a normal earnout size? The 2026 SRS Acquiom study puts the median earnout potential at 34% of the closing payment, up from 31% the prior year. That is the maximum written into the agreement, not the expected payment. Apply the 21% base rate to get an expected value.
How long should an earnout run? Market practice has shortened. Thirty-eight percent run one to two years, 23% run a year or less, and 20% run two to three years, with the median near 24 months. Longer periods give the buyer more time to integrate the business, which erodes the seller’s ability to prove what the standalone business would have produced.
Is revenue or EBITDA the better metric for a seller? Revenue, in most cases. EBITDA hands the buyer roughly eleven additional discretionary inputs, from overhead allocation to integration charges to accounting policy conformance. If the buyer insists on EBITDA, insist on a defined add-back schedule and a worked calculation attached as an exhibit.
Can the buyer deliberately miss the target? Delaware will not let a buyer act with the intent of avoiding an earnout payment, and the Krafton court ordered specific performance against a buyer who tried. Proving intent without an express covenant is hard and expensive. The Zimmer Biomet dismissal shows what happens when the agreement names no standard for measuring the buyer’s conduct.
What happens if the buyer sells the business during the earnout period? Whatever the agreement says. Without an acceleration clause, the seller’s claim follows the business into the hands of a third party who never negotiated with them and has no relationship to protect.
Should I take an earnout or seller financing? They are different risks. A seller note is a debt claim with a fixed schedule and, where the parties document it properly, a security interest. An earnout is an unsecured contingent claim on a number the buyer controls. Buyers offering an earnout in place of a note are proposing that you swap a credit risk for a control risk. See our explainer on seller financing in a business acquisition for how the note side prices out.
Do earnouts work in a search fund or self-funded acquisition? Rarely on the seller’s side, because the buyer is the operator and the seller has walked away. How search funds work covers the capital structure these buyers assemble instead.
The Business Model Analyst Take
Earnouts survive because they solve the buyer’s problem twice. They cap the price on a business the buyer is unsure about, and they hand the buyer control of the variable that decides whether the capped portion ever gets paid. A structure that valuable to one side does not persist for 40 years because it is fair.
None of that makes an earnout the wrong deal. Two out of five pay nothing, but three out of five pay something, and sellers of businesses that fit no clean comparable often have no better instrument available. The error is not accepting an earnout. The error is pricing it at face value and then spending the negotiation on the wrong clauses.
Treat the earnout section as a derivatives contract and negotiate it in that order. Define the underlying with a worked example. Constrain the writer with a named operating standard and an anti-frustration clause. Buy visibility into the number while it is still being produced. Route calculation fights to an accountant and conduct fights to a judge. Then discount whatever remains, because the counterparty runs the business the number comes from, and in three deals out of five in 2026 that turned out to matter more than the size of the promise.