Pizza is cooling across America, yet the category leader keeps eating everyone else’s slice.
Domino’s looks like a winner hiding inside a losing category. Even with U.S. pizza sales stagnant and its stock down nearly 40% in a year, the chain keeps taking share thanks to a vertically integrated supply chain and an asset-light, franchisee-funded model that pumped out $672 million in free cash flow last year, roughly triple a decade ago.
Picture the delivery app on your phone tonight. A local slice shop, a taco spot, a wings joint, and Domino’s all sit in the same scroll, fighting for the same hungry thumb. The red-roofed era where a national pizza brand owned your Friday night is over. And yet, somehow, the biggest player in pizza is the one quietly winning the fight.
What Happened
This week Domino’s said Chief Operating Officer Joe Jordan will replace Chief Executive Russell Weiner. Investors did not love the surprise timing and are treating the swap as a flashing red light, worried Jordan will quietly bin the company’s long-term growth targets.
The nerves are not coming out of nowhere. The stock already dropped in April after first-quarter U.S. same-store sales grew just 0.9%, and management walked away from its prior 3% growth target for 2026. Second-quarter results land next month, and nobody is expecting fireworks.
The Backstory
Pizza chains used to own a reliable American ritual: dinner under a Pizza Hut roof, or a predictable Domino’s box on a lazy TV night. That dependable appetite made Domino’s one of the best restaurant stocks to own for decades.
Then DoorDash and Uber Eats blew up the delivery moat. Suddenly every corner pizzeria had the same superpower national brands spent years building. Technomic data shows pizza’s share of U.S. restaurant spending has slipped as diners drift toward chicken and Mexican. Investors are now waving the white flag across the board: Yum Brands sold Pizza Hut this month for $2.7 billion, and Papa John’s has floated a sale of its own.
The Core Development
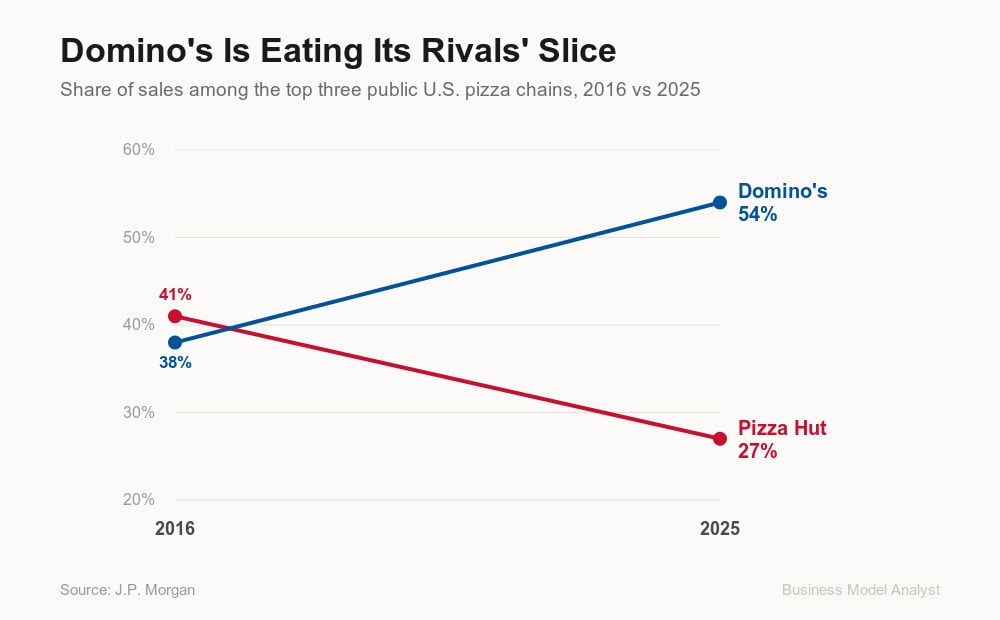
Look past the gloom and Domino’s is still grabbing a bigger piece of a shrinking pie. Its share of sales among the top three public pizza chains climbed to 54% in 2025 from 38% in 2016, according to J.P. Morgan. Pizza Hut went the other way, sliding from 41% to 27%.
The engine underneath is franchisee economics. A typical Domino’s restaurant throws off about $166,000 in per-unit EBITDA versus roughly $55,000 for Pizza Hut, per Evercore ISI. Domino’s is bigger, its supply chain keeps ingredient costs down, and its ad budget tops its two largest rivals combined. The chain is betting it can simply outlast competitors that are discounting their way into store closures.
The Business Model Angle
Here is the lesson worth stealing. Domino’s is a textbook asset-light franchise machine. Franchisees fund the new stores, so corporate capital needs stay low, which frees up mountains of cash. That cash funded a dividend raised every year plus steady buybacks. The quiet magic: even if same-store sales stay stuck in low gear, shrinking the share count means earnings per share can still grow at a mid-single-digit clip.
Translation for operators: a great business model is one that keeps minting money when growth disappears. Volume is nice. Structural cash generation is what protects you when the market turns cold.
The Risk
Do not paint over the tension. Domino’s is lapping the moves that juiced 2025, namely stuffed crusts (arriving decades after Pizza Hut) and finally landing on DoorDash, and RBC’s Logan Reich notes there are no easy levers left to pull. Net store growth could slow well below the 175 new U.S. locations the company targeted this year. As rivals lean harder into value deals, Domino’s faces a nasty choice: match the discounts and dent margins, or hold the line and risk handing back market share. A cash machine still has to keep the lights on.
Quick Questions
Why did Domino’s stock drop so much?
A mix of slowing U.S. same-store sales (just 0.9% in Q1), a dropped 3% growth target, and a surprise CEO change spooked investors into a near-40% slide over the past year.
Is the whole pizza category in trouble?
Pretty much. Pizza’s share of U.S. restaurant spending is slipping, Pizza Hut just sold for $2.7 billion, and Papa John’s is exploring a sale. Diners are wandering toward chicken and Mexican.
How is Domino’s still gaining if pizza is shrinking?
It is taking share from weaker rivals. Domino’s now holds 54% of sales among the top three public chains, up from 38% in 2016, while Pizza Hut collapsed to 27%.
Why do investors still care about a slow-growth chain?
The franchise model spins off serious cash ($672 million in free cash flow last year), funding buybacks that grow earnings per share even when sales barely move. The stock trades near 14 times forward earnings versus around 20 for peers like McDonald’s.
The Bottom Line
Growth gets the headlines, but cash flow wins the long game. Domino’s may never be the high-flying darling it once was, and that might be fine. A business engineered to compound earnings while the category shrinks around it is rarer, and frankly more durable, than another hot growth story. For founders: build the machine that pays you in the cold months, not just the warm ones.
Original reporting: The Wall Street Journal.