
The Domino lands August 31 at $7.99. Royalty, ad fund and the per-order tech fee eat 16.3% of that ticket, against 13.0% on a $25 order.
Domino’s is launching a rectangular, single-serve pizza built to pull people away from burgers and chicken sandwiches. The strategic logic is real: solo eating keeps rising and pizza has always been priced as a group purchase. But the fee architecture underneath means a small ticket is worth proportionally more to the franchisor than to the operator making it, and that gap is the actual story.
Every franchise system has a seam where the franchisor’s incentives and the operator’s incentives stop pointing the same direction. In pizza, that seam is the difference between an order and a dollar. Domino’s just built a product that adds a lot of the first and not much of the second.
What Happened
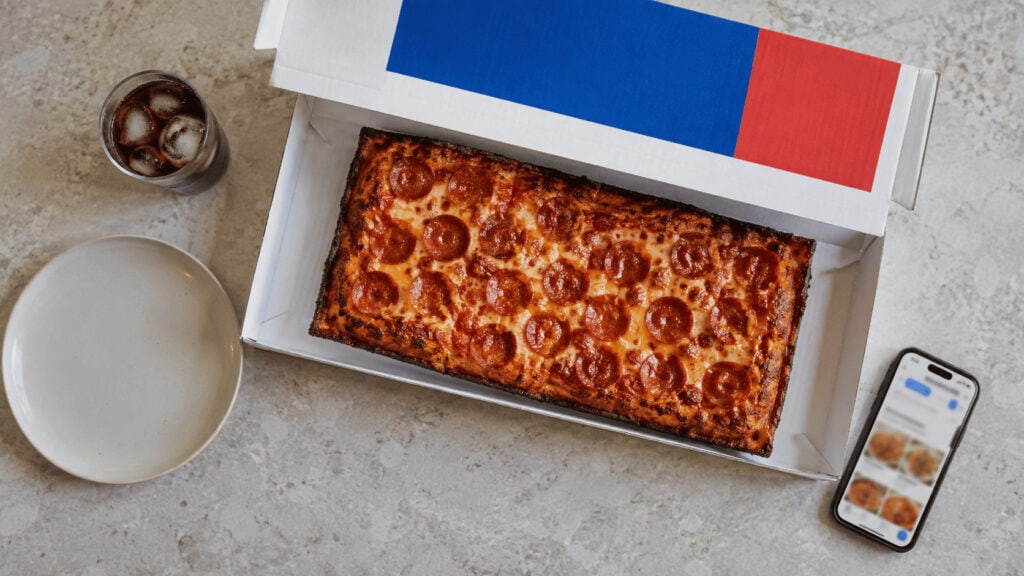
Domino’s confirmed it will release the Domino, an individual-size rectangular pie, on August 31. It resembles Detroit-style pizza, carries a savory Parmesan crust, packs more toppings than the small pizza already on the menu, ships in its own box, and required franchisees to buy dedicated pans to make it. A one-topping version runs about $7.99, or $6.99 each inside the mix-and-match menu. Incoming chief executive Joe Jordan, who takes over October 1, championed it after roughly two years of consumer research, and he is not pitching it as steering-wheel food.
The timing is not subtle. Domino’s posted US same-store sales of 0.1% in the quarter ended June 14, its softest comparable in more than a year, with international down 0.1%. Revenue rose 4.3% to $1.19 billion and net income rose 3.6% to $135.8 million, but diluted EPS of $4.07 missed the $4.17 consensus. Management told investors a new menu item would help in the back half.
The Backstory
The pizza category is shrinking around its leader. Papa John’s and Pizza Hut are closing hundreds of US locations, and Yum Brands sold Pizza Hut for $2.7 billion earlier this summer. Domino’s keeps taking share anyway, which is why the cash machine held up even as the stock fell.
The company has also been explicit about which metric it is playing for. Chief executive Russell Weiner told analysts that Domino’s grew orders meaningfully across delivery and carryout in the quarter, that the shortfall was on ticket, and that the ticket miss came from the premium series and Slice Sauce landing badly. “Order counts drive long-term success,” he said. Domino’s is now the largest pizza brand on both DoorDash and Uber Eats, and it says it prices those channels to be profit-neutral for franchisees.
Read that alongside the numbers and the picture is clean: orders up, ticket down, comps flat. The Domino is designed to push all three of those in exactly the same direction, harder.
The Plan
Jordan’s thesis is occasion capture. Pizza loses whenever a meal is one person deciding for themselves, because sharing forces compromise on toppings and crust. Circana data puts 43% of US restaurant meals eaten solo in the twelve months to June. If Domino’s can convert even a sliver of the individual fast-food occasion, the order count grows without needing the category to grow.
The company’s own P&L explains why order count is the metric it wants. US franchisees pay a 5.5% royalty on sales, contribute 6% of sales to the national ad fund, and pay a per-transaction technology fee on digital orders, which management raised by a penny in February to fund its platform. Two of those three scale with the ticket. The third does not.
The Business Model Angle
Here is what nobody else has run. Because the technology fee is fixed per order, corporate’s effective take rate rises as the ticket falls.
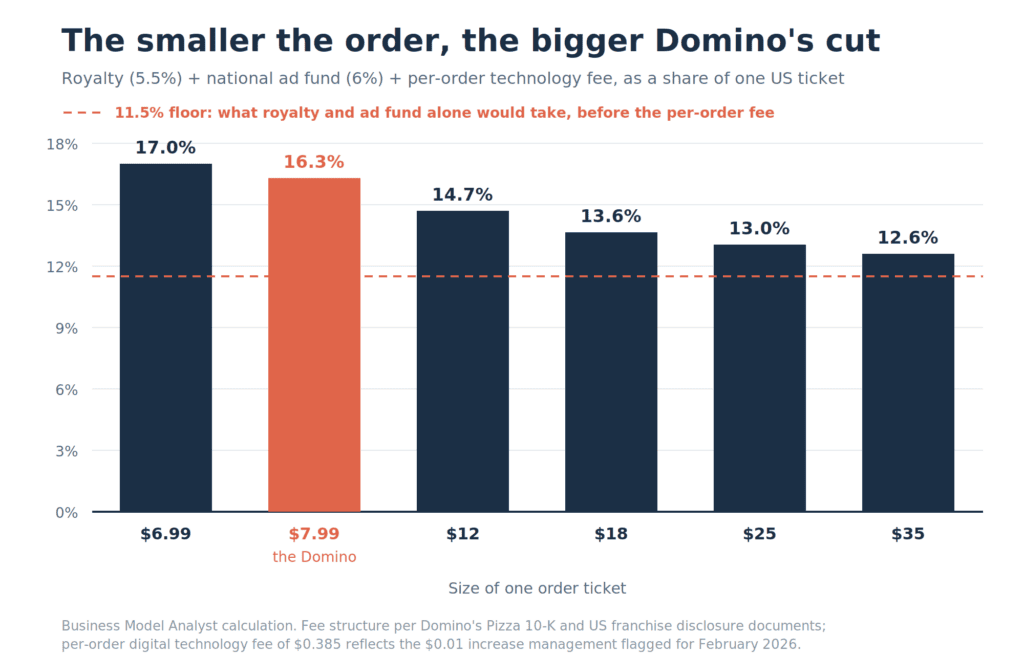
On a $35 family order, the stack takes 12.6%. On the $7.99 Domino, it takes 16.3%. At the $6.99 mix-and-match price, 17.0%. The headline 11.5% is a floor the system only approaches on large tickets.
The second-quarter numbers already show this engine running. Back out US franchise retail sales from the ad fund contribution and franchisees rang up roughly $2.25 billion, up 2.0% year over year. Domino’s US royalties and fees rose 5.1%. That lifted the effective take on every franchise sales dollar from 7.09% to 7.30%, a 21 basis point gain in a quarter with no comp growth. Strip out a full 5.5% royalty and the remaining fee line came to about $40.5 million against $35.1 million, up 15.5%, roughly 7.6 times the growth rate of the sales it sits on. That is a conservative read, because royalty incentives mean the true royalty rate is below 5.5% and the fee residual is therefore larger.
Now look at the other side of the same system. Domino’s own stores, the ones where it carries the operator P&L, ran an 11.8% store margin in the first half against 15.8% a year earlier, a 400 basis point collapse. In the second quarter alone it was 11.4% versus 15.6%. Domino’s also sold 77 company stores in Virginia and Michigan during the quarter, booking a $4.1 million refranchising gain. Meanwhile the supply chain segment, which sells franchisees the dough, the cheese and the pans, grew revenue 6.5% on a food basket up only 2.2% and grew segment profit 18.1%, lifting its margin from 9.4% to 10.4%.
The operator layer lost 400 basis points. The fee layer gained 21. The food-selling layer gained 103. That is the same trade McDonald’s runs between its landlord and operator books and the same one RBI runs across Burger King and its own restaurants, expressed through a different instrument. If you want the general shape, it is the franchise business model doing what it is built to do.
The Risk
The Domino only works if it is genuinely incremental. Every order that trades down from a family purchase to a single pie is a comp event in reverse. At a $20 displaced ticket, Domino’s needs roughly three incremental Domino orders for every two that cannibalize just to stay flat on system sales. At $25, it needs a little over two for one. Order count grows either way. Sales do not.
The operator absorbs the rest. The pan is capital the franchisee bought, and the cost has not been disclosed, though the precedent is not comforting: Burger King’s Whopper upgrade runs franchisees about $4,000 per store per year. A pan pizza also takes oven belt space during the exact hours when throughput is the constraint, and the make, box and drop cost of a $7.99 order is not much cheaper than a $22 one. On an aggregator, where the platform’s cut is layered on top, the math gets tighter still.
And Domino’s has just told the market it missed on ticket. Its answer is a product engineered to lower ticket further, sold on the promise that volume will more than cover it. Weiner’s read was that the miss was within the company’s control. This launch is the test of whether that was diagnosis or comfort.
Quick Questions
What is the Domino?
A rectangular, individual-size pizza with a savory Parmesan crust and heavier toppings than the current small, launching August 31 at roughly $7.99 for one topping or $6.99 each on mix-and-match. It requires special pans franchisees had to purchase.
Why is Domino’s doing this now?
US same-store sales came in at 0.1% in the June quarter, the weakest in over a year, with orders growing and ticket falling. Management promised investors a new menu item would lift the back half.
Who benefits most from a cheaper individual pizza?
The franchisor. Royalty and ad fund scale with the ticket, but the per-order technology fee does not, so the combined take rises from about 12.6% on a $35 order to 16.3% on the $7.99 Domino. Supply chain also sells more units.
What is the biggest risk to the launch?
Cannibalization. Domino’s needs the Domino to pull orders from burgers and chicken rather than from its own large pizzas, because a trade-down from a $20 order to a $7.99 one destroys system sales even while order count goes up.
The Business Model Analyst Take
Most operators design pricing around gross margin and ignore what their fee stack does to unit economics at different ticket sizes. Domino’s has a fixed per-order component sitting on top of two variable ones, which means the shape of its revenue changes with the shape of a basket. That is a design choice, and it is currently pointed at a strategy of more, smaller orders.
The lesson generalizes past pizza. If you charge partners a mix of percentage fees and flat per-transaction fees, you have quietly built a system that rewards you most on your smallest transactions and rewards them least. That works beautifully as long as the small transactions are additive. It becomes an argument the moment they are not. Know which one you are running, and check the number before your partners do.
Original reporting: The Wall Street Journal. Financial data from Domino’s Pizza, Inc. Form 10-Q for the quarter ended June 14, 2026 and company disclosures.