
What is a value chain analysis? A method from Michael Porter’s 1985 book Competitive Advantage that breaks a company into the activities it performs to create a product, then asks where margin is actually captured. Porter splits activities into five primary ones (inbound logistics, operations, outbound logistics, marketing and sales, service) and four support ones (firm infrastructure, human resource management, technology development, procurement).
What is Disney’s value chain? Disney creates characters and stories in its Entertainment segment, then sells access to them through streaming, television, theaters, theme parks, hotels, cruise ships and licensed merchandise. Every node in the chain runs on the same input: intellectual property that Disney owns.
The key takeaway: Disney charges outsiders for that input and charges itself almost nothing for it. An independent licensee pays a royalty to put Mickey on a lunchbox. Oriental Land Company pays a royalty on the revenues of Tokyo Disney Resort. Walt Disney World pays nothing at all. Because the input crosses most of the chain unpriced, Disney’s published segment margins measure where the IP happens to be billed rather than how well each node is run. On August 5, 2026, Disney announced it will move most of Consumer Products from Experiences into Entertainment, which on fiscal 2025 figures shifts $2.18 billion of operating income between segments without changing a single operation.
Almost every published Disney value chain analysis says a version of the same thing. Disney is vertically integrated. Disney has a flywheel. A film feeds a ride, the ride feeds merchandise, merchandise feeds the brand, the brand feeds the next film. It is true, it has been true since Walt Disney sketched the diagram himself in 1957, and it explains nothing about why one part of this company reports a 49 percent operating margin and another part reports 11 percent.
The more useful question is not how value moves through Disney’s chain. It is what each node pays for the thing it uses.
Every business has inputs it buys. Steel, flour, server capacity, shipping containers. The price of the input is the discipline: it tells the buyer whether the activity is worth doing, and it tells the seller whether the input is worth making. Disney’s chain runs on a single input, the character, and for most of the chain that input has no price at all. The parks do not buy Star Wars from the studio. They just use it.
That absence is not a rounding error in the analysis. It is the analysis.
Disney at a glance, fiscal 2025
Disney’s fiscal year ended September 27, 2025. Three reportable segments, one of which is about to change shape.
| Segment | Revenue | Operating income | Margin | Share of segment profit |
|---|---|---|---|---|
| Entertainment | $42,466M | $4,674M | 11.0% | 26.6% |
| Sports | $17,672M | $2,882M | 16.3% | 16.4% |
| Experiences | $36,156M | $9,995M | 27.6% | 56.9% |
| Eliminations | $(1,869)M | |||
| Total | $94,425M | $17,551M |
Source: Disney fiscal 2025 fourth quarter results, filed November 13, 2025.
Read that table the way most coverage reads it and you get the standard 2026 Disney story: the parks carry the company, streaming is finally respectable, sports is stuck. Read it as a value chain and something is off. The segment that writes, animates, films and owns every character in the building is the one with the thinnest margin in the company.
How the chain is actually built
Porter’s nine boxes map onto Disney awkwardly, because Disney’s raw material is manufactured in house rather than purchased. Here is the honest version.
| Porter activity | What Disney actually does | Which segment owns it |
|---|---|---|
| Inbound logistics | Creating and acquiring IP. Disney Animation, Pixar, Marvel Studios, Lucasfilm, 20th Century, plus sports rights bought from leagues | Entertainment (and Sports for rights) |
| Operations | Film and series production, live sports production, and Walt Disney Imagineering, which converts stories into physical attractions | Entertainment, Sports, Experiences |
| Outbound logistics | Theatrical distribution, Disney+, Hulu, ESPN DTC, ABC and the cable networks, home entertainment | Entertainment, Sports |
| Marketing and sales | Cross-promotion across every surface Disney owns, from trailers in the parks to park advertising inside the streaming apps | All three |
| Service | Cast members, hotels, Disney Cruise Line, Disney Vacation Club, guest recovery | Experiences |
| Firm infrastructure | Corporate, capital allocation, and the segment reporting structure itself | Corporate |
| Human resources | Creative talent contracts at one end, roughly 175,000 employees including a large hourly cast at the other | All three |
| Technology development | Imagineering ride systems, streaming platform engineering, production technology | All three |
| Procurement | Sports rights, third-party content, construction, cruise ships, retail goods. Not characters, which are never bought | All three |
That last row is the one worth sitting with. Disney procures everything a media and leisure company procures except the one input that makes it Disney.
The single most revealing fact in Disney’s 10-K
Disney does put a price on its IP. It does it constantly, and it is very good at it.
License Global’s most recent Top Global Licensors ranking puts roughly $63 billion of licensed Disney product through retail, the largest figure in the industry and close to a fifth of the entire $307.9 billion market the study tracks. Disney’s 10-K explains the mechanics plainly: it licenses characters from its film and television properties for use on third-party products and earns royalties, usually a fixed percentage of the wholesale or retail selling price, often with minimum guarantees attached.
Set that against the Consumer Products revenue Disney actually books and you get an implied capture rate of about 7 percent of retail value. Roughly seven cents of every dollar spent on a licensed Disney product comes back to Disney as revenue. That is the market price of a character, established across more than 100 product categories in more than 180 countries.
Now apply it internally.
Disney’s fiscal 2025 eliminations line is $1,869 million, and the company’s own footnote defines exactly what it is: fees Hulu pays ESPN and the Entertainment linear networks for the right to air them, plus fees ABC Network and Disney+ pay ESPN to carry sports content. Disney puts a quantified internal price on a television signal moving from one of its businesses to another, and that price has grown 17 percent year over year.
For characters, the 10-K describes one intersegment allocation and only one. Entertainment revenue includes a transfer from Experiences meant to reflect royalties on consumer products merchandise licensing revenue generated on IP the Entertainment segment created. That is the entire scope. It reaches merchandise. It does not reach a theme park ticket, a hotel room, a cruise fare, or a churro.
So a licensee who prints Elsa on a backpack triggers a payment back to the studio that made Frozen. A Disney park that builds an entire Frozen-themed land, prices admission around it, sells the hotel stay next to it and books the resulting revenue in a different segment triggers nothing.
Tokyo is the control experiment
If this sounds like an accounting curiosity rather than a real economic distinction, Disney runs the experiment for us.
Disney does not own Tokyo Disney Resort. A third party, Oriental Land Company, owns and operates it. Disney’s own annual report states that it licenses its IP to that third party and is entitled to royalties based on the resort’s revenues.
Same castle. Same characters. Same rides, in several cases the same ride systems designed by the same Imagineers. When somebody else owns the park, the characters have a price and it is charged on revenue. When Disney owns the park, they do not.
That is the whole argument in one comparison, and it is drawn entirely from Disney’s own filings.
What the unpriced input does to the numbers
Once you know one input crosses most of the chain for free, the segment margins stop reading as performance and start reading as geography.
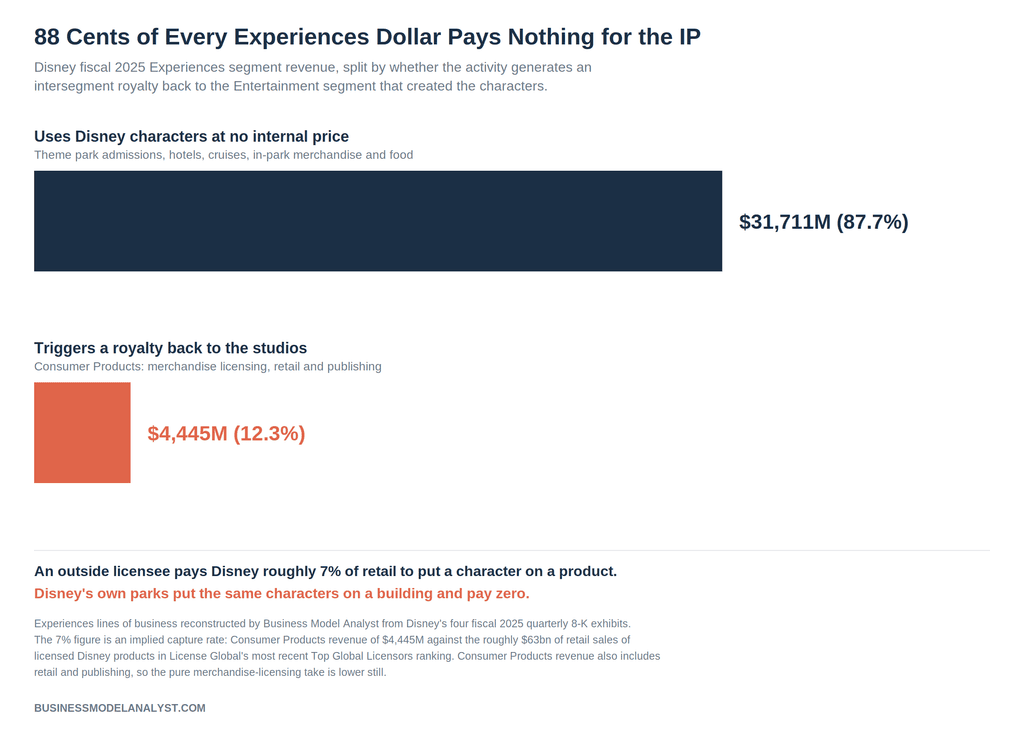
Consumer Products, the one node in Experiences that charges for the IP, ran a 49.0 percent operating margin in fiscal 2025. Domestic Parks and Experiences ran 25.3 percent. International ran 22.1 percent. Sports ran 16.3 percent. Entertainment, the node that creates every character the other four sell, ran 11.0 percent.
Those Consumer Products and Parks figures are not published as annual lines. Disney discloses the Experiences split by line of business quarterly and never sums it in the annual release, so we rebuilt the full year from the four fiscal 2025 quarterly 8-K exhibits. The reconstruction lands exactly on Disney’s reported segment totals of $36,156 million of revenue and $9,995 million of operating income, which is the check that matters.
Consumer Products, full fiscal year: $4,445 million of revenue and $2,178 million of operating income.
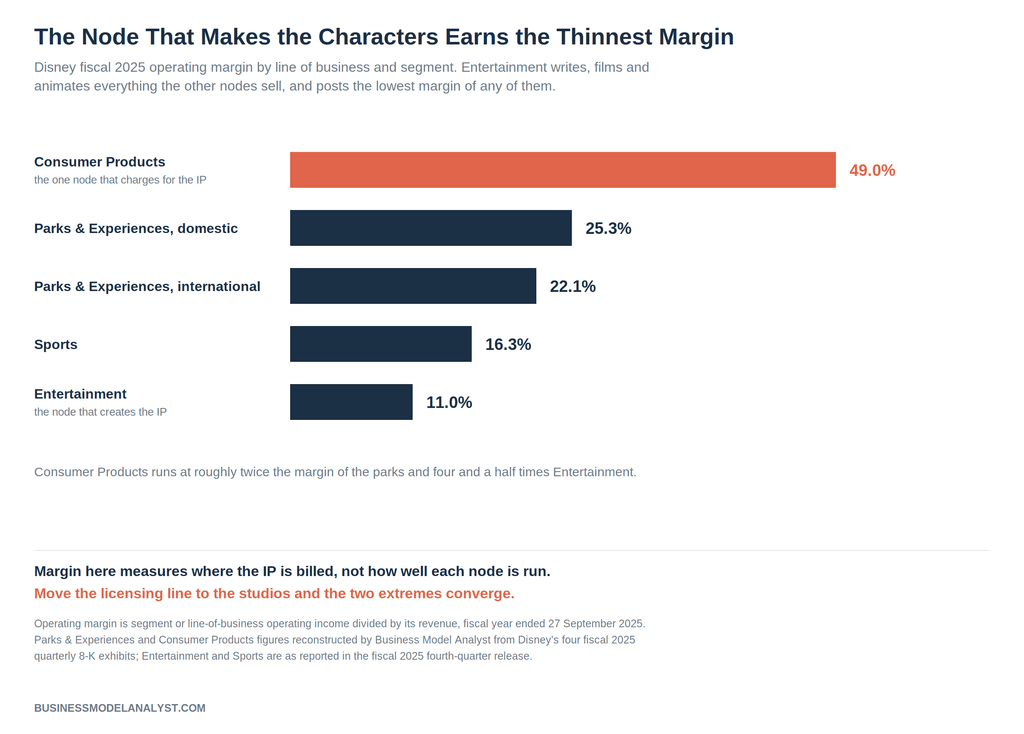
That $4,445 million is 12.3 percent of Experiences revenue. The other 87.7 percent, $31,711 million of admissions, hotel nights, cruise fares, in-park merchandise and food, is generated by activities that use Disney characters and generate no disclosed internal charge for them.
Eighty-eight cents of every Experiences dollar runs on an input the segment gets for nothing.
Disney just conceded the point
On August 5, 2026, alongside third quarter results, chief executive Josh D’Amaro told shareholders that beginning in the first quarter of fiscal 2027, which starts in October 2026, Disney will move most of its Consumer Products business from Experiences into Entertainment. The stated reasoning is worth quoting exactly, because it is unusually direct.
The shift, D’Amaro wrote, brings the monetization of Disney’s IP through consumer products closer to the studios that create that IP. And then the second sentence: Disney believes the presentation will better reflect the returns the Entertainment segment is generating from the content it produces, and make Entertainment more comparable to peer reporting.
Read that as a value chain statement. Disney is saying that the returns Entertainment generates were not previously being reflected where they were generated. That is a transfer pricing problem described in plain English by the company that has it.
Thomas Mazloum, chairman of Disney Experiences, and Alan Bergman, chairman of Disney Entertainment Studios, sent a joint memo framing it as an operating alignment rather than a reporting change. Both things are true. Putting merchandising in the same room as the studios is a real coordination decision. It is also the largest single revision to how Disney’s chain is scored since Consumer Products stopped being its own segment.
Here is what it does to fiscal 2025 if you apply it retroactively.

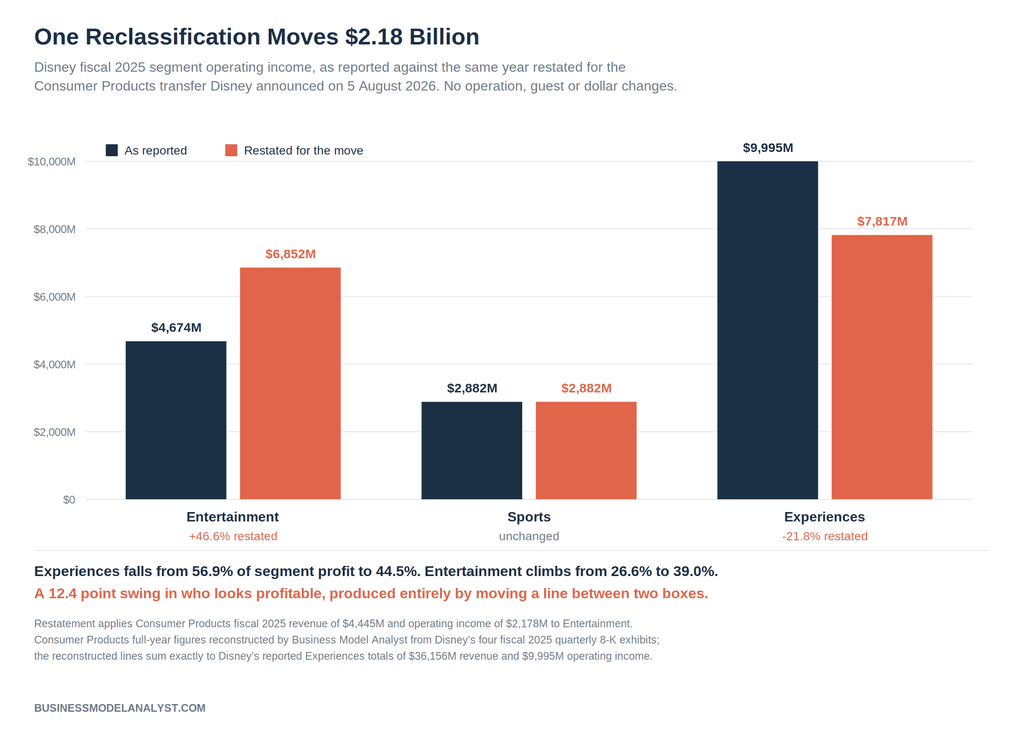
Entertainment operating income goes from $4,674 million to $6,852 million, a 46.6 percent increase. Experiences falls from $9,995 million to $7,817 million, down 21.8 percent. Entertainment’s share of total segment profit rises from 26.6 percent to 39.0 percent. Experiences drops from 56.9 percent to 44.5 percent.
Twelve and a half points of profit share move between two segments. Not one guest, film, ride, ship or dollar of cash changes. Entertainment’s margin goes from 11.0 percent to 14.6 percent; Experiences goes from 27.6 percent to 24.7 percent, and the gap between the company’s fattest and thinnest nodes narrows sharply.
Every “the parks are carrying Disney” analysis written between 2024 and 2026 was measuring a boundary, not a business.
Where the capital goes, and why it compounds the distortion
The reclassification only affects merchandise. The larger flow, the physical chain, stays exactly where it is.
In fiscal 2025 Disney spent $8,024 million on parks, resorts and other property. Experiences took $6,429 million of it, 80.1 percent. Entertainment took $1,155 million. For every dollar of capital that went to the segment that makes the IP, $5.57 went to the segment that uses it for free. Meanwhile the cost of manufacturing that input, roughly $24 billion of annual content investment across Entertainment and Sports, sits inside operating expenses at the segments that create it.
So the node that produces the raw material carries the full cost of producing it and collects a royalty on one narrow category of use. The node that consumes the most of it pays nothing for it and receives four fifths of the capital budget. Both effects push in the same direction, and both are invisible if you read the chain as a flywheel.
Disney’s capital allocation asymmetries run deeper than this, and we have covered the sharpest example separately in ESPN’s harvest economics, where a segment earning $2.9 billion received $3 million of capital expenditure in the same year.
Information gain: what this analysis has that the others do not
Most Disney value chain pages online are still working from the segment structure Disney retired in 2023, describing Media Networks and Parks and Resorts as though they exist. Several of the top-ranked results cite no financial figure newer than 2016.
| Data point | Value | Available elsewhere? |
|---|---|---|
| Consumer Products fiscal 2025 revenue and operating income | $4,445M / $2,178M, reconstructed from four 8-K exhibits | No, Disney publishes no annual line |
| Consumer Products operating margin | 49.0% | No |
| Effect of the announced transfer on fiscal 2025 segment profit | Entertainment +46.6%, Experiences -21.8% | No |
| Profit share shift | Experiences 56.9% to 44.5%, a 12.4 point swing | No |
| Share of Experiences revenue with no internal IP charge | 87.7% ($31,711M of $36,156M) | No |
| Implied external royalty capture | About 7% of the roughly $63bn licensed retail base | No |
| Disney’s only quantified intersegment price | $1,869M, entirely carriage and programming fees | Rarely, and never read as a transfer pricing fact |
| Tokyo Disney Resort as the priced counterexample | Third-party owned, royalty on resort revenues per the 10-K | Occasionally mentioned, never used this way |
| Capex asymmetry | Experiences $6,429M against Entertainment $1,155M, 5.57x | Partially |
| Date and wording of the Consumer Products move | August 5, 2026 shareholder letter, effective Q1 fiscal 2027 | Yes, but not connected to the chain |
The case against this reading
Three objections deserve real weight.
Segment reporting is not cost accounting. Under ASC 280, a company reports the way its chief operating decision maker actually manages the business. The absence of a disclosed park royalty proves the absence of a disclosed one, not the absence of any internal charge. Disney certainly maintains transfer pricing between legal entities for tax purposes, and that machinery is separate from segment presentation and largely invisible from outside. The honest claim is about what Disney tells investors, not about what its internal management accounts contain.
A zero internal royalty may be the right answer. If the films exist partly because the parks will monetize them, and the parks fill partly because the films exist, then any arm’s-length royalty between the two is arbitrary. You would be inventing a number to move it from one pocket to another. Plenty of well-run conglomerates decline to charge internally for shared brand assets for exactly this reason. The critique here is not that Disney should charge itself. It is that analysts should stop treating the resulting margins as clean measures of node performance.
Entertainment’s margin is thin for real reasons too. Linear networks are in structural decline, with revenue down 12 percent in fiscal 2025. Theatrical results swing violently on a single slate. Streaming only recently crossed into meaningful profit, with direct-to-consumer operating income going from $143 million to $1,327 million in one year. Even after restating for the Consumer Products move, Entertainment sits at 14.6 percent, which is still below Experiences. The unpriced input explains part of the gap, not all of it.
None of that rescues the standard analysis. If a single reclassification announced in a shareholder letter can move a fifth of a segment’s profit, the diagram was never measuring what people thought it was measuring.
Frequently asked questions
What is Disney’s value chain in simple terms? Disney creates characters and stories, then sells access to them through as many surfaces as it can own: streaming, broadcast, theaters, theme parks, hotels, cruise ships, and licensed merchandise. The distinguishing feature is not the number of surfaces. It is that Disney owns the input and reuses it across all of them without buying it from anyone.
Which part of Disney’s value chain is most profitable? On fiscal 2025 figures, Consumer Products, at a 49.0 percent operating margin. That is also the only node that charges other parts of the company for the IP it uses, which is not a coincidence.
Does Disney charge its own theme parks for using its characters? Not in any form Disney discloses. The one intersegment IP royalty described in the 10-K is scoped to consumer products merchandise licensing. Disney does charge third-party park operators. Oriental Land Company, which owns and operates Tokyo Disney Resort, pays Disney royalties based on the resort’s revenues.
Why is Disney moving Consumer Products to the Entertainment segment? Disney says it puts merchandise and licensing closer to the studios creating the underlying IP, and that it will better reflect the returns Entertainment generates from its content. The change takes effect in the first quarter of fiscal 2027, beginning October 2026.
What are Disney’s primary and support activities under Porter’s framework? Primary: IP creation and rights acquisition, production and Imagineering, distribution across theatrical, streaming and linear, cross-promotional marketing, and guest service at the parks, hotels and cruise line. Support: corporate and capital allocation, human resources spanning creative talent and a large hourly cast, technology development in ride systems and streaming, and procurement of everything except characters.
What is Disney’s real competitive advantage in the value chain? Not integration on its own, which competitors have copied. It is that Disney’s input appreciates with use. A character gets more valuable each time it appears somewhere new, which inverts the normal relationship between consuming an input and depleting it. That property is what makes the missing internal price tolerable, and it is also what makes it so hard to see.
The Business Model Analyst Take
Porter’s diagram assumes you can score each node by the value it adds. That works when the inputs have prices, because the price is what separates value added from value passed through. Disney breaks the assumption. Its central input moves through most of the chain uncosted, which means the reported margin of every node is partly an artifact of where the accountants drew the line.
The tell is that Disney keeps redrawing it. Consumer Products has been its own segment, then part of Consumer Products and Interactive Media, then part of Parks Experiences and Products, then part of Experiences, and from October 2026 part of Entertainment. Five homes in roughly a decade, and each move rewrote which part of Disney looked like the engine. The business did not change. The box did.
There is a general lesson here for anyone running a value chain analysis on a company built around reusable IP, which increasingly means most software, media, and consumer brand companies. Before you compare margins across nodes, find out what the nodes charge each other. If the answer is nothing, you are not looking at a performance ranking. You are looking at a filing convention, and the company can change it any quarter it likes.
Disney is about to change it in October. Watch how quickly the story about which part of the company is winning changes with it.