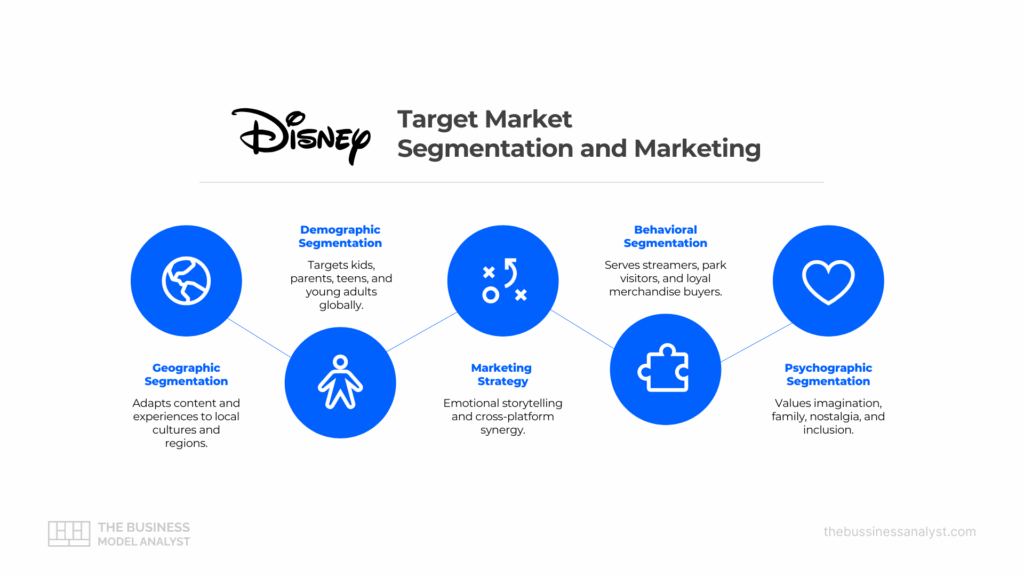

What Is the Disney Target Market? The Disney target market is built around four core segments: families with children aged 3 to 12, parents aged 25 to 45 who control household spending, young adults aged 18 to 34 reached through Marvel, Star Wars, and streaming, and nostalgic adults without children, one of Disney’s fastest-growing cohorts. Disney monetizes these groups across theme parks (a record $10.0 billion in quarterly revenue in Q1 fiscal 2026), streaming (196 million Disney+ and Hulu subscriptions at the last public count in September 2025), films, and licensed merchandise, with North America as its anchor market and Asia-Pacific and the Middle East as its main growth bets.
Few companies serve a customer base as wide as The Walt Disney Company. A four-year-old watching Bluey on Disney+, a 38-year-old planning a Walt Disney World trip, and a childless 29-year-old buying Loungefly bags all sit inside the same target market, just in different segments. That breadth is deliberate. Disney’s segmentation strategy is designed to capture a customer in early childhood and keep monetizing that relationship across every life stage.
This analysis breaks down who Disney targets, how the company segments its audience demographically, geographically, psychographically, and behaviorally, how each segment maps to actual revenue, and where the strategy shows cracks heading deeper into 2026.
Disney Target Market at a Glance
| Segment | Age range | Role in the market | Primary touchpoints |
|---|---|---|---|
| Children | 3 to 12 | Demand creators, brand entry point | Animated films, Disney Jr., merchandise, parks |
| Parents | 25 to 45 | Purchase decision-makers, nostalgic co-consumers | Parks, Disney+ subscriptions, cruises, merchandise |
| Teens and young adults | 13 to 34 | Franchise fans, streaming-first viewers | Marvel, Star Wars, Hulu, ESPN, social content |
| Adults without children | 18 to 45+ | High-margin discretionary spenders (“Disney adults”) | Parks, collectibles, Disney+ catalog, food and wine events |
| Multigenerational families | All ages | High-ticket group travelers | Walt Disney World, Disney Cruise Line |
Demographic Segmentation
Disney’s demographic core has not changed in decades: families with children aged 3 to 12. What has changed is how much of the company’s growth now comes from everyone else.
Children (3 to 12). Kids are rarely the buyers, but they are the demand engine. Animated franchises do the recruiting. Zootopia 2, released in late 2025, became the highest-grossing animated film of all time and pushed Disney’s Entertainment segment revenue up 7% in Q1 fiscal 2026, according to the company’s February 2026 earnings release. A hit film aimed at children feeds parks attendance, merchandise sales, and streaming sign-ups for years.
Parents (25 to 45). This is the segment that actually pays. Parents are targeted twice: as gatekeepers of household entertainment budgets and as nostalgic consumers of the same franchises they grew up with. Per-guest spending at domestic parks rose 4% year over year in Q1 fiscal 2026, a sign that Disney’s pricing power with this cohort remains intact even in a cautious consumer environment.
Teens and young adults (13 to 34). The Marvel, Star Wars, and 20th Century acquisitions exist largely to serve this group. Hulu (now folding into a unified Disney+ app experience during 2026) extends the company’s reach into general entertainment that the family-branded Disney+ catalog cannot credibly carry alone.
Adults without children. The so-called Disney adult is no longer a meme; it is a strategic segment. These consumers have high discretionary income, no childcare costs, and strong franchise attachment. Runway events like EPCOT’s food festivals, adult-oriented merchandise lines, and after-hours park events are built for them.
| Demographic lever | What Disney offers | Revenue logic |
|---|---|---|
| Income (middle to upper-middle) | Tiered park tickets, Lightning Lane upsells, deluxe resorts | Captures both value seekers and premium spenders |
| Income (price-sensitive) | Disney+ ad-supported tier, Disney+/Hulu bundles | Keeps lower-income households in the ecosystem |
| Gender | Princess lines, Marvel, ESPN, Star Wars | Franchise portfolio covers traditionally gendered preferences without excluding either |
| Life stage | Disney Jr. to Hulu to cruise retirees | One brand architecture per life stage |
Geographic Segmentation
Disney is global in distribution but heavily concentrated in revenue. In Q1 fiscal 2026, domestic parks generated $6.91 billion against $1.75 billion from international parks, per CNBC’s earnings coverage. Both grew 7%, but the gap shows how dependent the Experiences segment remains on North American visitors.
| Region | Anchor assets | Targeting approach |
|---|---|---|
| North America | Walt Disney World, Disneyland, ESPN, Hulu | Core market; premium pricing, loyalty programs, annual passes |
| Europe | Disneyland Paris, Disney+ | Localized content, park investment after record Paris growth in fiscal 2025 |
| Asia-Pacific | Tokyo, Shanghai, Hong Kong resorts | Localized attractions (Zootopia land in Shanghai), regional storytelling |
| Latin America | Disney+ | Streaming-first, football and local originals |
| Middle East and Africa | Disney Abu Dhabi (announced) | New flagship to capture a market with no Disney park |
The biggest geographic move in years came on May 7, 2025, when Disney and Miral announced the company’s seventh theme park resort on Yas Island, Abu Dhabi. The structure is telling for anyone studying Disney’s targeting: Miral finances, builds, and operates the resort while Disney collects royalties and leads creative design. Disney gets exposure to roughly 120 million annual airline passengers moving through Abu Dhabi and Dubai, plus proximity to families across the Middle East, India, and Africa, without deploying its own capital. It is geographic market expansion at near-zero balance sheet risk.
Attendance data confirms why parks anchor the geographic strategy. The 2024 TEA Global Experience Index ranked Magic Kingdom the world’s most visited theme park for the 19th consecutive year, with an estimated 17.84 million visitors, and placed Disney properties in 8 of the global top 10.
Psychographic Segmentation
Demographics explain who buys; psychographics explain why they keep buying. Disney targets three durable psychological profiles.
Nostalgia seekers. Adults who grew up with Disney content treat the brand as a link to their own childhood. This is why Disney remakes its animated classics in live action and why park attractions from the 1970s are preserved rather than replaced. Nostalgia converts a one-time childhood customer into a lifetime revenue stream, and eventually into a parent who restarts the cycle.
Experience collectors. A growing share of consumers, particularly millennials and Gen Z, prioritize spending on experiences over goods. Disney’s cruise expansion speaks directly to this profile: the Disney Treasure and Disney Destiny both entered service within the past two fiscal years, and cruise growth was a named driver of domestic Experiences results in fiscal 2025.
Values-driven families. Parents who filter entertainment for safety and age-appropriateness default to Disney brands. The trust premium here is real but fragile, and it is the psychographic battleground where content controversies cost the company most.
Behavioral Segmentation
| Behavior pattern | What it signals | How Disney monetizes it |
|---|---|---|
| Repeat park visitation | High loyalty, high lifetime value | Annual passes, deluxe resort upsells, Lightning Lane |
| Franchise bingeing on streaming | Strong fan identity | Merchandise drops timed to releases, park tie-ins |
| Price-sensitive streaming sign-ups | Churn risk | Ad-supported tier, Hulu bundling, price-hike laddering |
| Occasion-based purchases | Birthdays, holidays, first visits | Premium photo packages, celebration merchandise |
| Cord-cutting | Linear TV decline | Migration path to Disney+, Hulu, and ESPN’s direct-to-consumer service |
The behavioral story of 2025 and 2026 is monetization over volume. Disney stopped reporting Disney+ and Hulu subscriber counts entirely as of its Q1 fiscal 2026 report in February 2026, following Netflix’s lead and stating the metric had become less meaningful. The final public figures, from September 27, 2025, stood at 196 million combined Disney+ and Hulu subscriptions, including 132 million Disney+ subscribers. The shift tells you where targeting effort now goes: not acquiring marginal subscribers, but extracting more revenue per existing one. It worked in the short term. Streaming revenue rose 11% to $5.35 billion in Q1 fiscal 2026, and combined Disney+ and Hulu profit jumped 72% year over year to $450 million.
How Each Segment Maps to Revenue
This is the table most analyses skip. Disney’s fiscal 2026 first quarter (ended December 27, 2025) shows exactly which audience segments carry the business.
| Business segment | Q1 FY2026 result | Primary target segments served |
|---|---|---|
| Experiences (parks, cruises, products) | Record $10.0 billion revenue, $3.3 billion operating income | Families, parents, Disney adults, multigenerational travelers |
| Entertainment (film, streaming, networks) | Revenue up 7%; streaming revenue $5.35 billion, up 11% | Children, teens, young adults, cord-cutters |
| Sports (ESPN) | $191 million operating income | Adult males 18 to 49, sports households |
| Total company | $26.0 billion revenue, up 5% | All segments |
Two takeaways for strategists. First, the family-and-parks machine is still the profit engine: Experiences delivered roughly 70% of total segment operating income in the quarter. Second, streaming finally pays for itself. Direct-to-consumer operating income for full fiscal 2025 reached $1.33 billion, up from $143 million the year before, according to Disney’s 10-K filing. The decade-long bet on reaching streaming-first audiences has crossed from investment to return.
Disney vs. Competitors: Audience Targeting Compared
| Dimension | Disney | Universal (Comcast) | Netflix |
|---|---|---|---|
| Core audience | Families with kids 3 to 12, plus nostalgic adults | Teens and thrill-seeking young adults | Adults 18 to 49, genre-diverse |
| Children’s content depth | Deepest catalog in the industry | Limited (DreamWorks) | Broad but not brand-defining |
| Physical experiences | 6 resorts, 7th announced | Epic Universe opened 2025 in Orlando | None |
| Brand trust with parents | Highest in entertainment | Moderate | Neutral |
| Weakness | Premium pricing excludes lower-income families | Narrower demographic ceiling | No physical ecosystem |
Universal’s Epic Universe raised the stakes in Orlando, but the 2024 TEA index showed both legacy Universal Orlando parks losing attendance while all four Walt Disney World parks grew. Netflix competes for screen time rather than vacations; its algorithmic, adult-skewing model is examined in our Netflix target market analysis, and the contrast is instructive. Netflix targets individuals; Disney targets households.
How Disney Reaches Its Target Market
Disney’s segmentation only works because its marketing engine activates each group differently: character-led campaigns for children, nostalgia-driven creative for parents, franchise drops and social-first content for young adults, and destination marketing for travel planners. The full playbook, from localized content like Coco and Mulan to synchronized franchise launches across parks, retail, and streaming, is covered in our breakdown of the Walt Disney marketing strategy.
The structural advantage is the flywheel. A film creates characters, characters become park attractions, attractions sell merchandise, and merchandise keeps the franchise alive between releases. Each segment touchpoint reinforces the others, which is why the company’s customer segments are best understood alongside the broader Disney business model.
Strengths and Weaknesses of Disney’s Targeting
| Strengths | Weaknesses |
|---|---|
| Multigenerational reach: captures customers at age 3 and re-captures them as parents | Premium park pricing increasingly excludes middle-income families |
| Franchise portfolio spans gender and age preferences | Heavy dependence on North America (about 80% of parks revenue) |
| Physical-digital ecosystem competitors cannot replicate | Linear TV audience shrinking faster than streaming profits replace it |
| Pricing power: 4% guest spending growth despite soft international visitation | Brand trust exposes Disney to culture-war backlash from multiple directions |
| Royalty-based expansion (Abu Dhabi) adds reach without capital risk | Subscriber opacity since 2026 makes streaming health harder to verify externally |
A fuller treatment of these tensions sits in our Disney SWOT analysis, and the strategic frameworks behind the company’s expansion choices are mapped in Disney’s generic competitive and growth strategies.
What Changed in 2025 and 2026
| Date | Development | Targeting implication |
|---|---|---|
| May 2025 | Abu Dhabi resort announced with Miral | First dedicated play for Middle East, India, and Africa audiences |
| Sept 2025 | Final subscriber disclosure: 196M Disney+ and Hulu subscriptions | End of the growth-at-all-costs streaming era |
| Oct 2025 | Hulu + Live TV merged with Fubo; Disney holds 70% | Consolidates the cord-cutter segment under one roof |
| Nov 2025 | Zootopia 2 becomes highest-grossing animated film ever | Children’s segment remains the franchise factory |
| Feb 2026 | Record $10B Experiences quarter; subscriber reporting ends | Strategy pivots fully from audience volume to audience yield |
| 2026 (ongoing) | Disney+ and Hulu merge into a unified app | One front door for family and general-entertainment segments |
Frequently Asked Questions
Who is Disney’s primary target market? Families with children aged 3 to 12, with parents aged 25 to 45 as the purchasing decision-makers. Secondary segments include young adults 18 to 34 (via Marvel, Star Wars, and Hulu) and adults without children who engage through parks and nostalgia-driven content.
What age group does Disney target most? Children aged 3 to 12 drive demand, but parents aged 25 to 45 generate the most revenue because they control spending on park visits, subscriptions, and merchandise.
How many Disney+ subscribers are there in 2026? Disney stopped publicly reporting subscriber numbers in February 2026. The last disclosed figures, from September 2025, were 196 million combined Disney+ and Hulu subscriptions, including 132 million Disney+ subscribers.
Does Disney target adults? Yes, and increasingly so. Adults without children are among Disney’s fastest-growing segments, monetized through park events, premium merchandise, cruises, and the deep streaming catalog. Franchises like Marvel and Star Wars were acquired largely to serve audiences aged 13 to 34.
Which market is Disney expanding into next? The Middle East. Disney’s seventh theme park resort, announced in May 2025, will be built on Yas Island in Abu Dhabi by partner Miral, positioning Disney to reach families across the Gulf region, India, and Africa.
Conclusion
The Disney target market looks broad from the outside, but the underlying logic is narrow and disciplined: recruit customers as children, monetize their parents, retain them as nostalgic adults, and hand the cycle to the next generation. The fiscal 2026 numbers show the model working where it matters, with a record $10 billion parks quarter and streaming finally profitable at scale.
The open questions are about yield, not reach. Premium pricing tests how long middle-income families stay in the funnel. Subscriber opacity shifts the burden of proof on streaming health to revenue and margin. And the Abu Dhabi bet will reveal whether Disney’s family-first formula travels to a region it has never directly served. For now, no competitor matches the breadth of Disney’s audience or the depth of its grip on each segment within it.