The $2.5 billion Foot Locker deal put two retail business models inside one company. Last quarter measured the gap between them at 1,218 basis points of gross margin, and the market took roughly $4.5 billion off Dick’s in a single session.
Dick’s Sporting Goods shares fell as much as 25% on August 25, 2026, the worst single-session drop in the company’s history, after management cut full-year earnings guidance by 17% at the midpoint. The damage sits almost entirely in one segment. The Dick’s namesake business grew comparable sales 4.9% and held a 12.6% segment operating margin. Foot Locker, bought eleven months earlier, comped down 3.6% and posted a $31.9 million operating loss. Both segments sell the same brands to overlapping customers in the same economy. The difference is how much of the assortment each one controls.
Simeon Gutman of Morgan Stanley opened the analyst call with the question the whole session turned on. He wanted to know what had changed since the team sat in those same seats 90 days earlier, raising guidance and sounding confident. Executive Chairman Ed Stack pointed at brands discounting on their own websites, at fuel prices, at pressured shoppers in Europe and the Middle East, at geopolitics.
Every one of those forces hit the Dick’s namesake stores too. Those stores grew.
What Happened
Consolidated net sales for the quarter ended August 1, 2026 reached $5.59 billion, up 53.2% on the prior year, with the increase coming almost entirely from adding Foot Locker’s $1.74 billion. Consolidated operating margin fell from 12.40% to 7.89%. Net income dropped 17% to $315 million, and diluted EPS fell 26% to $3.50, dragged further by the 9.6 million shares Dick’s issued to buy Foot Locker.
The segment table tells a cleaner story than the consolidated one. Dick’s gross margin came in at 37.85%. Foot Locker’s landed at 25.66%. Dick’s segment operating margin was 12.60% against Foot Locker’s negative 1.84%.

Management left the Dick’s full-year sales outlook untouched at $14.5 billion to $14.7 billion and kept the comp guidance at 2.5% to 4.0%. Foot Locker’s sales guidance came down to $7.4 billion to $7.5 billion, its comp outlook went negative, and its full-year segment profit turned into a guided loss of $40 million to $80 million. Consolidated EPS guidance dropped from a range of $13.27 to $14.27 down to $10.94 to $11.94.
At $128 a share, the low of the session, Dick’s market capitalization sat near $11.5 billion against roughly $16.05 billion at Monday’s close. One day of trading erased close to twice what the company paid for Foot Locker.
The Backstory
Dick’s signed the merger agreement on May 15, 2025 and closed on September 8, 2025. Total consideration ran to $2.5 billion: $2.1 billion in Dick’s stock, $223 million in cash, and $111.6 million from a stake Dick’s already held. Foot Locker shareholders chose between $24.00 in cash or 0.1168 Dick’s shares per Foot Locker share. Those who took paper received stock then worth about $219 apiece. It closed near $134 on the day of the print.
Foot Locker arrived carrying excess inventory, falling sales, tariff exposure on Asian production, and a decade of Nike allocation cuts. Stack took personal charge of the business, installed former Nike executive Ann Freeman over North America, and hired ex-Aldi UK chief Matthew Barnes to run Europe. He described the chain in late 2025 as having drifted from the basics of retail.
The first quarter of fiscal 2026 looked like proof the fix was working. Foot Locker’s proforma comp turned positive at 0.6%, the US Foot Locker banner comped up 6.4%, and the segment turned a $17.5 million operating profit. Dick’s put that in the headline of its May earnings release.
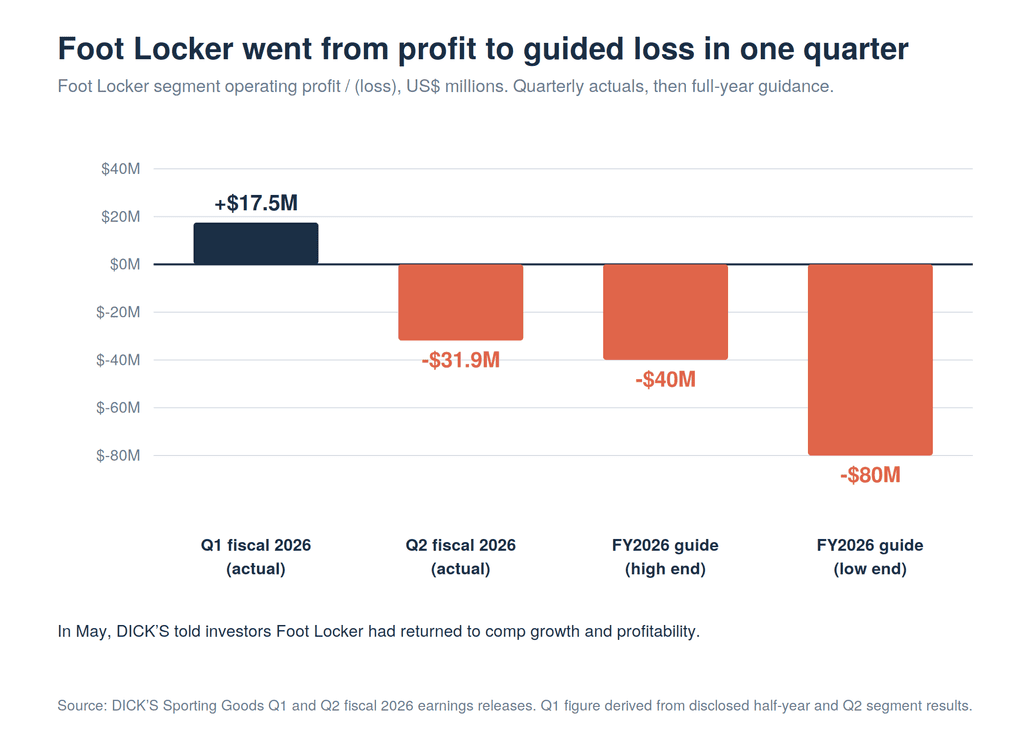
Ninety days later the same segment lost $31.9 million, a swing of $49.4 million in one quarter.
The Plan
Stack has not backed away from any of it. Dick’s is converting Foot Locker doors to a smaller “Fast Break” format that management says outperforms the legacy stores, reaching about 100 globally in the first quarter and targeting 300 to 350 by year end. The company closed 110 Foot Locker stores in fiscal 2026 so far, 67 of them flagged as unproductive assets, and cut the WSS banner from 143 doors to 99.
The stated financial prize is $100 million to $125 million of annual cost synergies, mostly from procurement and direct sourcing. Getting there requires up to $750 million of pre-tax cleanup charges, of which $515.8 million has already been booked.

Dick’s also matched competitors’ markdowns rather than ceding share, a decision Stack defended as a worthwhile investment while the market waits to recover. That choice shows up in the guidance: Dick’s own segment margin outlook slipped from 11.0% to 11.4% down to 10.6% to 10.9%, even though its sales outlook never moved.
The Business Model Angle
Foot Locker resells other companies’ shoes. In 2023, the last full year it reported alone, 65% of everything it bought came from Nike, and 84% came from its top five suppliers. It owns no meaningful product IP. Its assortment leans on launches and retro silhouettes that Nike, adidas, and On decide when to release, how many to make, and what to charge on their own sites. Footwear runs to roughly two-thirds of Nike’s revenue, and Nike Direct now moves a third of it. Stack pinned the quarter on Foot Locker’s “greater exposure to legacy footwear silhouettes” and on launches that underdelivered.
Read that as a description of the business model rather than a description of a bad quarter. A retailer whose gross margin depends on other people’s launch calendars has no mechanism to defend that margin when the calendar disappoints.
Dick’s namesake business carries the same national brands, and Nike matters there too. It also carries something Foot Locker does not. Its vertical brands, including DSG, CALIA, VRST, and Walter Hagen, generated $1.8 billion in fiscal 2025, about 13% of segment net sales, which makes Dick’s its own second-largest vendor at margins the company sets. Beyond that sit hardlines, golf, team sports, the GameChanger youth-sports platform, the Dick’s Media Network, and House of Sport formats that sell experiences alongside product. Nike can discount a running shoe on nike.com. It cannot discount a batting cage, a club fitting, or a CALIA legging.
That is where the 1,218 basis points of gross margin come from.
The deeper mechanic runs upstream. As we covered in the adidas vs Nike comparison, both brands now sit near a 60/40 wholesale-to-direct split after nearly a decade of opposite strategies. Owning a direct channel did not give either one pricing power. It gave them a second place to discount. When a brand cuts prices on its own site, it sets the clearing price for merchandise that a wholesaler has already bought, already paid for, and already put on a shelf. The brand books a promotion. The retailer books a markdown against inventory it owns.
Somebody in that chain absorbs the industry’s overproduction. Structurally, it is whoever holds the goods and cannot set the price. Dick’s spent $2.5 billion to add 2,478 more stores of exactly that position, at the point in the cycle when the brands upstream had finished building the tools to squeeze it.
The Dick’s business is not immune to any of this, which is the part worth sitting with. Its footwear exposure rose with the deal, it chose to match markdowns, and its own margin guidance came down 45 basis points as a result. The vertical brands, the services, and the media network do not make Dick’s untouchable. They give it a floor that Foot Locker does not have.
The Risk
Foot Locker carried $2.0 billion of the company’s $5.57 billion inventory at quarter end. Total inventory rose 63% year on year while Dick’s own inventory rose 6%. That $2.0 billion has to clear into the same promotional market that caused the problem, and Stack expects the promotions to run through the rest of the year.

Three further exposures deserve attention.
The balance sheet now carries $837 million of goodwill and $763 million of intangibles, most of it created by this deal. A segment guided to lose money for a full year invites an impairment test, and impairment would confirm in accounting what the share price already priced in.
Operating lease assets jumped from $2.42 billion to $4.75 billion. Closing a store removes the sales and the payroll. The lease stays until it expires or Dick’s buys its way out, which is part of why the cleanup bill runs to $750 million.
Then there is the diagnosis itself. Stack pointed at Europe and the Middle East as the weak spots. The disclosure says something else: Foot Locker International comped down 3.3% for the quarter against a total Foot Locker decline of 3.6%, which puts North America on the worse side of the average. Europe does carry a separate problem, since losses there generate no tax benefit under existing valuation allowances, pushing the effective tax rate toward 29%. Fixing a North American assortment problem with a European management change would waste a year.
Stack’s family holds Class B shares with supermajority voting control, so no activist investor is going to force a divestiture. Whatever happens next happens on the Stacks’ timetable.
Quick Questions
Did Dick’s overpay for Foot Locker? Price was not the failure. At $2.5 billion for a chain doing roughly $8 billion in sales, the multiple was modest. The problem is the shape of the asset. Dick’s bought scale in the one part of the athletic value chain with no control over its own gross margin.
Why did the Dick’s business grow while Foot Locker shrank? Assortment control and category mix. Foot Locker sells athletic footwear, most of it from suppliers who also sell direct. Dick’s sells footwear plus hardlines, golf, team sports, its own $1.8 billion vertical brand portfolio, and services. When footwear turns promotional, Dick’s has other places to earn.
Was the first-quarter turnaround fake? No. Foot Locker posted a real $17.5 million segment profit on a positive comp in Q1. It came from cost cuts, store closures, and inventory cleanup, all of which are one-time in nature. None of it changed who sets the price of a Jordan retro.
Can Fast Break fix this? Smaller stores with better productivity improve four-wall economics. They do not change supplier concentration or margin structure. Foot Locker needs owned product or exclusive product to move its gross margin, and building either takes years.
What should investors watch next? Foot Locker’s gross margin rather than its comp. A comp recovery bought with markdowns is worth less than a margin recovery, and the segment’s path back to break-even runs through the second number.
The Business Model Analyst Take
The Foot Locker deal has been read all day as a timing error, a big acquisition that ran into a soft consumer. The consumer explanation collapses the moment you look at the segment table. Two businesses, one company, one country, one quarter, opposite outcomes. Macro conditions cannot produce that.
What produces it is a difference in who owns the product. Dick’s spent fifteen years building vertical brands, services, and formats that give it revenue no supplier can discount away, and that work bought it a 37.85% gross margin last quarter. Then it spent $2.5 billion on a business that has almost none of that, at the exact moment Nike, adidas, and On finished building direct channels that let them set the clearing price on goods their wholesalers already own.
Stack’s response to the crisis is instructive on its own. He matched competitors’ markdowns to protect share and called it an investment. That is the correct move for a business with a margin buffer and the wrong move for one without. Applying it across both segments is how a problem in the acquired business becomes a problem in the parent.
The lesson generalizes past sneakers. In any value chain where suppliers can reach the end customer directly, distribution scale stops being a moat and becomes a liability with rent attached. The same test applies well outside sport, and we run it across categories in our business model comparison library. The retailers that survive the transition are the ones that become suppliers themselves. Dick’s understood this well enough to build $1.8 billion of it. Then it bought 2,478 stores that had not.