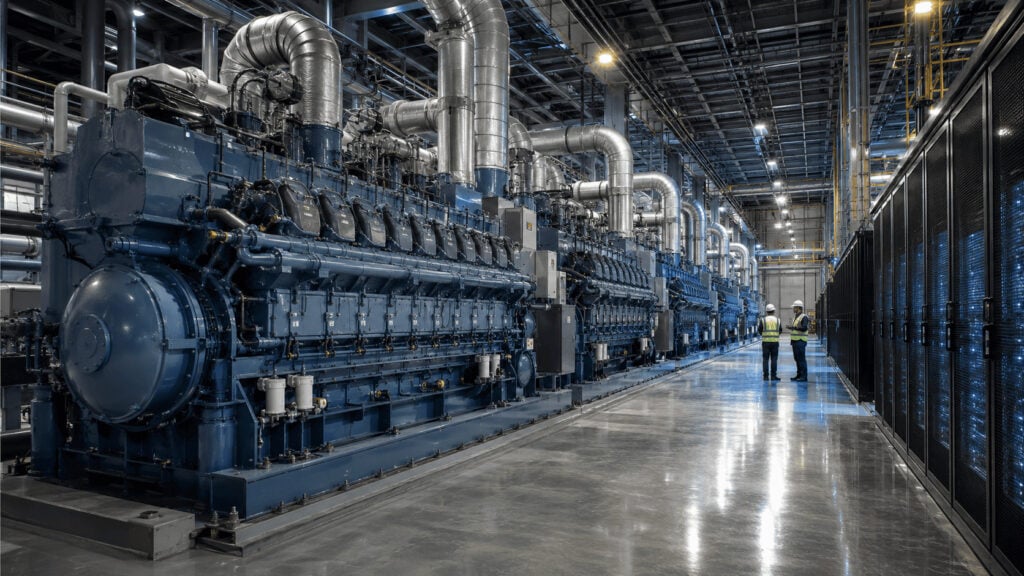

A few years ago, wiring gigawatts of AI compute to hundreds of engines pulled from the world of trucks and cruise ships would have sounded absurd. In mid-2026, it is a supply chain in overdrive, and it just minted a newly public winner.
The logic is brutally simple. Power, not chips, is the real bottleneck in the AI buildout, and the wait to connect a large new load to the grid has become the single slowest step in shipping a data center. So hyperscalers stopped waiting. They are buying their own generation and running it off-grid, and the fastest hardware they can get their hands on is not a giant utility turbine. It is a reciprocating engine.
The grid is the wall, so engines go around it
The connection queue is the whole story. Heavy-duty, utility-scale turbines can carry wait times of seven to eight years. Aeroderivative turbines, the lighter aircraft-derived kind, run up to three years. Reciprocating engines? One to two years, and often faster to install once they arrive. When a five-year queue delay can represent hundreds of millions in foregone revenue per megawatt, lead time beats efficiency every time.
That trade-off is now visible in the order book. Among US data-center projects that plan on-site natural gas and have disclosed timelines, roughly 55% expect to use gas turbines and about 29% plan on reciprocating engines, according to BloombergNEF. The turbine share is still bigger, but the smaller, uglier option is the one gaining ground, mostly because the better option is sold out.
Reciprocating engine vs. turbine. A reciprocating engine is the piston-driven type that powers cars, trucks, and ships. A gas turbine is a jet-style engine that spins a shaft with expanding hot gas. Turbines are bigger, more efficient, and cleaner per unit of output. Reciprocating engines are smaller, less efficient, more emissions-heavy, and need more frequent servicing. Their one decisive edge right now: you can actually get them.
Why the “worse” machine is winning
Availability is the headline, but engines carry a few real advantages that matter for AI-shaped demand.
They ramp fast. AI training and inference loads swing hard and often, and reciprocating engines respond to those swings faster than turbines, which also means the site needs fewer batteries to smooth things out. They handle heat. Engines lose less efficiency than turbines as the temperature climbs, which is why they suit hot-weather buildouts like Texas, where cheap natural gas keeps pulling data centers in. And they run dry. Unlike many turbine and cooling setups, they do not carry heavy water requirements, a growing liability as water use becomes a siting and permitting flashpoint.
Then there is cost. On BloombergNEF’s math, an engine-based off-grid system runs about $103 per megawatt hour over a 30-year span, against $106 to $109.50 for turbine-based systems and $140 for fuel cells. Cheapest, fastest, and heat-tolerant is a hard combination to argue with when the clock is the constraint.
The business model hiding inside the sale
Here is the part investors should actually care about, because the engine sale is not where the money is. The maintenance is.
Reciprocating engines need frequent servicing, and data centers run them harder than almost any traditional customer. Innio, the market leader, makes roughly 29% EBITDA margins on services versus about 15% on the equipment itself. RBC Capital Markets estimates data-center customers could throw off around 2.5 times more service revenue than Innio’s existing installed base. Read that carefully. The manufacturer sells a box at a thin margin, then earns for 30 years on the parts and labor that keep it running. It is the razor-and-blade model wearing a hard hat, and the AI boom just handed these companies the most demanding, highest-utilization blades they have ever sold.
That is the same instinct behind every smart picks-and-shovels bet in this cycle: find the bottleneck in a booming market and own the one component nobody can get fast enough. Engine makers did not have to invent anything. They just had to have inventory.
Innio is the purest way to play it
The demand is real across the field. Innio reported its data-center sales more than doubled year over year in its first quarter. Caterpillar’s reciprocating-engine backlog rose more than 3.5 times. Rolls-Royce said data-center revenue climbed 35% in the final quarter of 2025.
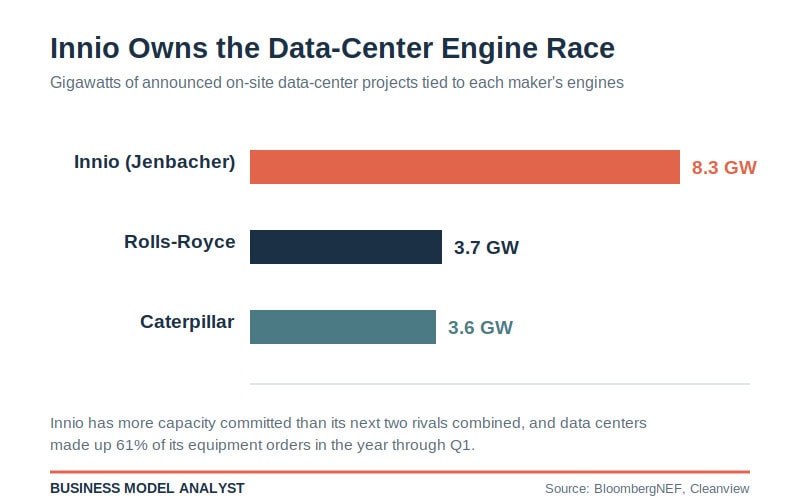
But exposure is not evenly spread, and that is what makes Innio interesting. Its Jenbacher engines are the most popular for data centers, with about 8.3 gigawatts of announced global projects attached to them, more than Rolls-Royce (3.7 GW) and Caterpillar (3.6 GW) combined. Vantage Data Centers alone plans to run 620 Jenbacher units, a total of 2.58 gigawatts, at its Stargate Frontier campus in Texas, per data firm Cleanview. Crucially, Innio’s engines are built specifically for stationary power, not repurposed from trucks or ships, and data centers made up 61% of its equipment orders in the year through Q1. Innio went public in June, and investors clearly like the concentration: the stock has run 46% above its IPO price, and its enterprise value sits near 34 times forward EBITDA, richer than diversified peers Caterpillar and Rolls-Royce, both below 30 times.
That premium is the pure-play tax. You get the cleanest exposure to the AI power grab, and you also get the cleanest exposure to whatever goes wrong.
The skeptic’s case: this is a capacity boom waiting to overbuild
Every enthusiastic hardware cycle carries the same risk, and the engine makers are walking straight into it. Caterpillar plans to lift large reciprocating-engine capacity to three times its 2024 level and grow turbine output 2.5 times. Innio intends to triple capacity to roughly 10 gigawatts by 2030. Everyone is expanding into the same forecast at once.
The scarier number is latent supply. Only about 15 gigawatts of engine-manufacturing capacity is currently dedicated to the power sector, but manufacturers across marine and heavy-duty uses can build around 250 gigawatts of engines in total, and repurposing a slice of that toward data centers would take only a modest investment, according to Thunder Said Energy. That is a lot of dormant supply sitting one decision away from flooding a hot market. It is also why the big, scarred incumbents like GE Vernova and Siemens Energy are expanding cautiously. They remember the power-equipment boom and bust of the early 2000s. The smaller engine makers largely do not, because they were not major power players back then.
There is a second-order risk too. This entire demand wave assumes the announced buildout gets built. It might not. A data-center announcement is a claim on power and capital, not consumption, and if hyperscaler capex cools or policy tightens around gas-fired, off-grid power, the order book can thin fast. In that world, the diversified makers just point their lines back at ships and oil rigs. Innio, the least diversified of the bunch, has nowhere else to send 61% of its orders.
Frequently Asked Questions
Why are data centers using engines instead of connecting to the grid?
Connecting a large new load to the electricity grid can take years, and some heavy-duty turbine setups carry waits of seven to eight years. Reciprocating engines can arrive in one to two years and install in months, so hyperscalers use them to start running compute far sooner than a grid connection would allow.
What is the difference between a reciprocating engine and a gas turbine?
A reciprocating engine is the piston-driven type used in cars, trucks, and ships. A gas turbine is a jet-style engine that spins a shaft with expanding hot gas. Turbines are larger, more efficient, and cleaner per unit of output, while reciprocating engines are smaller, ramp faster, and, right now, are far easier to buy.
Which company makes the most data-center engines?
Innio, whose Jenbacher engines have about 8.3 gigawatts of announced data-center projects attached to them, more than Rolls-Royce and Caterpillar combined. Its engines are built specifically for stationary power, and data centers made up 61% of Innio’s equipment orders in the year through the first quarter.
Are reciprocating engines cheaper than turbines for data centers?
On BloombergNEF’s estimates, an engine-based off-grid system costs about $103 per megawatt hour over 30 years, versus $106 to $109.50 for turbine systems and $140 for fuel cells. Engines also handle heat better and need far less water, which helps in hot, gas-rich states like Texas.
What is the biggest risk for engine makers like Innio?
Overbuild. Manufacturers can build roughly 250 gigawatts of engines across all uses, and repurposing even a slice toward data centers would take only a modest investment. If that latent supply floods the market or the AI buildout slows, pricing power shifts to buyers, and Innio, the least diversified maker, has the most to lose.
The Business Model Analyst Take
The engine story is a clean lesson in where value actually pools during an infrastructure land grab. It is not the flashy layer. It is the boring, physical, hard-to-source component that turns a permit into running compute, plus the multi-decade service annuity bolted onto it. That is a genuinely good business model, and the maintenance economics are better than the equipment margins suggest.
The catch is that “good business model” and “good stock at this price” are different questions. Innio is the sharpest expression of the thesis and the most fragile if the thesis breaks, and a 34-times multiple prices in very little disappointment. The tell to watch is not order growth, which everyone already expects. It is the overbuild. The moment 250 gigawatts of repurposable capacity starts leaking into the power market, pricing power shifts from the seller to the buyer, and customers stop taking whatever is available and start demanding the best technology at the lowest price. That is exactly when a pure-play premium becomes a liability. Right now the field looks bright. In a field this crowded and this enthusiastic, bright is precisely when disciplined operators start watching for exuberance.