
CXMT soared 466% on its first day of trading and became mainland China’s most valuable listed company. Investors priced it as the fourth member of a memory cartel. Its business model is the opposite of one.
On Monday, a chip maker almost nobody outside the semiconductor industry could name became the most valuable company listed in mainland China. ChangXin Memory Technologies, or CXMT, opened in Shanghai at 8.66 yuan a share and closed at 49. That is a 466% gain in a single session, a market capitalization of roughly $484 billion, and enough to leapfrog Industrial and Commercial Bank of China, an institution founded in 1984 with more than $6 trillion in assets.
The obvious story is national triumph. A decade-old company backed by Beijing has muscled into the most technically demanding commodity business on earth, and Apple is reportedly lobbying Washington for permission to buy its chips. That is a good story, and every major outlet has it.
The more useful story for anyone holding memory stocks, buying memory chips, or building hardware products is this: the memory industry’s spectacular 2026 profits do not come from making chips. They come from a decade of not making too many of them. And the market just handed $8.55 billion in fresh capital to the one participant whose mandate makes restraint impossible.
The Numbers Behind the Pop
CXMT’s first quarter of 2026 is the kind of financial statement that does not look real. Revenue reached about $7.5 billion, up from under $1 billion in the same quarter a year earlier. Net profit came in around $3.66 billion. That is a net margin near 50% on a commodity product.
For context on how new this is: CXMT’s full-year 2025 revenue was roughly $8.6 billion, up 156% from about $3.3 billion in 2024. The company turned its first annual profit that year, around $1 billion. In a single quarter of 2026, it nearly matched an entire year of 2025 sales.
The IPO priced conservatively at 8.66 yuan, a figure analysts read as deliberately cheap to guarantee a debut pop. It worked. Lottery winners who got allocation more than quintupled their money in a day.
Memory’s Real Product Is Restraint
Here is what most coverage of the memory boom gets structurally wrong.
DRAM is a commodity. The chips are close to interchangeable, the fabs cost tens of billions, and the fixed cost base is enormous. Under textbook conditions, that combination produces brutal price wars and terrible returns, which is exactly what memory delivered for most of its history. Dozens of manufacturers entered the business since the 1970s. Almost all of them died.
What changed after 2016 was not technology. It was structure. The survivors consolidated into three firms, Samsung, SK Hynix and Micron, which together control more than 90% of DRAM output. Three players in a capital-intensive commodity market can do something dozens cannot: they can practice capacity discipline. They can decline to build the marginal fab. They can shift wafers toward high-bandwidth memory for AI servers and let commodity supply tighten rather than chase volume.
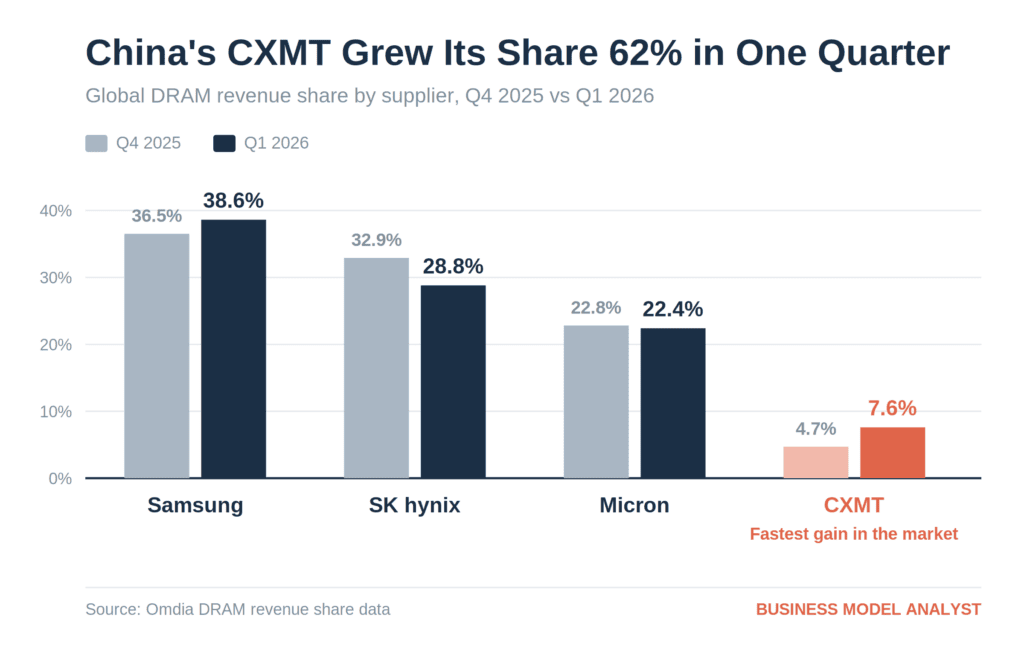
That discipline is the actual asset. It is why Micron posted an 84.9% gross margin on a product that is functionally a bulk good. It is why contract DRAM prices rose roughly 90% in the first quarter of 2026 and another 60% in the second. It is why three memory makers are now collectively worth more than the world’s largest oil companies. It is also why Apple raised prices across nearly its entire Mac and iPad line.
Restraint is a business model. And business models built on restraint have exactly one failure mode: a participant who does not have to be restrained.
CXMT Has Already Run This Play Once
This is not a hypothetical risk. It is a rerun.
In May 2024, DDR4 prices began falling in near-perfect sync with CXMT’s arrival as a volume supplier. Chinese memory makers were reportedly selling DDR4 at up to 50% below what Micron, Samsung and SK Hynix were charging. Some of that pricing landed below the cost of reballed second-hand chips pulled from scrapped hardware.
The big three did not fight it. They exited. All three began phasing out DDR4 because at those prices the product no longer cleared their margin hurdles, and redirected the capacity toward DDR5 and HBM. Then, in late 2024, Beijing reportedly directed CXMT to convert its own production from DDR4 to DDR5 as fast as it could manage. CXMT complied. DDR4 supply vanished from the market and prices spiked so hard that by mid-2025 old DDR4 was selling at rough parity with newer DDR5.
Read that sequence again, because it contains the whole thesis. A single company’s capacity decision moved global pricing for an entire memory generation, twice, in opposite directions, inside eighteen months. And the decision that moved it the second time was not made by the company. It was made by a government.
A Company That Never Needed to Make Money
Every listed memory maker operates under the same constraint: build too much capacity into a boom, and the resulting bust destroys your shareholders. That fear is the enforcement mechanism behind the entire oligopoly. It is why nobody defects.
CXMT has spent its existence demonstrating that the constraint does not apply to it.
Between 2016 and 2024, the company accumulated roughly $5 billion in unrecovered losses while scaling capacity. No Western or Korean competitor could have absorbed eight consecutive years of that and kept building. CXMT could, because its capital came from China’s national chip investment fund and from the city of Hefei, where it is based, and because the objective was never return on invested capital. The objective was domestic self-sufficiency in a component that the United States can otherwise switch off.
That is the business model. Not “sell memory profitably.” It is “convert state capital into installed capacity until China no longer depends on foreign memory.” Profit is a pleasant side effect of the current shortage, not the goal, and it arrived only in year nine.
Now add $8.55 billion of IPO proceeds, earmarked by the company for upgrading production lines and technology. The 466% pop was not a reward for past performance. It was ammunition for future capacity.
What Investors Actually Bought
Here is the uncomfortable symmetry. The investors who bid CXMT to a $484 billion valuation did so on the strength of shortage-era economics: 50% net margins, triple-digit revenue growth, prices rising every quarter.
Those same investors just financed the capacity expansion most likely to end shortage-era economics.
You can hold both positions at once only if you believe CXMT will join the cartel rather than break it. Ten-year-old state champions built explicitly to eliminate import dependence do not typically join cartels. They undercut them, because share is the mandate and margin is not.
The Case Against This Thesis
Intellectual honesty requires the counterargument, and it is stronger than the bulls on this trade probably realize it needs to be.
Export controls are a real ceiling. CXMT cannot buy the most advanced Western chip-making equipment. It compensates with multi-patterning, squeezing more circuitry onto a wafer through additional lithography passes. That works, but it multiplies error opportunities and drags yield. Independent analysis puts CXMT’s mature yields below the 85% to 90% industry standard. Lower yield means higher cost per good die, which limits how far it can undercut before it is bleeding again.
It cannot touch the crown jewels. More than 98% of CXMT’s revenue comes from conventional DRAM. It has no meaningful HBM business. It is currently sampling HBM3, a generation SK Hynix commercialized about four years ago, with trial production targeted for the end of this year. The highest-margin AI memory is not under threat from Hefei any time soon.
Beijing may keep the capacity at home. CXMT told regulators its capacity still falls short of Chinese demand, and Beijing has instructed domestic memory makers to serve local buyers first. Capacity that never reaches the global merchant market cannot crash global prices directly.
All three points are valid. None of them are as protective as they sound. Commodity DRAM is where the incumbents’ windfall currently lives, because AI scarcity has repriced ordinary memory alongside the specialized kind. And every gigabyte of Chinese demand that CXMT serves domestically is a gigabyte Samsung, SK Hynix and Micron no longer sell into the world’s largest electronics manufacturing base. Displacement does not require exports.
The Second Shoe
CXMT is not the only listing coming. Yangtze Memory Technologies, or YMTC, which makes NAND flash rather than DRAM, is preparing its own Shanghai offering as soon as this year. It is building three factories that would more than double its capacity by the end of 2027.
That matters for how you read Monday. This was not a one-off IPO. It is the opening move in a financing program that converts public equity markets into capacity for both halves of the memory industry at the exact top of the pricing cycle.
What Operators Should Take From This
The transferable lesson has nothing to do with semiconductors.
Any industry whose profitability rests on tacit supply discipline among a small number of players is structurally fragile in a specific way: it is not vulnerable to a better competitor, it is vulnerable to an indifferent one. A rival optimizing for something other than returns, whether that is a state mandate, a strategic loss leader inside a larger platform, or a venture-funded land grab, does not respond to the incentives that keep the peace. Your competitors’ rationality is load-bearing, and most companies never audit it.
If you sell into a concentrated market with unusually good margins, the question is not who might build a better product. It is who might show up who does not care about margin at all. Vertically integrated giants understand this instinctively, which is why they hold capacity they do not strictly need.
The Business Model Analyst Take
We have argued repeatedly that the memory supercycle is a pricing event wearing a structural costume, and that the rotation into memory stocks was a bet that this cycle breaks the historical pattern. What was missing from that argument was a named mechanism for the ending.
Monday supplied it. The mechanism is a state-backed manufacturer with below-standard yields, a domestic-first mandate, a documented history of pricing to win share rather than to earn returns, and now a war chest raised from investors who appear to believe it will behave like the incumbents it was built to replace.
The near-term trade may still work. Shortages have momentum, AI demand is genuinely enormous, and CXMT’s technical ceiling is real. But the structural read is clear enough. The memory oligopoly’s margins were never protected by technology. They were protected by the fact that everyone in the room had shareholders to answer to. There is now a fourth chair, and the company sitting in it spent eight years losing money on purpose to get there.
Price that accordingly.