
Customer acquisition costs are rising fast enough to distort strategy if you measure them casually. A 2024 Amplitude analysis tracking over 1,000 global businesses put the average CAC at $200 per new customer, up from $174 in 2023, and identified 3:1 as the benchmark CLV-to-CAC ratio for healthy growth. Businesses below 2:1 reported a 60% higher probability of cash flow crises within 12 months (Amplitude's guide to customer acquisition cost).
That data changes the conversation. CAC isn't just a finance metric for month-end reporting. It's one of the clearest tests of whether a company's growth model is working.
Most CAC advice stops at a simple formula. That's where errors begin. In practice, customer acquisition cost calculation becomes difficult when a company has long sales cycles, multiple channels, shared overhead, high-touch onboarding, or customer success teams that do part of the work of winning the account. For executive teams, those details matter more than the formula itself.
What Is Customer Acquisition Cost and Why It's More Than a Formula
A small change in CAC assumptions can rewrite the economics of a growth plan. In B2B SaaS, one omitted cost bucket, especially onboarding or solution engineering tied to closing and activating accounts, can make a channel look profitable when it is only being subsidized elsewhere in the business.
Customer acquisition cost calculation starts with a simple equation: total sales and marketing cost divided by the number of new customers acquired in the same period. The math is simple. The operating reality is not.
A useful CAC number depends on whether the company measures acquisition the way customers are won. If finance captures paid media but excludes SDR compensation, the result is understated. If sales includes reactivated accounts, partner handoffs, or expansion deals in the “new customer” count, the denominator is distorted. If implementation teams carry meaningful pre-launch work required to secure enterprise contracts, the standard formula misses part of the true cost of acquisition.
The basic formula is not the strategic insight
The standard model is:
CAC = Total Sales and Marketing Costs / New Customers Acquired
That equation only becomes decision-grade after leadership defines three inputs with discipline:
- Total sales and marketing costs
- New customers
- The period being measured
The arithmetic is the easy part. The strategic value comes from boundary setting.
For example, a self-serve SaaS company can often isolate media, lifecycle tooling, and growth salaries with reasonable precision. An enterprise SaaS company usually cannot. Sales engineering, procurement support, executive time in late-stage deals, security reviews, and high-touch onboarding may all contribute to winning the account. Excluding those costs produces a lower CAC, but not a truer one.
CAC is not just a reporting metric; it is a summary of how your business model converts spend into customers.
Why executives should care
A well-defined CAC reveals where the business model is under strain:
| What CAC reveals | Strategic implication |
|---|---|
| Cost to create demand | Whether growth is capital-efficient |
| Sales process complexity | Whether go-to-market design matches deal size |
| Channel quality | Whether budget allocation is rational |
| Onboarding intensity | Whether post-sale resources are subsidizing acquisition |
| Pricing resilience | Whether margins can support scale |
In practice, CAC becomes more useful when it is tied to the Business Model Canvas rather than reviewed as a standalone metric. Rising CAC can point to weaknesses in multiple blocks at once: an unclear value proposition that forces heavier sales effort, channels that no longer convert efficiently, customer segments that require custom onboarding, or a revenue model that cannot absorb long payback periods. That framing turns CAC from a finance ratio into an operating diagnosis.
The broader shift toward efficiency-first growth reflects that pressure. Companies facing higher acquisition costs are being forced to prove that their customer economics work under real cost allocation, not idealized assumptions. That argument is developed further in this analysis of efficiency-first consumer acquisition economics in 2026.
One more practical point belongs here. Some acquisition-related expenses have accounting and tax implications that finance teams should review alongside CAC policy. If you need a starting point, Optimize your company's tax deductions.
For an executive team, the key question is not whether the company can calculate CAC. It is whether the number reflects how the company wins customers, activates them, and earns back that investment.
A Practical Guide to Auditing Your Acquisition Spend
A CAC figure can be wrong by a wide margin even when the spreadsheet reconciles perfectly. The usual failure is incomplete cost capture, especially in businesses where acquisition does not end at contract signature.
That problem is acute in B2B SaaS. A company may count paid search, SDR salaries, and sales commissions, then exclude solution engineering support, onboarding labor needed to activate the account, revops time, and management oversight tied to winning and ramping a new customer. The result is a CAC number that looks disciplined but understates the actual investment required to turn demand into revenue.
Start with a finance-first audit
Begin in the general ledger, payroll system, procurement records, and departmental budgets. Ad platform exports are useful, but they show only a subset of acquisition spend. Finance records show what the company paid.
Use one rule across the audit: review any cost the business incurs to attract, convert, or activate a new customer. For self-serve products, activation costs may be minimal. For enterprise SaaS, they often are not. If onboarding is high-touch and consistently required before the customer reaches first value, leadership should decide explicitly whether that cost sits inside CAC, in a separate activated CAC metric, or in implementation cost reporting. Leaving it unclassified creates false efficiency.
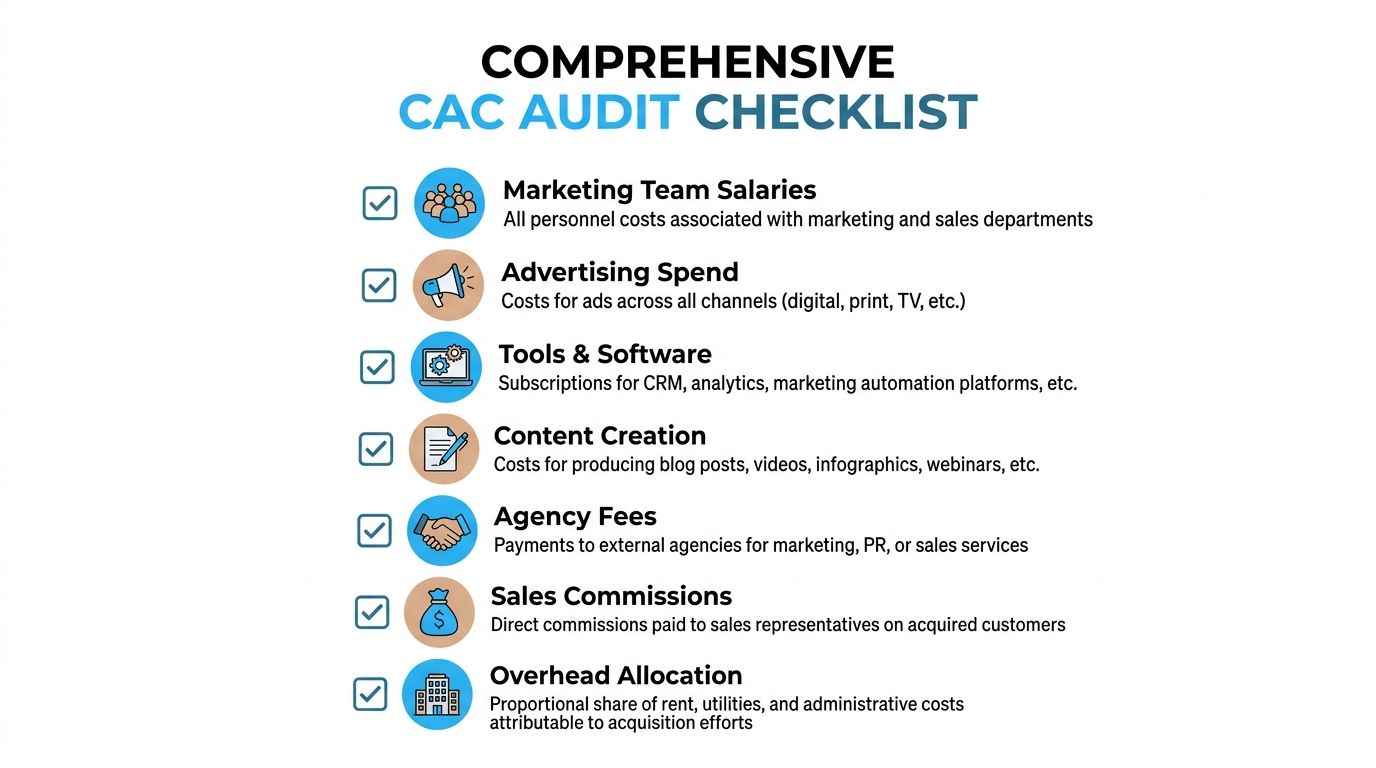
What belongs in the numerator
Use the numerator as an operating map of how the company wins customers.
- Paid media and campaign spend. Include search, social, display, sponsorships, affiliates, events, and acquisition-focused partnerships. Pull from billing records and finance close files, not only from channel dashboards.
- Sales compensation. Include salaries, commissions, bonuses, payroll taxes, and benefits for teams focused on new logo acquisition.
- Marketing payroll. Include demand generation, content, performance marketing, field marketing, partner marketing, and other roles tied to pipeline creation.
- Software and tools. Include CRM, marketing automation, prospecting tools, attribution systems, webinar software, analytics, and creative platforms used in acquisition workflows.
- Agency and contractor fees. Include media buying, SEO, creative production, outsourced SDR work, PR tied to pipeline generation, and campaign operations support.
- Content production costs. Include writers, designers, video editors, webinar production, landing page development, and other assets created to acquire net-new customers.
- Pre-sales and onboarding support tied to new logos. Include solution consultants, implementation staff, or customer success resources if their work is consistently required to close or activate a customer. This is one of the biggest blind spots in B2B SaaS CAC policy.
The costs companies miss most often
The recurring omissions are rarely dramatic line items. They are shared costs that no team owns clearly enough to classify.
- Overhead allocation. Office costs, software administration, recruiting support, and other operating expenses assigned to sales and marketing functions.
- Management time. Time spent by sales leaders, marketing leaders, finance partners, and executives on pipeline reviews, deal support, pricing approvals, and acquisition planning.
- Revenue operations and enablement. Reporting, list operations, CRM administration, training, and sales enablement when those functions directly support new customer acquisition.
- Shared infrastructure. Data tools, BI support, and workflow systems used across acquisition and retention. These need an allocation rule, not a guess.
A low CAC built on partial cost capture is not operational efficiency. It is a classification problem.
Make your chart of accounts useful for strategy
Many finance systems were set up for statutory reporting, not go-to-market diagnosis. That is why CAC audits often stall. The expense data exists, but it is grouped too broadly to separate acquisition from retention or shared operating support.
A better setup uses tags, cost centers, or subaccounts that map spending to the customer journey. This is also where CAC becomes more useful inside the Business Model Canvas. If acquisition costs are concentrated in channels, customer relationships, or key activities that require too much manual effort, the audit points to a model issue, not just a measurement issue. A heavy onboarding burden, for example, may signal a product adoption problem or a customer segment mismatch rather than a sales productivity problem.
That same clean-up has tax implications. If leadership is revising how expenses are classified, it is worth reviewing Optimize your company's tax deductions for a practical view of how companies document and categorize business spending.
A simple policy framework helps:
| Expense bucket | Treatment in CAC |
|---|---|
| New customer acquisition | Include |
| Retention and expansion | Exclude from strict CAC |
| Shared cost | Allocate using a consistent rule |
Consistency matters more than perfection in the first pass. If the allocation logic is stable, leaders can compare periods, channels, and segments with confidence.
That becomes more important as the acquisition engine gets more layered. Omnichannel brands and multi-motion SaaS companies often add tools, agencies, content programs, and partner activity faster than finance taxonomy keeps up. The result is a go-to-market stack that grows harder to measure with each added layer, which is why this breakdown of how DTC brands build a marketing stack that hits $10M ARR is useful context for auditing spend discipline as systems expand.
Advanced Calculation Models for Real-World Scenarios
The basic CAC formula breaks down in two common situations. First, when the sales cycle is long. Second, when leaders rely on one blended average across all channels.
Both errors are common because the aggregate number feels clean. It also hides operational truth.
Time-weighted CAC for long sales cycles
A company with a short self-serve purchase path can often align spend and acquisition within the same month. A company selling enterprise software usually can't. The conversion happens now, but the work that produced it may have started weeks earlier.
That timing issue matters. A critical pitfall in CAC calculation is temporal misalignment, and expert methodology recommends a time-weighted model because ignoring sales-cycle lag can inflate costs by 15% to 25%. One example formula is:
CAC = (Marketing Expenses (n-60) + 0.5 × Sales Expenses (n-30) + 0.5 × Sales Expenses (n)) / New Customers (n)
In this model, n is the current month, and the cost inputs are offset to reflect the fact that B2B and some B2C deals often close after 30 to 60 days of prior effort.
That's a better decision tool than a same-month formula because it aligns cause and effect. If you ignore lag, one month looks artificially expensive and the next looks artificially efficient. The team then cuts a channel that was working or expands one that only appears cheap because the cost landed earlier.
Treat CAC like a cohort metric when the sales cycle is long. Calendar-month accounting alone won't tell you what actually drove conversion.
Blended CAC versus channel-specific CAC
A blended CAC is useful for board-level summaries. It's weak as a budget allocation tool.
The strategic risk is simple. Averages flatten variation. One low-cost channel can mask another that burns capital. One high-conversion segment can make a weak campaign look acceptable. Leadership sees a “reasonable” blended number and misses the fact that budget is subsidizing inefficiency.
Benchmark data points to a specific failure mode here. Failing to calculate CAC per channel leads to a 20% misallocation of marketing budgets. Top startups reduce CAC by 10% to 15% annually by shifting spend based on granular, per-channel tracking rather than relying on aggregate metrics.
A practical way to think about the difference:
| Model | Best use | Main weakness |
|---|---|---|
| Blended CAC | Executive summary, board reporting, trend monitoring | Hides channel variance |
| Channel-specific CAC | Budget allocation, optimization, campaign decisions | Requires cleaner attribution and cost tagging |
The most useful management view is usually layered:
- Blended CAC for total company efficiency
- Channel CAC for budget decisions
- Segment CAC for pricing, sales motion, and product-market fit analysis
That structure also makes CAC easier to pair with funnel analytics. If a paid channel generates many leads but few qualified opportunities, its CAC may look tolerable only because the blend absorbs the waste. Frameworks built around acquisition, activation, retention, revenue, and referral can help teams make that diagnosis systematically, including tools like the Pirate Metrics Canvas.
The deeper point is this. CAC isn't one number. It's a family of numbers used for different decisions. The company that reports only one version usually optimizes too late.
Interpreting Your CAC LTV Ratios and Payback Periods
A company can post efficient-looking CAC and still create a cash problem. The reason is simple. Acquisition cost on its own says little about value created or how quickly that value returns to the business.
The decision-grade view pairs CAC with two measures. First, the LTV:CAC ratio tests whether a customer relationship is economically attractive. Second, payback period tests whether that growth is financially tolerable in real operating conditions.
The ratio that turns CAC into a business signal
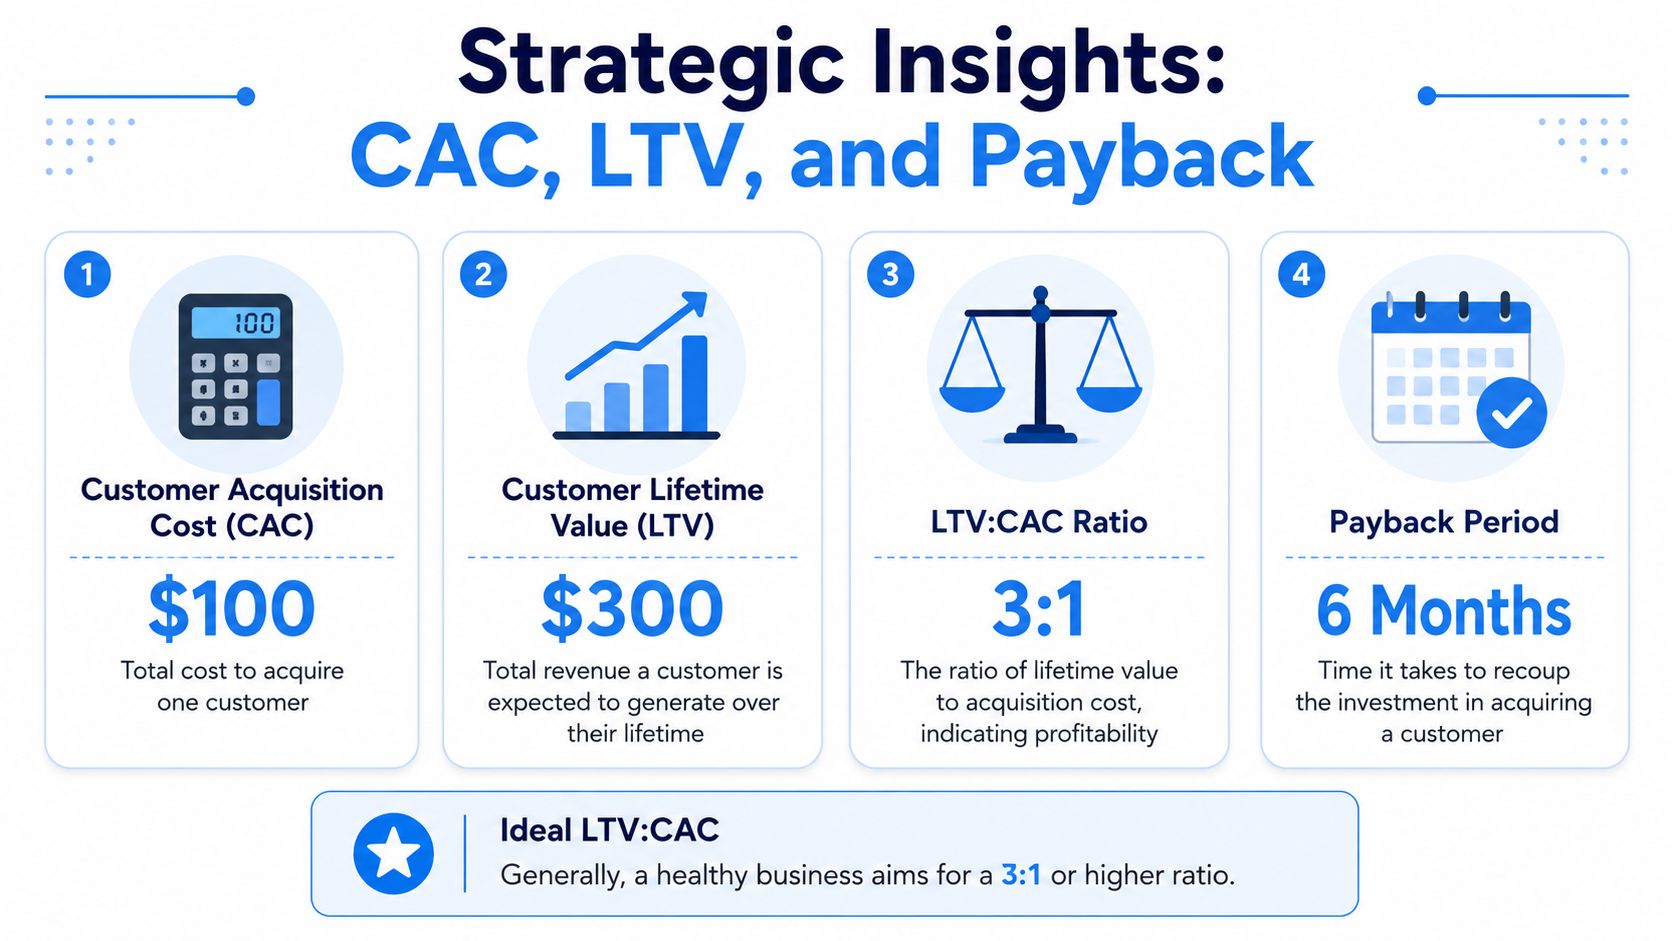
Amplitude's 2024 benchmark places a healthy CLV:CAC ratio at 3:1, and reports materially higher cash flow risk for businesses that fall below 2:1 (Amplitude's CLV-to-CAC benchmark). That benchmark matters because it shifts the conversation from marketing efficiency to capital efficiency.
A higher CAC can be rational. Enterprise SaaS often requires sales engineering, procurement support, implementation work, and high-touch onboarding before the customer reaches steady-state usage. If those accounts retain well, expand over time, and produce strong gross margin, a headline CAC that looks high in isolation may still be the right trade.
A low CAC can also mislead. It may reflect underinvestment in channels that could scale, a pricing model that caps lifetime value, or weak onboarding that attracts easy-to-close customers who never become durable revenue.
How to read the ratio
The ratio is useful only when finance, sales, and product teams interpret it the same way.
- Around 3:1. Unit economics are often in a range consistent with disciplined growth.
- Below 3:1. The company may be paying too much to acquire demand, pricing below value, retaining poorly, or loading too many post-sale costs into the journey.
- Far above 3:1. The company may have room to increase acquisition spend, especially if conversion quality is strong and sales capacity is not constrained.
The strategic point is less obvious than the formula. LTV:CAC is not only a marketing ratio. It is a test of whether the full customer model works, including pricing, retention, onboarding, support intensity, and expansion revenue. In B2B SaaS, generic CAC guidance often falls short. If onboarding requires customer success managers, solution consultants, or implementation specialists before the account reaches value, leadership needs to decide whether those costs belong in acquisition, delivery, or both for planning purposes. That accounting choice changes the ratio, and it can materially change how attractive a segment appears.
This is also where the metric connects to the Business Model Canvas. The ratio is partly shaped by Channels, but it is also shaped by Revenue Streams, Cost Structure, and the value proposition's ability to support retention and expansion. A company with a solid top-of-funnel engine but weak activation or slow implementation can look efficient on lead generation while destroying economics after the contract is signed.
Board-level view: CAC shows what growth costs. LTV shows whether the customer relationship can carry that cost.
Payback period is the liquidity test
LTV:CAC measures attractiveness over the life of the customer. Payback period measures how long the business has to fund the gap.
The standard approach divides CAC by the gross profit contribution generated by a new customer over a recurring interval, usually monthly in subscription models. The output is the number of months required to recover acquisition spend. For executive teams, that figure often matters more in the near term than lifetime value because payroll, channel commitments, and implementation costs are paid now, not over the full customer lifespan.
This gets more complex in real operating environments. A B2B SaaS company may close a customer in month one, assign onboarding specialists in months one through three, and see full product adoption only in month four or five. If those onboarding costs are omitted from acquisition economics, payback appears faster than the cash cycle actually is. If they are included, the company gets a more realistic view of how much working capital growth consumes.
That distinction affects planning. A business can report an acceptable LTV:CAC ratio and still strain cash if recovery is slow. Finance sees it in deferred hiring, tighter spend controls, and reduced tolerance for channel experiments. Commercial teams often misread that constraint as a demand problem when it is really a payback problem.
If your team is trying to connect CAC analysis with a more complete commercial accountability model, this guide on practical steps for proving ROI is useful because it shifts the conversation from spend reporting to return discipline.
The executive takeaway is clear. Customer acquisition cost calculation becomes useful when it is tested against both lifetime economics and cash recovery speed. One shows whether growth creates value. The other shows whether the company can fund that growth without stressing the business.
Using CAC to Drive Strategic Business Decisions
Most companies still treat CAC as a marketing KPI. That's too narrow.
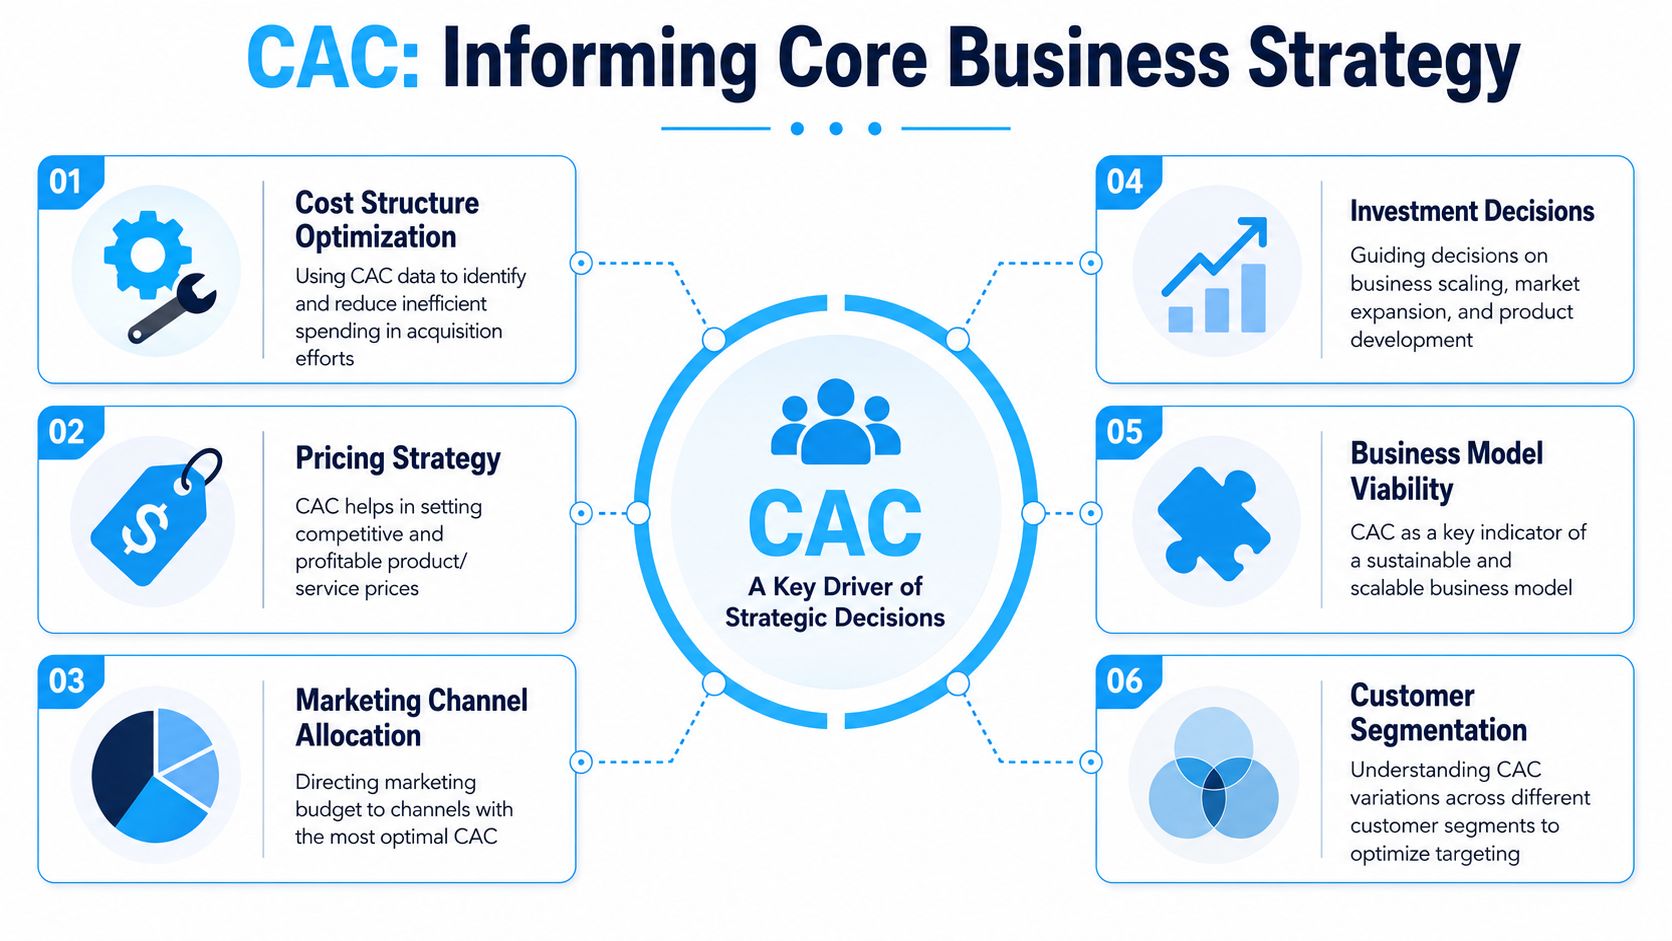
CAC belongs in strategy because it shapes the economics of the whole business model. It directly affects cost structure, pricing flexibility, channel design, investor confidence, and even whether a customer segment is worth serving at all.
CAC inside the Business Model Canvas
Two blocks of the Business Model Canvas are immediately shaped by CAC.
First is Channels. If one route to market has structurally high acquisition costs, the company may need to redesign the channel mix, improve conversion architecture, or narrow targeting. Second is Cost Structure. If acquisition costs consume an outsized share of contribution margin, the business model may need higher pricing, better retention, or a different sales motion.
CAC transcends mere reporting. It becomes a design constraint. A company cannot claim its model scales if acquiring each incremental customer requires cost structures that margins can't support.
CAC inside SWOT and executive planning
In a SWOT analysis, CAC often reveals truths leadership teams prefer to soften.
- Strength. The company wins customers efficiently through channels or segments that competitors struggle to access.
- Weakness. The company depends on expensive paid acquisition, heavy sales support, or operationally messy handoffs.
- Opportunity. Referral-driven, product-led, or partner-led growth may lower acquisition cost while improving sales efficiency.
- Threat. Rising media costs, longer sales cycles, channel saturation, or compliance-heavy onboarding can make current CAC assumptions obsolete.
That framing matters because CAC is rarely just a marketing operations issue. It often points to a deeper strategic mismatch between offer design, channel choice, and delivery model.
Why high-touch SaaS needs a different CAC model
Generic CAC guidance often falls short. In high-touch B2B SaaS, the customer often isn't “acquired” at contract signature. The deal closes commercially, but adoption still depends on onboarding teams, implementation specialists, and customer success staff who make the account usable.
A 2025 McKinsey study on B2B SaaS found that including post-sale onboarding and customer success salaries in the CAC formula increased the average calculated CAC by 27% for enterprise clients. For high-service models, that adjustment is not optional if leadership wants a defensible view of unit economics.
Consider the strategic implication. If a SaaS company wins enterprise accounts through a high-touch process and excludes onboarding from CAC, leadership may:
- Overestimate channel efficiency
- Underprice implementation-heavy contracts
- Expand sales headcount into segments that are unprofitable
- Present investors with overly optimistic payback assumptions
Enterprise SaaS often closes revenue before it secures successful adoption. If onboarding is required to realize the sale, part of that cost belongs in acquisition economics.
What investors want to see
Investors don't just want growth metrics. They want evidence that growth can scale without absorbing disproportionate capital.
That means CAC should be presented alongside:
| Metric | Why it matters in a pitch |
|---|---|
| CAC | Shows what new revenue costs to generate |
| LTV:CAC | Shows whether acquisition is economically sound |
| Payback period | Shows how quickly the business recovers cash |
| Segment or channel CAC | Shows management discipline and optimization maturity |
The strongest pitch decks don't present CAC as a vanity efficiency number. They show that management understands what sits inside it, where it varies, and how it links to the broader business model. For executive teams, that's the strategic use of customer acquisition cost calculation. It turns growth from a headline into an operating system.
Common CAC Pitfalls and How to Optimize Your Spend
Bad CAC management usually comes from a few recurring errors. Each one creates a false sense of efficiency. Each one also has a practical fix.
Pitfall one: mixing acquisition with retention
If the numerator includes retention or reactivation spending while the denominator counts only new customers, CAC gets inflated. If the team does the reverse and counts returning users as new customers, CAC gets artificially lowered.
The fix is governance, not guesswork. Define acquisition costs and retention costs as separate operating buckets, and force every channel owner to classify spend accordingly.
Pitfall two: relying on blended averages
This is the classic channel isolation error. Benchmark guidance shows that failing to calculate CAC per channel leads to a 20% misallocation of marketing budgets, while top startups reduce CAC by 10% to 15% annually by reallocating spend based on granular channel tracking.
The optimization move is straightforward:
- Break out channel-level CAC. Review PPC, organic, partnerships, referrals, outbound, events, and affiliates separately.
- Reallocate with discipline. Shift budget only after validating conversion quality and downstream value, not just lead volume.
- Tag shared costs carefully. Don't dump SEO content costs into paid social or vice versa.
Pitfall three: ignoring sales-cycle lag
For companies with longer deal cycles, same-month CAC creates noise. The team reads calendar artifacts as performance signals.
The fix is to adopt a lag-aware model and review CAC on a cohort basis where possible. That makes hiring, channel investment, and forecasting much more stable.
Pitfall four: undercounting high-touch acquisition work
This is common in enterprise SaaS, regulated services, and consultative sales models. The contract gets signed by sales, but onboarding and customer success do part of the work required to secure a viable customer relationship.
The fix is to test an expanded CAC model for segments where post-sale activation is operationally inseparable from acquisition. If the economics change meaningfully, leadership should manage to the expanded model.
The fastest way to improve CAC isn't always cutting spend. Often it's removing measurement errors that hide where spend is actually working.
Practical optimization moves that hold up
- Improve conversion quality. Better landing pages, cleaner qualification rules, and tighter sales handoffs increase customer yield from existing spend.
- Use referral channels aggressively. Benchmark guidance shows referral channels can produce materially lower CAC than paid advertising.
- Audit tooling overlap. Many teams carry redundant prospecting, analytics, and automation subscriptions that add cost without improving win rates.
- Review segment fit. Sometimes the problem isn't campaign efficiency. It's that the company is pursuing customers who are too expensive to win relative to value.
Customer acquisition cost calculation becomes powerful when leadership stops asking for one clean number and starts asking better questions about how growth happens.
The best strategy work starts with honest unit economics. If you want sharper frameworks for evaluating CAC inside your broader business model, explore The Business Model Analyst for practical analysis on business model design, growth strategy, and tools like the Business Model Canvas and SWOT analysis.