A SWOT analysis of Crocs maps the strengths, weaknesses, opportunities, and threats shaping one of the strangest success stories in footwear. The foam clog that people once mocked now anchors a business that cleared $4 billion in revenue in 2025. That scale did not buy calm. Crocs enters 2026 running two brands moving in opposite directions, leaning on overseas shoppers to cover a shrinking home market, and cleaning up a 2022 acquisition that turned into a $737 million writedown.
This analysis uses Crocs, Inc.’s FY2025 results, its Q1 2026 report, and the company’s own 2026 outlook, so the picture reflects where the business stands now rather than where it sat at its pandemic-era peak.
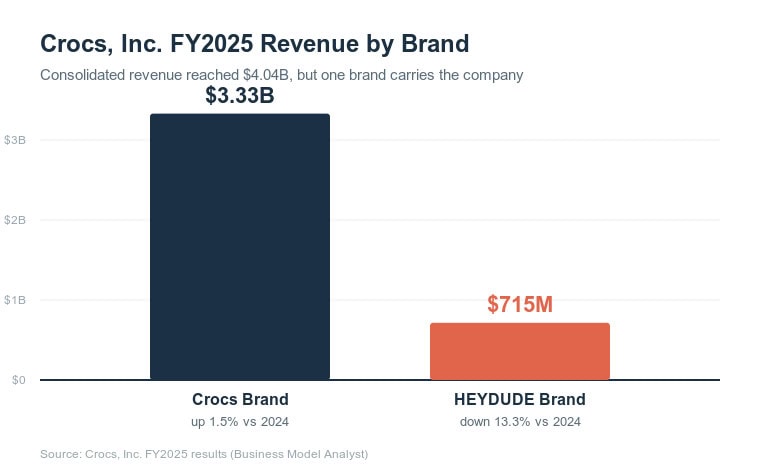
Crocs SWOT Analysis at a glance Crocs, Inc. (NASDAQ: CROX) runs two segments, the Crocs Brand and HEYDUDE, and sells in more than 80 countries. FY2025 revenue was $4.04 billion, down 1.5% from 2024. The Crocs Brand grew 1.5% to $3.33 billion on double-digit international gains, while HEYDUDE fell 13.3% to $715 million and forced a large impairment. Adjusted diluted EPS came in at $12.51, operating cash flow reached roughly $700 million, and management repurchased about 10% of shares outstanding. The core strength is a high-margin, globally expanding Crocs Brand. The core problem is HEYDUDE and a North American market that keeps softening.
Crocs SWOT Analysis Summary
| Strengths | Weaknesses |
|---|---|
| Iconic, high-margin core clog with 58% gross margins | HEYDUDE brand in multi-year decline, forced a $737M writedown |
| Double-digit international growth across China, India, Japan, Europe | Heavy reliance on a single hero product |
| Jibbitz charms drive repeat purchase and personalization | North America revenue shrinking, still the largest single market |
| Strong cash generation, roughly $700M operating cash flow in 2025 | Divisive brand perception limits some fashion segments |
| Disciplined capital returns, about 10% of shares bought back in 2025 | Tariff exposure squeezing gross margin |
| Opportunities | Threats |
|---|---|
| International set to pass North America in annual revenue in 2026 | Intense competition from Nike, adidas, Skechers, Birkenstock |
| Collaborations and cultural marketing (Post Malone, Balenciaga, Tim Hortons) | Fashion cycles can cool on a trend-driven product |
| Sandals, sneakers, and adjacencies beyond the clog | New and rising tariffs on imported footwear |
| Sustainability push via bio-based Croslite and 2030 carbon targets | Geopolitical shocks lifting freight and oil costs |
| A HEYDUDE turnaround if the cleanup works | Consumer pullback in a weaker economy |
Crocs by the Numbers
| Metric | FY2025 | Change vs 2024 |
|---|---|---|
| Consolidated revenue | $4.04 billion | down 1.5% |
| Crocs Brand revenue | $3.33 billion | up 1.5% |
| HEYDUDE Brand revenue | $715 million | down 13.3% |
| Gross margin | 58.3% | down 50 bps |
| Adjusted diluted EPS | $12.51 | reported |
| Operating cash flow | ~$700 million | reported |
| Shares repurchased | ~6.5 million ($577 million) | ~10% of float |
In Q1 2026, Crocs reported enterprise revenue of $921.5 million, down 1.7% but ahead of Wall Street estimates. Adjusted EPS of $2.99 beat forecasts, adjusted EBITDA margin held at 24.5%, and management raised full-year 2026 adjusted EPS guidance to a range of $13.20 to $13.75. The stock, a mid-cap trading around $128 in mid-2026 with a market value near $6 billion, has drawn a run of analyst upgrades on the back of that beat.
Crocs Strengths
Crocs turns an unusual product into durable financial performance. These are the advantages that keep the company relevant against much larger rivals.
A High-Margin Icon
The signature clog remains one of the most profitable everyday shoes in the market. Crocs held a 58.3% gross margin in 2025, a level most footwear makers never reach. The proprietary Croslite foam is cheap to mold, light to ship, and instantly recognizable, which lets Crocs price above a plain rubber sandal while spending little to make each pair. That margin funds the marketing, the collaborations, and the buybacks.
International Growth That Offsets a Soft Home Market
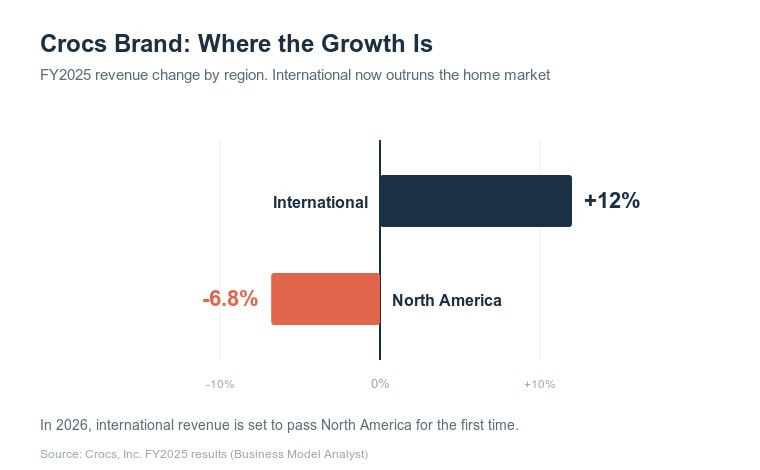
The Crocs Brand grew international revenue by nearly 12% in 2025 while North America slipped 6.8%. China, India, Japan, and Western Europe all posted gains, and Q1 2026 extended the pattern with 7% international growth for the brand. This geographic spread protects the company when any single market cools, and it hands management a growth engine that North America can no longer supply on its own.
Jibbitz and the Personalization Loop
The small Jibbitz charms that clip into clog holes look like a novelty. They work like a razor-and-blades engine. A shopper buys the shoe once, then returns for charms tied to a favorite team, film, or mood. Each charm carries a high margin and pulls the customer back to the brand. This personalization also gives Crocs a low-cost way to refresh the product for new audiences without redesigning the shoe.
Cash Generation and Shareholder Returns
Crocs produced roughly $700 million in operating cash flow in 2025 and used it with discipline. The company repurchased about 6.5 million shares for $577 million, close to 10% of shares outstanding, and paid down $128 million of debt. Buying back a tenth of the float in a single year lifts earnings per share and signals that management sees its own stock as undervalued. Few footwear brands convert cash this efficiently.
Marketing That Reaches Culture
Crocs sits in the conversation rather than shouting at it. The brand runs collaborations with musicians, luxury houses, and food chains, from Post Malone and Balenciaga to a 2026 Tim Hortons clog. It moved into short-form TikTok microdramas in mid-2026 to reach younger viewers where they already scroll. These moves keep an inexpensive shoe feeling like a cultural object, which supports both price and demand.
Crocs Weaknesses
The same focus that makes Crocs efficient also leaves it exposed. Three weaknesses stand out in the current numbers.
HEYDUDE Is Dragging the Whole Company
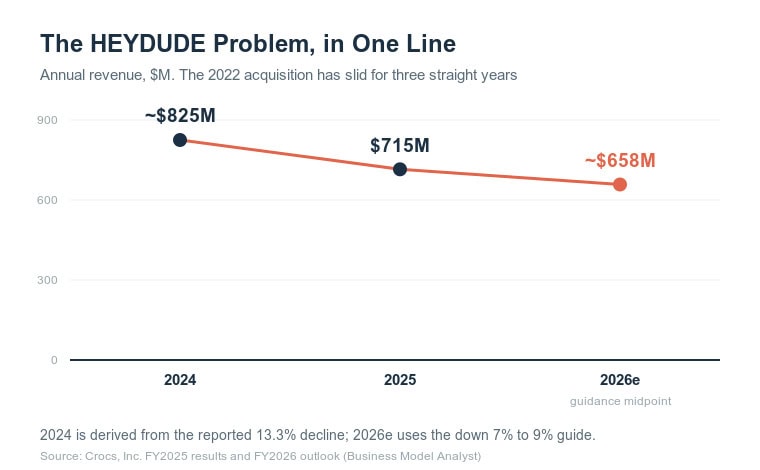
Crocs paid about $2.5 billion for HEYDUDE in 2022 to add a casual, canvas-style shoe to the portfolio. The bet has soured. HEYDUDE revenue fell 13.3% to $715 million in 2025, and the company recorded roughly $737 million in non-cash impairments against the brand’s trademark and goodwill during the year. Those charges crushed reported operating margin to 3.7%, down from nearly 25% the year before. Wholesale is the epicenter, with HEYDUDE wholesale down more than 40% in the fourth quarter as management cleaned up the channel.
Everything Rides on One Shoe
The Crocs Brand still leans on the classic clog. That concentration means a shift in taste hits the whole company at once. Management has pushed sandals, slides, and sneakers to broaden the base, but the clog remains the product people picture when they hear the name. A single hero product is efficient when the trend runs hot and dangerous when it cools.
The Home Market Keeps Shrinking
North America remains Crocs’ largest single market, yet it is the one going backward. Crocs Brand North America fell 6.8% in 2025 and kept declining into 2026. International strength covers the gap for now, but a business cannot lean on overseas growth forever while its home base erodes. Rebuilding North American demand, especially in wholesale, is the open question management has not yet answered.
A Look People Still Argue About
Crocs has converted a lot of skeptics, but the shoe still splits opinion. Some shoppers see comfort and self-expression. Others see something they would only wear in a garden. That divide caps how far Crocs can push into fashion-forward segments and leaves the brand exposed to mockery cycles on social media, where a single viral post can reshape perception fast.
Crocs Opportunities
Crocs has clear paths to grow, and most of them build on strengths the company already owns.
International Overtakes Home
Management expects international revenue to pass North America in annual sales for the first time in 2026. That milestone reframes Crocs as a global brand rather than a US brand with exports. India and Indonesia offer large, young, warm-weather populations well suited to a breathable clog. Direct ownership moves, such as taking over distribution in Malaysia, show the company investing behind the shift rather than waiting for it.
Collaborations as a Growth Lever
Each collaboration buys attention that would cost far more as paid media. Limited drops with designers, celebrities, and brands generate resale demand, social buzz, and a reason for existing fans to buy again. Crocs can keep widening the roster across sport, entertainment, and food to reach audiences it does not own yet, all while protecting the core product’s margins.
Beyond the Clog
Sandals and sneakers give Crocs room to sell more shoes to the same loyal customer. Building credible adjacencies, including performance and outdoor styles, would reduce the single-product risk and lift the average number of pairs each shopper owns. The personalization playbook that works for clogs can extend to these categories too.
Sustainability as Differentiation
Crocs has committed to bio-based Croslite and aims to cut the carbon footprint per pair by 50% by 2030 on the way to net zero. Younger buyers weigh a brand’s environmental record, and a credible, well-communicated program can turn a synthetic-foam shoe from a liability into a selling point. The opportunity is real only if the marketing matches the manufacturing.
The HEYDUDE Reset
HEYDUDE is a weakness today and an option for tomorrow. Management guides the brand to return to growth in the second half of 2026 after the wholesale cleanup. If new leadership stabilizes the brand at a smaller, cleaner base, HEYDUDE could shift from an earnings drag to a modest contributor, which would remove the biggest overhang on the stock.
Crocs Threats
External forces could stall Crocs even if the company executes well.
A Crowded, Aggressive Field
Crocs competes with Nike, adidas, Skechers, and a resurgent Birkenstock, alongside a long tail of low-cost lookalikes. These rivals spend heavily, innovate constantly, and chase the same casual and comfort dollars. The Nike business model and the adidas business model both fund marketing budgets Crocs cannot match dollar for dollar, so Crocs has to win on distinctiveness rather than scale.
Tariffs and Trade Policy
Crocs manufactures overseas and imports into its markets, which puts it directly in the path of rising footwear tariffs. Incremental duties already cost the company about 130 basis points of gross margin in 2025, and management withdrew its full-year outlook at one point in 2025 over trade uncertainty. Further tariff moves would hit margins or force price increases that test shopper loyalty.
Fashion Risk
A trend-driven product can fall out of favor as fast as it rose. Crocs has proven durable across several years, but the company still depends on the clog staying culturally relevant. A cooling of the broader comfort-footwear wave, or a simple shift in what feels current, would pressure the core faster than any new category could compensate.
Geopolitical and Cost Shocks
Management flagged the Middle East conflict as a real headwind in 2026, raising freight and oil-linked transport costs and pressuring distributor revenue in affected regions. High energy prices and government energy-control measures in parts of Europe and Southeast Asia add further uncertainty. A global supply chain that keeps margins high in calm periods becomes a liability when routes and inputs get expensive.
A Weaker Consumer
Crocs sells discretionary items. In a downturn, shoppers trade down or delay non-essential purchases, and footwear sits near the front of that list. A meaningful consumer pullback would hit unit volumes and push competitors into deeper discounting, squeezing the pricing power that underpins Crocs’ margins.
Frequently Asked Questions
Is Crocs profitable in 2026? Yes. On an adjusted basis Crocs remains highly profitable, with adjusted diluted EPS of $12.51 in 2025 and guidance of $13.20 to $13.75 for 2026. Reported 2025 operating margin looked weak at 3.7%, but that figure reflects one-time HEYDUDE impairment charges rather than the underlying business, which runs adjusted operating margins above 22%.
What are Crocs’ biggest strengths? A high-margin, instantly recognizable core clog, double-digit international growth, strong cash generation of roughly $700 million a year, and a personalization engine in Jibbitz charms that drives repeat purchases.
What is the biggest problem facing Crocs? HEYDUDE. The brand Crocs bought in 2022 has declined for multiple years, fell 13.3% in 2025, and triggered about $737 million in impairment charges. Fixing or stabilizing HEYDUDE is management’s central challenge.
Who owns Crocs? Crocs, Inc. is a publicly traded company listed on the Nasdaq under the ticker CROX. It is owned by its shareholders, with institutional investors holding the majority of the roughly 50 million shares outstanding.
Who are Crocs’ main competitors? Nike, adidas, Skechers, and Birkenstock are the largest direct rivals, along with numerous lower-cost brands that copy the clog silhouette.
The Business Model Analyst Take
Crocs in 2026 is a tale of two brands. The Crocs Brand is a rare thing in footwear, a high-margin product with a cult following and a genuine international runway, throwing off cash that management returns to shareholders with unusual discipline. HEYDUDE is the anchor tied to its ankle, a $2.5 billion acquisition now worth far less on the books and still shrinking.
The bull case is simple. If international growth keeps outrunning North American softness and HEYDUDE stabilizes at a smaller base, Crocs is a cash machine trading at a single-digit multiple of earnings. The bear case is just as clear. A trend-driven core, rising tariffs, and a home market that will not stop shrinking could cap the story right here.
The number that matters most in 2026 is not revenue growth, which management guides to roughly flat. It is whether the international business truly overtakes North America and whether HEYDUDE turns the corner in the second half. Get both, and the discount on the stock closes. Miss both, and Crocs stays exactly where the market has parked it, cheap for a reason. For a company built on a shoe people once laughed at, that is a far more serious position than its critics ever expected.