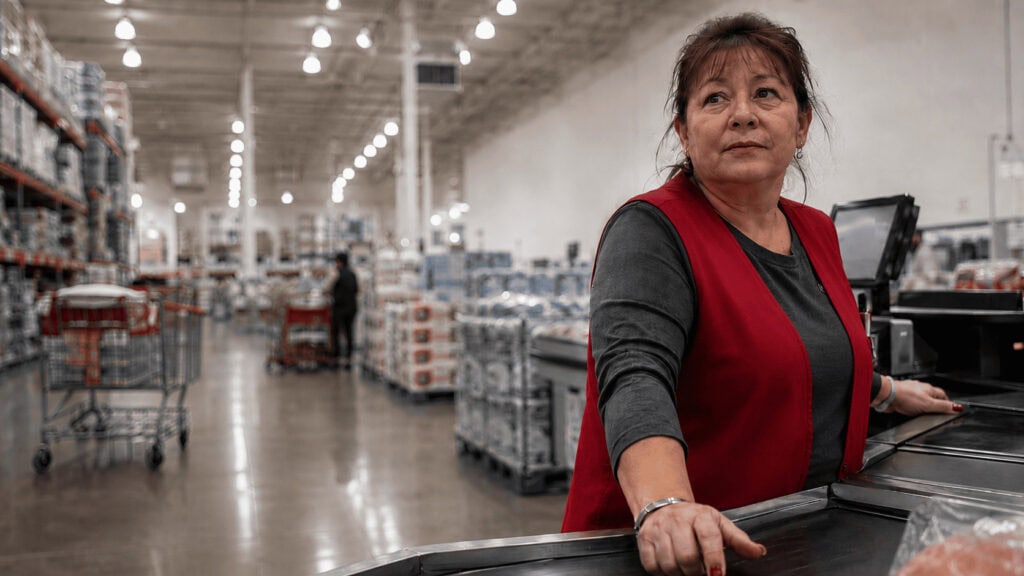

A 60-year-old cashier in Tucson has spent four decades at Costco, earns $32.90 an hour, and now has more than $1 million sitting in his 401(k). The Wall Street Journal framed it as a feel-good story about one loyal worker. For founders and operators, it is something more useful: a clean look at the flywheel that turned Costco from a discount warehouse into a company worth roughly $420 billion.
Tony Barzar is not an outlier Costco tolerates. He is the output of a strategy Costco has been compounding for 40 years, and the number that should catch your attention is not his net worth. It is his employer’s turnover rate.
The Quick Version
Costco deliberately pays hourly workers well above the retail average. That high pay drives turnover down to roughly 7 to 8 percent a year, against an industry average near 60 percent. Low turnover produces experienced staff, faster checkout, and better member service, which protects the membership renewal rate that is the actual profit engine. The wages are not a cost Costco reluctantly absorbs. They are the input that keeps the money machine running.
What Actually Happened
Barzar started at a Price Club store in 1986, gathering carts in the Tucson parking lot for $5.85 an hour. When Costco acquired Price Club in 1993, it converted the pension into a 401(k), and Barzar began quietly diverting part of each paycheck into it. Four decades of compounding, steady contributions, and a stock that has climbed more than 2,000 percent since the 2008 lows did the rest.
His pay today is $32.90 an hour, recently bumped from $31.90. His health plan carries a $15 co-pay for a standard visit. When his wife was diagnosed with stage 3 brain cancer, Costco’s insurance covered three brain surgeries in full, and he took nearly a year of paid leave. He has been offered a supervisor role more than once and turned it down. In his words, “Costco has been good to me.”
The human story is real. But Barzar is not rare inside Costco. The company’s own CFO says many thousands of its US hourly workers are also 401(k) millionaires. When a millionaire cashier is a category rather than an anecdote, you are looking at a system, not luck.
The Efficiency-Wage Flywheel
Economists have a name for what Costco is doing: efficiency wages. The idea is that paying above the market clearing rate can pay for itself through higher motivation and lower turnover. Most retailers treat it as a nice theory. Costco treats it as an operating manual.
Here is the loop, stage by stage:
- Pay meaningfully above retail average.
- Turnover collapses to 7 to 8 percent, versus roughly 60 percent industry-wide.
- Fewer departures mean lower recruiting, onboarding, and training costs.
- Staff get more experienced. Fast cashiers ring up around 70 shoppers an hour against a 57 average.
- Faster lines and friendlier, more knowledgeable service improve the member experience.
- Happier members renew. Costco’s renewal rate sits near 90 percent, and around 93 percent in the US and Canada.
- Renewal fees, not merchandise margin, generate most of the operating profit.
- That profit funds the next round of raises, and the loop tightens.
The critical move most analyses miss is step 7. Costco sells merchandise at near break-even and earns its profit from membership fees. So the cashier is not a cost center attached to a low-margin product. The cashier is a guardian of the renewal rate, which is the margin. Paying that person well is not generosity. It is protecting the one number the entire model depends on.
The Turnover Math Nobody Runs
Retailers obsess over hourly wage as a line item because it is easy to see on a P&L. The cost of turnover is harder to see, so it gets ignored. That is the trap.
McKinsey estimated that losing a single front-line retail employee costs roughly $10,000 in recruiting, training, and lost productivity. Run that against the industry’s 60 percent annual churn and the “savings” from paying people less evaporate. A retailer with 100,000 hourly workers and 60 percent turnover is replacing 60,000 people a year. At $10,000 each, that is a $600 million annual bill that rarely gets attributed to the low-wage decision that caused it.
Costco’s roughly 341,000 employees and single-digit turnover mean it pays that replacement tax on a fraction of its workforce. The same McKinsey work found retailers in the top quartile of employee satisfaction were more than twice as likely to land in the top quartile of customer satisfaction. Happy workers are not a soft benefit. They are a leading indicator of the customer metrics that drive revenue.
Why Cheap Labor Is Expensive
The wage gap between Costco and the rest of retail is not subtle. It reframes the whole “labor cost” conversation.
| Retailer | Hourly pay range | Reported average | Approx. annual turnover |
|---|---|---|---|
| Costco | $19.50 floor, $32.90 top | High $25s | 7 to 8% |
| Amazon (fulfillment) | Varies | Over $22 | High |
| Target | $15 to $24 | Around $18.50 | Industry-level |
| Walmart | $14 to $19 | Over $17.50 | Industry-level |
| Kroger | Varies | Around $16 | Industry-level |
Costco’s pay floor sits several dollars above where competitors’ ranges start, and more than half of its hourly workforce has already reached the top of the scale. The competitors are not paying badly by historical standards. They are simply playing a different game, optimizing the visible wage line while eating an invisible turnover bill.
The Tension Costco Will Not Fully Solve
This is the part the feel-good framing skips, and it is the most instructive piece for operators. Costco’s compensation is generous enough to create a problem: some workers save so much that they retire earlier than the company would like. When a long-tenured employee leaves, the store’s average wage drops, which nudges short-term profit up. But it comes at the expense of experience and, as one Tucson manager put it, dilutes the culture that makes the model work in the first place.
So Costco faces a permanent trade-off. It can let tenured, expensive workers cycle out to lift near-term margin, or it can keep paying to retain the experience that protects the renewal rate. It has consistently chosen experience over the quarterly number, adding a “culture coach” role for veterans, an extra week of vacation for 30-year employees, and higher bonuses. That is the discipline behind the strategy. Anyone can announce a raise. The hard part is defending it when the finance team shows you how much cheaper churn looks on this quarter’s statement.
What Founders and Operators Should Steal
You do not need warehouses to use the underlying logic. Four transferable moves:
Track the cost of losing people, not just the cost of paying them. If you cannot put a dollar figure on replacing a key role, you are almost certainly underpaying to retain it and overpaying to churn through it.
Find the number your business actually monetizes, then protect it upstream. For Costco it is the renewal rate, and the cashier protects it. For a SaaS company it might be net revenue retention, which your support and onboarding staff protect. Pay the people closest to that number like they matter, because they do.
Treat retention as a compounding asset. Barzar’s value is not that he is cheap. It is that 40 years of tenure make him faster, calmer, and a mentor to newer staff. Experience compounds only if people stay long enough to accumulate it.
Be willing to look worse this quarter. The efficiency-wage flywheel only works if you defend the wage when cutting it would flatter the near-term P&L. That is a leadership decision, not a spreadsheet one.
Where This Could Break
Strong models deserve honest stress tests, so here is the case against copying Costco wholesale.
The membership model does the heavy lifting. Costco can afford to pay cashiers well because renewal fees, not product margin, are the profit. A thin-margin retailer without a recurring revenue layer has far less room to run the same play, and importing the wages without importing the membership economics could simply raise costs.
Low turnover is partly a labor-market artifact. Retention looks heroic in a loose labor market and gets tested when workers have more outside options. Costco’s numbers held through tight and loose cycles, which is a point in its favor, but the flywheel is easier to sustain when the whole sector is not bidding for the same people.
Automation shifts the terms. Costco leans on human cashiers even in self-checkout, where a worker like Barzar circulates to keep lines moving. As retailers push further into automated checkout and AI-assisted operations, the marginal value of a veteran cashier could compress, and the wage-for-experience trade changes shape.
Scale and capital hide the difficulty. Costco reached this equilibrium over four decades with an expanding store base and a rising stock funding the 401(k) gains. A younger company cannot promise the compounding that made Barzar a millionaire, so the retention pitch is weaker until the flywheel has spun for years.
None of this breaks the core insight. It just means the lesson is “understand what your labor actually protects and price accordingly,” not “pay everyone more and wait for magic.”
The Business Model Analyst Take
The millionaire cashier is not a heartwarming exception to Costco’s strategy. He is the strategy, made visible. Costco figured out something most retailers still refuse to believe: in a business where your profit comes from people renewing rather than from squeezing product margin, the front-line worker is not the cost to minimize. They are the asset that defends the only number that matters.
The competitors optimizing the visible wage line while absorbing a hidden turnover bill are not being frugal. They are being fooled by their own P&L, which shows them what wages cost and hides what churn costs. Costco’s edge is not that it is nicer. It is that it does the full arithmetic, prices experience correctly, and then holds the line when the short-term math tempts it to cut. Most companies do the first part occasionally. Almost none do the third part consistently. That gap, sustained across 40 years, is the moat. Tony Barzar’s 401(k) is just the receipt.