
Retailers are becoming ground-floor tenants in subsidized apartment projects, getting scarce urban land for almost nothing. The catch is that this only works if you make your money the way Costco does.
Costco has signed on as the ground-floor tenant of a roughly $450 million residential project in Los Angeles with 800 apartments, including affordable and workforce housing. It is the first U.S. residential development with a Costco. The retailer is not paying to build it. That is the entire point.
There is a version of this story where big-box retail finally learned to love the city. It is a nice story. It is also mostly wrong. What is actually happening is a land-acquisition arbitrage, and it works spectacularly for exactly one kind of business model.
What Happened
In the Baldwin Village neighborhood of Los Angeles, developer Thrive Living is building an approximately $450 million residential project with 800 apartments that mixes affordable and workforce housing. Costco will occupy the ground floor. It is scheduled to open in 2028, and it will be the first residential development in the United States with a Costco inside it.
Costco also signed on for a 162,000-square-foot warehouse inside VIVA White Oak, a 280-acre project in Montgomery County, Maryland, where county rules require 12.5 percent of new residential construction to be affordable. Construction starts this year. The developer, MCB Real Estate, says it will be the first multifamily construction in that part of the county in 40 years, and that the project would have gone ahead without Costco, but Costco’s name pulled in other tenants. As MCB co-founder P. David Bramble put it, “Everyone wants to dance with Costco.”
Target is in the story too. Its 2024 Harlem store opened inside a complex with 171 affordable housing units, including 51 apartments for young people aging out of foster care. Target now has 16 Manhattan locations, up from one in 2015.
The mechanism is the same everywhere. States and cities, including California, Florida, Massachusetts, and Philadelphia, have rolled out incentives and financing to get housing built. The retailers are riding that subsidy wave into land they could never have bought outright.
The Backstory
The big-box model was never really a retail model. It was a real estate model with merchandise attached. Cheap land on the edge of town, a building that costs almost nothing per square foot, and an ocean of free parking. Volume did the rest.
That model has been quietly dying in cities for a decade, and not because shoppers stopped wanting cheap paper towels. It died because the land math stopped working. Urban parcels large enough for a warehouse and a parking field either do not exist or cost more than the store will ever earn on them. Meanwhile construction material prices jumped 50 percent between March 2020 and March 2026, according to federal price data, which means the cost of building anything at all went up while the returns did not.
So the retailers waited. And while they waited, the housing crisis handed them a key.
The Plan
Here is the structure, stripped of the community-benefit language.
The developer needs an anchor tenant. Not for rent, exactly, but for financing. A creditworthy national tenant on the ground floor de-risks the capital stack, lowers the cost of debt, and raises what the residential units above can charge. A Costco downstairs is an amenity that gets written into the leasing brochure.
The retailer needs land it cannot buy. So it contributes the one asset it has in surplus: its brand and its balance sheet. It signs a lease. It puts up little or no upfront capital. The developer eats the construction cost, the entitlement fight, and the risk.
Then the public sector shows up with the subsidy that makes the housing pencil in the first place. Tax breaks, zoning changes, state financing. In Harlem, the $242 million complex that houses Target drew more than $20 million from Empire State Development.
Read that back slowly. A housing subsidy program, designed to get affordable units built, is functioning as a land-acquisition vehicle for two of the largest retailers in America. Nobody planned it that way. It works anyway.
The Business Model Angle
Now the part that the trend framing misses.
This structure is not equally attractive to all big-box retailers. It is wildly attractive to one specific kind, and the reason sits inside Costco’s income statement.
In fiscal 2025, Costco reported $10.38 billion in operating income on $269.9 billion of net sales. Of that operating income, $5.32 billion came from membership fees. That is 51 percent of the company’s operating profit generated by a recurring fee that costs almost nothing to service. Merchandise, the thing customers think they are buying, delivered the other half on a gross margin of 11.1 percent.
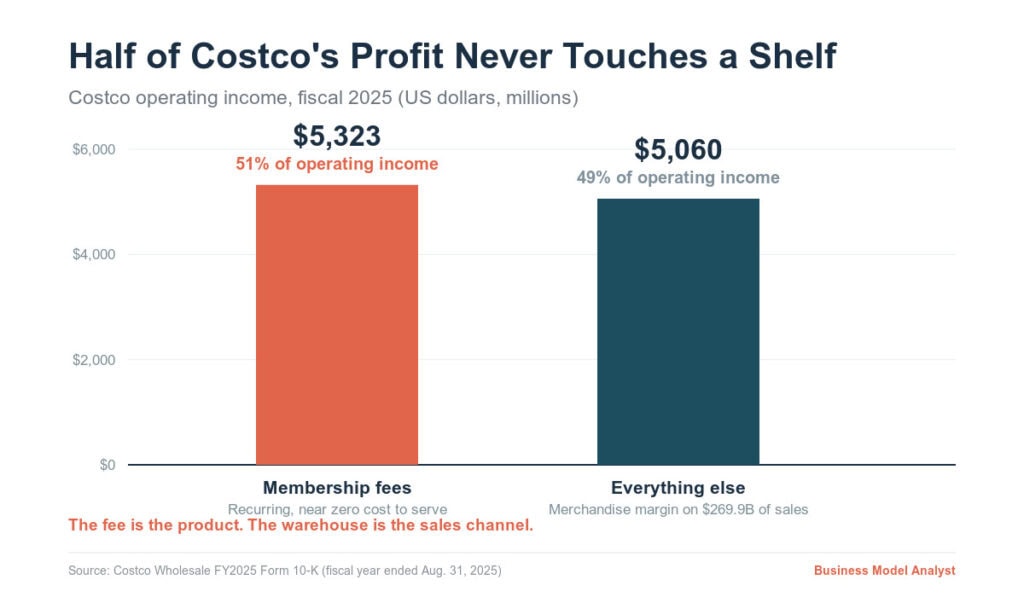
Sit with what that means for an urban store. Costco does not need a dense city warehouse to be a productive seller of merchandise per square foot. It needs it to be a productive acquirer and retainer of members. A store wedged under 800 apartments in Los Angeles, surrounded by exactly the density that a suburban warehouse never sees, is a membership acquisition machine that happens to also sell rotisserie chickens. Renewal rates run above 90 percent. Once someone signs up, the fee compounds annually whether or not they ever hit a great basket size.
That is why Costco can accept the compromises of urban mixed-use, which are real: no ground-level parking field, interior loading docks, noise abatement, separate entrances, fire-safety systems designed around residents sleeping upstairs. Those compromises hurt merchandise productivity. They do not hurt membership revenue.
Now look at Target. Its profit comes from merchandise margin, private label, and its Roundel retail media network, all of which scale with sales volume and assortment breadth. Square footage productivity is the whole game. And in March 2026, Target announced more than 30 new stores in 2026 and over 300 by 2035, most of them full-size, with a flagship new format running around 148,000 square feet, funded from a $5 billion capital plan. Its COO has said the returns on the small urban boxes are fine, but the big boxes are where returns are strongest.
So the honest read is not “big-box retailers discovered cities.” It is: a membership business can afford to be a bad tenant of its own square footage, and a merchandise business cannot. Target is in the Harlem building. Target is not betting the company on it.
The Risk
Three of them, in ascending order of how badly they could bite.
The retailer has no skin in the game. Costco is contributing a signature, not capital. That is the beauty of the deal and also its fragility. Ground-floor retail in mixed-use developments has a long, unglamorous history of sitting dark. A lease is not a commitment to operate well.
The subsidy is the load-bearing wall. Strip out the tax abatements, the state financing, and the inclusionary zoning that makes these projects viable, and the deals stop. That subsidy stack is a political variable, not a structural one. A single budget cycle can turn the pipeline off.
Somebody is going to write the other story. Right now the framing is community benefit: the Empowerment Congress West Area Neighborhood Development Council backed Costco’s LA alcohol permit on the grounds that the store would serve residents. That goodwill holds until a journalist or a city councilor runs the arithmetic and asks why public housing money is de-risking corporate land banking. The counterargument is decent, because a grocery anchor in an underserved neighborhood is a genuinely good thing. But the headline writes itself, and reputational risk is asymmetric.
Quick Questions
Is Costco actually opening stores inside apartment buildings? Yes. The Los Angeles project in Baldwin Village will place a Costco on the ground floor of a roughly $450 million, 800-unit residential development that includes affordable and workforce housing. It is scheduled to open in 2028 and is the first of its kind in the United States.
Why would a developer want a big-box store in a housing project? Because a national retail anchor lowers the cost of financing, attracts other tenants, and lets the developer charge higher residential rents. The retailer’s brand functions as a credit enhancement.
Does this mean big-box retail is going urban across the board? No. Target announced in March 2026 that it is focusing new growth on full-size stores of roughly 148,000 square feet, with more than 300 openings planned by 2035. Urban mixed-use is opportunistic for most retailers and structurally attractive for very few.
Why does the model work so well for Costco specifically? Because roughly half of Costco’s operating profit comes from membership fees rather than merchandise margin. Dense urban locations are excellent at signing up and retaining members even when they are mediocre at moving pallets, which is a trade Costco can afford and a merchandise-margin retailer cannot.
What is the biggest thing that could stop this? The subsidies. These projects pencil because of state and municipal incentives, tax breaks, and inclusionary zoning. Change the policy and the deal structure loses its foundation.
The Business Model Analyst Take
The lesson here is not about retail real estate. It is about what your revenue model permits you to tolerate.
Costco can walk into the most expensive, most constrained, most politically complicated real estate in America and accept terms that would be unacceptable to a normal retailer, because the thing it actually sells is not on the shelves. It is a $65 annual fee with a 90 percent renewal rate. Everything in the warehouse is a customer acquisition cost dressed up as inventory. When your profit engine is recurring and your storefront is just a channel, you get to be flexible about the storefront in ways your competitors cannot imitate.
That is the transferable insight for operators, and it has nothing to do with warehouses. Look at what your monetization model lets you say yes to that your competitors have to refuse. Costco can say yes to a weird building with no parking under 800 apartments. Target has to run the square-footage math and mostly say no. Same industry, same city, same subsidy, completely different answer.
The strategy is downstream of the business model. It always was. This story just makes it visible.
Reporting from The New York Times, “Big-Box Retailers Have a New Strategy for Breaking Into Urban Markets” by Lauren Coleman-Lochner, July 12, 2026. Financial data from Costco Wholesale’s FY2025 Form 10-K and Target Corporation’s March 2026 store investment announcement.