
Nick Fink gave his first interview as Constellation Brands chief executive on the same morning the company held its Q1 earnings call, and his message was built entirely around one idea: win the occasion, not the category. The maker of Modelo, Corona, and Pacifico is leaning on the World Cup, a Knicks title run, and a rethink of pack sizes to pull a stalling beer business through its most important selling season. Here is what he is actually betting on, and whether the numbers back it.
The pool-cooler theory of competition
Fink, who took over from Bill Newlands in April, frames Constellation’s competitive set in a way most CPG executives do not say out loud. His rivals are not just other brewers. They are whatever else ends up in the cooler at a given moment. Poolside on a hot afternoon, the competition is the seltzer, the canned cocktail, and the soda sitting next to his beer, and the job is to decide which of those occasions to win rather than trying to win all of them.
That is a sharper strategic filter than it sounds. It reframes the entire portfolio question around demand moments instead of shelf adjacencies, and it gives the company permission to concede occasions it cannot win profitably. For a business under volume pressure, choosing where to compete is often more valuable than fighting everywhere.
The summer selling season is where this theory gets tested, and Fink’s first one is arriving with unusual tailwinds. The 2026 World Cup is running across the United States, Mexico, and Canada, stacking exactly the kind of social, watch-together drinking occasions beer is built for. Add a New York sports moment and warm weather, and you get younger adults gathering in groups again, relearning the post-Covid habit of socializing in person. Beer is riding along with that behavior, and it is doing so partly on price. A beer runs less than half the cost of a cocktail at a bar, which matters more than usual in a stretched consumer environment.
The K-shaped consumer is the real story
Ask Fink what is happening to spending and he does not pretend the picture is uniform. The K-shaped economy that dominated the last two years is still very much in play. Some consumers keep spending where they perceive value. Others are hunting hard for it. The split is not academic for Constellation, because its core Hispanic consumer sits closer to the pressured side of that K, and gas prices are a real swing factor.
The geographic pattern he describes is telling. Markets more exposed to fuel costs, like Texas and Florida, saw more pullback. A market like New York, where public transit softens the gas-price hit, held up better. That is a useful reminder for any operator selling to value-sensitive customers: the same national brand can be experiencing two completely different demand curves depending on the local cost structure your buyer lives inside.
Premium beer actually performed well early in the quarter before affordability bit, then recovered as pressure eased. The takeaway is that trading down is not permanent here. It is a reflex that switches on and off with the consumer’s sense of headroom, which is exactly why Fink is building flexibility into the pack lineup rather than repricing the brands.
GLP-1s and the pony bottle
The more structurally interesting thread is how Constellation is treating GLP-1 drugs. Fink’s stance is that ignoring a technology-driven behavior shift would be a mistake, even though the current data does not show a dramatic hit to beer. The honest version is that consumption habits could still change, and the company’s edge will come from how quickly it adapts rather than whether it can predict the exact impact.
The product response is concrete. Constellation is pushing large single-serve containers meant to be shared, aimed at affordability-minded buyers, alongside smaller “pony” bottles pitched at people on GLP-1 medications who want less volume and lower alcohol per sitting. There is even an emerging consumer story that some GLP-1 users are drinking more beer, not less, because they have become less tolerant of high-ABV spirits. Whether that holds is unproven, but the packaging bet costs little to run and hedges a real long-term risk.
This is worth watching because the GLP-1 threat has been priced far more aggressively into sugary categories than into beer. The same appetite-suppression research that has Coca-Cola reworking its portfolio toward zero-sugar and smaller formats is the backdrop here, and beer has largely been treated as insulated. Fink is quietly refusing to assume that, which is the right posture even if the data stays benign for now.
Do the numbers back the optimism?
Constellation’s Q1 fiscal 2027 print, released the same day, gives the strategy a mixed but defensible foundation.
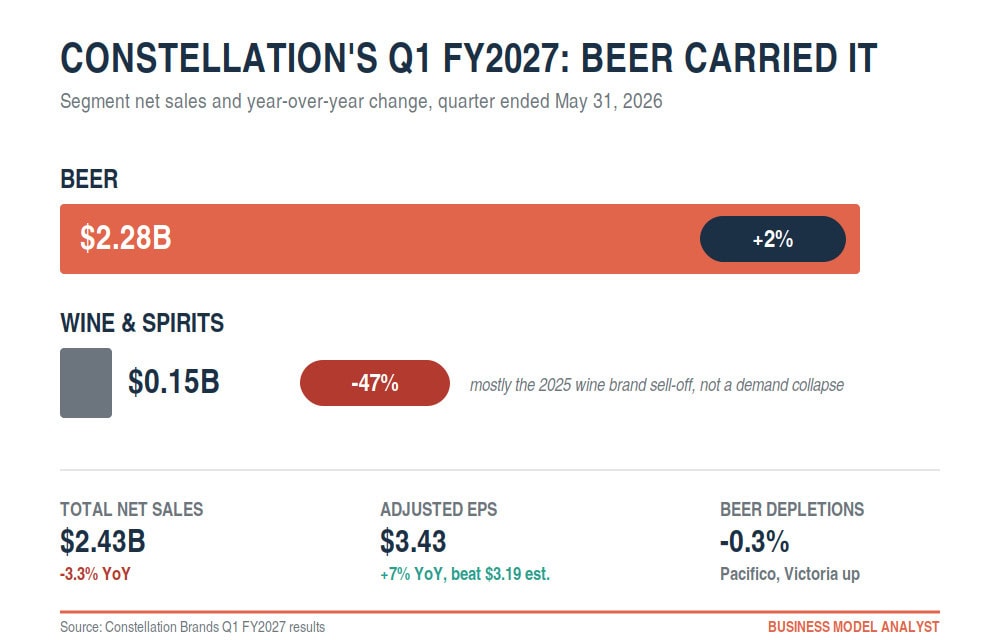
Total net sales fell 3.3% to $2.43 billion, but the composition matters more than the headline. Beer revenue rose 2% to $2.28 billion on pricing and shipment gains, and adjusted earnings came in at $3.43 per share, comfortably ahead of the roughly $3.19 analysts expected and up about 7% year over year. The alarming-looking 47% drop in wine and spirits, down to $149 million, is mostly an artifact of the 2025 wine brand divestitures rather than a demand collapse, which is exactly the kind of number that spooks a casual reader and rewards a careful one.
The softer signal is depletions, the measure of how much distributors actually sell through to retailers. That slipped 0.3%, with Modelo Especial and Corona Extra soft and Pacifico, Victoria, and Modelo Chelada picking up the slack. In other words, the flagship brands are cooling while the portfolio’s supporting cast grows, which is precisely why Fink’s occasion-and-flexibility framing is more than PR. It is a response to a real mix shift already underway.
Markets were not fully convinced. The stock slid on the report even with the EPS beat, and the broader brewer group fell alongside it, leaving Constellation with a market value near $23 billion and a valuation multiple that already reflects a lot of skepticism about the beer category’s growth.
Frequently Asked Questions
Who is Nick Fink and when did he become Constellation Brands CEO?
Nick Fink is the chief executive of Constellation Brands, the maker of Modelo, Corona, and Pacifico. He took over from Bill Newlands in April 2026 after sitting on the company’s board since 2021, and previously ran Fortune Brands Innovations and held senior roles at Suntory Global Spirits.
What did Constellation Brands report in Q1 fiscal 2027?
Net sales fell 3.3% to $2.43 billion, but adjusted earnings of $3.43 per share beat the roughly $3.19 analysts expected and rose about 7% year over year. Beer revenue grew 2% to $2.28 billion, while wine and spirits fell 47% to $149 million, mostly because of the 2025 wine brand divestitures.
How is the 2026 World Cup helping beer sales?
The tournament stacks the kind of social, watch-together drinking occasions beer is built for, right in the middle of the crucial summer selling season. Fink is treating those occasions as a demand tailwind, though the boost is tied to a calendar event rather than a lasting shift in habits.
What impact are GLP-1 drugs having on beer?
Constellation says current data does not show a dramatic hit, but it is not assuming beer is immune. Its response is packaging: smaller “pony” bottles for people on GLP-1 medications and large single-serve share packs for value-focused buyers. Some GLP-1 users may even be shifting toward beer because they tolerate high-alcohol spirits less, though that trend is unproven.
What is the K-shaped economy and why does it matter to Constellation?
A K-shaped economy is one where some consumers keep spending freely while others pull back hard. It matters because Constellation’s core Hispanic consumer sits closer to the pressured side, and demand swings with local factors like gas prices, which hit markets such as Texas and Florida harder than a transit-heavy market like New York.
Why did Constellation’s stock fall even though earnings beat estimates?
The market focused on softening demand signals rather than the EPS beat. Beer depletions slipped 0.3%, with flagship brands Modelo Especial and Corona Extra cooling, and the whole brewer group fell that day. That left Constellation valued near $23 billion at a multiple that already prices in real skepticism about beer category growth.
The Business Model Analyst Take
Fink is running a genuinely coherent playbook: stop defending the whole category, pick the occasions beer can win, and use packaging rather than price cuts to meet a K-shaped consumer where they actually are. The occasion-first framing is the strongest part, because it turns a demand problem into a targeting problem the company can act on.
The risk he is underplaying is that his two biggest tailwinds this summer, the World Cup and a sports-driven social moment, are calendar events, not a trend. Occasions you do not own are borrowed demand. When the tournament ends in July and the weather turns, the structural questions come straight back: depletions in the flagship brands are drifting down, the Hispanic core is stretched, and GLP-1s remain a slow-burn unknown. Pony bottles and share packs are smart, cheap hedges, but they are hedges, not a growth engine.
The tell for operators watching this is simple. If beer depletions are still negative after the World Cup bump washes out, the occasion strategy was a clever way to manage a decline, not reverse it. If they turn positive, Fink will have proven that in a fragmented market, choosing your battles beats fighting the whole cooler. Right now the evidence points to competent decline management with real optionality attached, which is a reasonable place for a new CEO to start, and not yet the turnaround the summer headlines imply.