
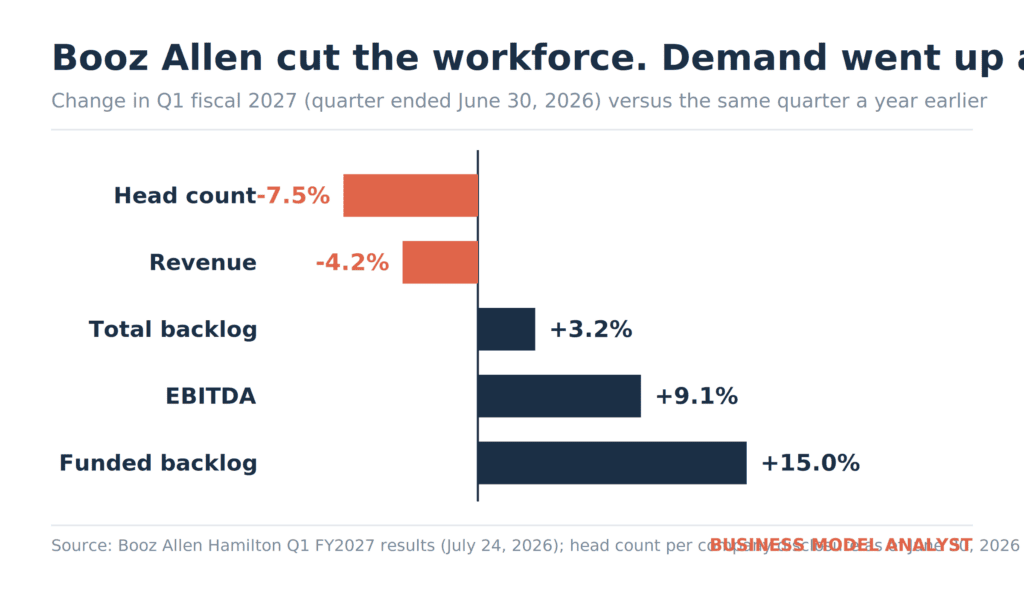
Revenue fell 4.2%. Funded backlog rose 15%. The missing variable is the roughly 2,500 people who left, and the whole AI substitution trade is now unwinding in public.
Booz Allen Hamilton’s chief operating officer told investors on Friday that the firm needs to speed up hiring and is running behind. That is a strange thing to say eighteen months into an era when the standard corporate script called artificial intelligence a reason to stop hiring altogether.
The Wall Street Journal put Booz Allen at the front of a broader story: CSX, Snap-on, Alphabet, and ServiceNow all told investors in the past two weeks that they plan to add people. Jobless claims fell to 187,000 in the week ended July 18, the lowest reading since 1969. Robert Half’s chief executive said AI’s effect on the job market looks milder than the forecasts implied.
The reversal is real. The interesting part sits one level down, in how these companies accounted for the workers they let go.
The Quarter That Gives the Game Away
Booz Allen reported first quarter fiscal 2027 results on July 24. Revenue came in at $2.8 billion, down 4.2% from a year earlier. The company’s own filing names the cause: slowed procurement reduced head count and billable expenses.
Read that sentence twice. Revenue fell because head count fell. For a firm that bills client hours, those are the same number wearing different clothes.
Now look at what improved in the same quarter. EBITDA rose to $324 million from $297 million. Adjusted EBITDA margin hit 11.9%, up 130 basis points year over year. Adjusted diluted EPS climbed 22% to $1.81. Funded backlog jumped 15% to $4.7 billion, total backlog passed $39 billion, and book-to-bill hit 1.5x for the quarter.
Total head count sat near 30,900 as of June 30, down 7.5% from a year earlier. Call it 2,500 people gone.
A firm that sells hours shrank its capacity into a demand upturn. Margins looked better on the way down because the denominator shrank faster than the overhead. Demand kept climbing anyway. Now management has to buy the capacity back, and the specific capacity it needs is cleared national security personnel, which takes months of background investigation before anyone bills a single hour.
Substitutes Shrink Your Cost Base. Complements Expand It.
Two years of corporate messaging treated AI as a substitute for labor. Fire the analysts, buy the model, keep the difference. Under that assumption, AI adoption should show up as a permanently smaller payroll and a permanently fatter margin.
A complement works the opposite way. Buy the model, then hire people who can operate it, audit it, sell against it, and clean up after it. Payroll holds or grows, and the compute bill lands on top.
Sarah Franklin, who runs the HR platform Lattice, described the recalibration to the Journal: companies stopped hiring junior staff on the theory that agents would cover the work, then found they needed humans working alongside the agents. Coding agents did not remove the need for engineers. AI sales agents did not remove the need for salespeople.
The financial consequence is direct. Under the substitute story, an S&P company books a cost reduction. Under the complement story, it books a cost addition and hopes revenue per employee rises enough to cover it. Those two stories carry different multiples.
Head Count Is Inventory, Not Overhead
Accounting rules put salaries in the expense column, which trains executives to treat people as a cost to be minimized. That framing works for a software company with 4,000 engineers serving 200 million users. It falls apart at a firm where billable staff are the product.
For Booz Allen, Accenture, Robert Half, and the rest of the labor-leveraged services world, staff function as inventory. You carry it, you finance it, and you sell it by the hour. The Accenture business model runs on exactly this mechanic: capability priced in billable time, with utilization as the margin lever.
Retailers already learned what happens when you run inventory to zero during a soft patch and demand returns. The restock costs more, arrives late, and you lose the orders you could not fill. Booz Allen has a $39 billion backlog and a security clearance queue standing between it and the revenue.
That is the bullwhip effect applied to human capital, and 2026 delivered a textbook version of it.
The Data Cuts Both Ways, Which Is the Honest Part
Skeptics have a case here, and it deserves a hearing rather than a wave.
Challenger, Gray & Christmas recorded 139,156 job cuts in the first half of 2026 with AI as the leading stated reason, and AI held the top spot for four straight months. Revelio Labs found entry-level postings down 35% since January 2023. Roughly 51% of hiring managers rated the market for new graduates as poor or fair, the weakest reading since 2020. Those numbers are not noise.
Set against them: a Ramp and Revelio Labs study covering 21,559 US companies found that the heaviest AI spenders grew head count 10.2% in the two years after adoption, with entry-level roles up 12%. Correlation, not causation, and the authors say so. It still runs directly against the replacement thesis.
Both patterns can hold at once. Firms cut first on the substitute assumption, discovered the complement reality, and are now restocking. The cuts were real. The permanence was the error.
Everyone Quoted Has a Book
Treat the sourcing on this story with the skepticism it earns.
Robert Half’s chief executive sells staffing services, so a benign AI narrative is his product pitch. Lattice sells HR software priced per employee, so more employees means more revenue. Booz Allen’s COO wants investors to believe the revenue decline is temporary and fixable. Every voice pushing the “AI won’t take your job” line in this news cycle profits from you believing it.
The counterweight comes from the filings. Booz Allen’s 8-K attributing revenue decline to reduced head count is an audited disclosure, not a talking point. The Labor Department’s claims data is not selling anything. Weight those above the executive commentary.
The Cost Stack Nobody Nets Out
Anyone holding these names at current multiples should sit with the next paragraph.
The same quarter that produced the hiring reversal also produced record capital spending. Alphabet spent $44.9 billion on capex in Q2 alone, more than double a year earlier, raised full-year guidance to $195 to $205 billion, and posted negative free cash flow of $5.9 billion. We covered that unwind in detail in Google’s cloud backlog and the capex problem underneath it.
Alphabet CFO Anat Ashkenazi also said the company will keep hiring in AI and cloud. Both things at once: record infrastructure spending and expanding payroll, at a company whose advertising machine was supposed to be the most automatable revenue model in the S&P 500.
Across the four largest hyperscalers, planned 2026 capex sits near $725 billion against roughly $410 billion in 2025. If those companies had genuinely substituted compute for labor, the payroll line would fall to help fund the compute line. It is not falling.
What This Changes for Operators
Three practical consequences follow from a complement model rather than a substitute model.
Unit economics shift from cost per employee to revenue per employee. If AI raises output per head, the payoff arrives as growth on a stable cost base, which is a slower and less exciting story than a headcount cut and takes longer to show up in a quarterly print.
Entry-level pipelines become a strategic asset again. Franklin’s point about junior staff being cheaper and more fluent with new tools is a hiring argument dressed as a cultural one. Firms that froze graduate intake in 2025 now face a two-year gap in the layer that feeds mid-level supply.
Clearance, licensing, and certification turn into moats. Booz Allen cannot hire its way out of this quarter because the people it needs must pass federal background checks first. Any business whose staff require regulated credentials should treat head count reductions as much harder to reverse than a standard hiring freeze.
What to Watch Next
Amazon reports on July 30 and will update its roughly $200 billion capex plan. Watch whether the companies now guiding toward higher hiring also guide toward flat or lower operating expense growth, because they cannot deliver both.
For the services firms, the number that matters is utilization against backlog conversion. Booz Allen guided to fiscal 2027 revenue of $11.2 billion to $11.7 billion, which spans zero to 4% growth. Hitting the top of that range requires staffing up fast enough to convert a $39 billion backlog. Missing it will look like a demand problem in the headlines and read as a capacity problem in the filings.
The Business Model Analyst Take
The 2025 corporate consensus valued AI as a substitute for labor and repriced margins accordingly. Q2 2026 earnings season is the first broad evidence that it behaves as a complement, and complements do not cut your cost base.
Booz Allen is the cleanest proof because its business model removes the ambiguity. When you sell hours, cutting staff cuts revenue on a one-for-one basis, and the margin improvement you book on the way down is a drawdown, not an efficiency gain. Software companies get to hide the same dynamic inside gross margin for a few more quarters.
The trade to watch is not whether companies hire again. They will. The trade is whether revenue per employee rises enough to justify a compute bill that keeps climbing while payroll stops falling. Nobody has shown that math yet, and the companies spending $725 billion this year are asking investors to assume it.
Paul Osterman at MIT gave the Journal the most honest line in the whole story when asked whether firms need more people or fewer: nobody knows. Price the stocks accordingly.