
The limit on the declarations page is the least important number on a CGL policy. Here is what a business is actually buying.
Almost every American business that signs a lease, bids a job, or ships a product carries commercial general liability insurance. Most owners can recite the limit they bought, usually $1 million per occurrence and $2 million aggregate, and almost none can explain why that number has not moved in forty years.
That is the interesting part. The $1M/$2M convention is a fossil. It was set by the 1986 ISO form that introduced the general aggregate limit, and the market has quoted it ever since while the value of a dollar, the size of a jury award, and the perimeter of the policy itself have all moved a very long way.
Which raises the question this article is built around: if the limit has been quietly hollowed out, what is the premium actually paying for?
Commercial general liability (CGL) insurance is a third-party liability policy that responds when a business is legally obligated to pay damages for bodily injury, property damage, or personal and advertising injury caused to someone outside the business. In the United States it is written almost universally on the ISO CG 00 01 occurrence form, currently the 04 13 edition. The policy does three separate jobs: it indemnifies covered damages up to a stated limit, it obligates the insurer to defend the business against covered suits with defense costs paid outside that limit, and it serves as the instrument through which customers, landlords, and general contractors are added as additional insureds so the business can be hired at all.
At a glance
| Standard form | ISO CG 00 01, occurrence basis (claims-made version is CG 00 02) |
| Current edition | 04 13 |
| Coverage A | Bodily injury and property damage |
| Coverage B | Personal and advertising injury |
| Coverage C | Medical payments, no-fault, small sublimit |
| Typical limits | $1M per occurrence, $2M general aggregate, $2M products-completed operations aggregate |
| Defense costs | Paid as supplementary payments, in addition to the limits |
| Median small-business premium | About $45 per month, roughly $538 per year, at $1M/$2M |
| US market size | Other liability direct premiums written of $129.2B in 2024 |
| Q1 2026 rate change | Up 2.6%, in a market down 1.2% overall |
What is actually inside the form
A CGL policy is three coverages bolted onto one set of conditions, and they behave very differently.
Coverage A is the one people mean when they say liability insurance. It pays damages the business becomes legally obligated to pay because of bodily injury or property damage caused by an occurrence, defined as an accident, including continuous or repeated exposure to substantially the same harmful conditions. The customer who slips in the entryway, the plumbing subcontractor whose fitting floods a finished lobby, the pallet that falls off a forklift onto a delivery driver.
Coverage B is the odd one. It covers a closed list of non-physical offenses: libel, slander, malicious prosecution, wrongful eviction, invasion of privacy, and use of another’s advertising idea or infringement of copyright, trade dress, or slogan in an advertisement. It is why a marketing agency with no physical premises still carries CGL. It is also the coverage most exposed to the new exclusions discussed below, because generated content lands squarely inside it.
Coverage C pays reasonable medical expenses for someone injured on the premises regardless of fault, subject to a small sublimit, usually $5,000 or $10,000. Its purpose is not really coverage. It is a settlement tool that resolves a minor injury before a lawyer gets involved.
Sitting alongside these is the supplementary payments provision, which is where most of the economic value of the policy actually lives.
The limit is a 1986 artifact
The general aggregate limit arrived with the 1986 ISO CGL rewrite. So did the $1M/$2M convention, which spread through commercial contracts, lease riders, and bid specifications until it became the default requirement almost everywhere. Contract templates from 2026 still specify it in the same numbers.
Nothing indexes it. The Consumer Price Index for All Urban Consumers stood at 109.6 as a 1986 annual average and at 333.918 in July 2026, a factor of 3.05. On that basis a $1 million occurrence limit purchased today is worth about $328,200 in the money the limit was set in, a loss of roughly 67% of its purchasing power. Holding the 1986 standard constant would require a limit of $3.05 million per occurrence and $6.09 million aggregate.
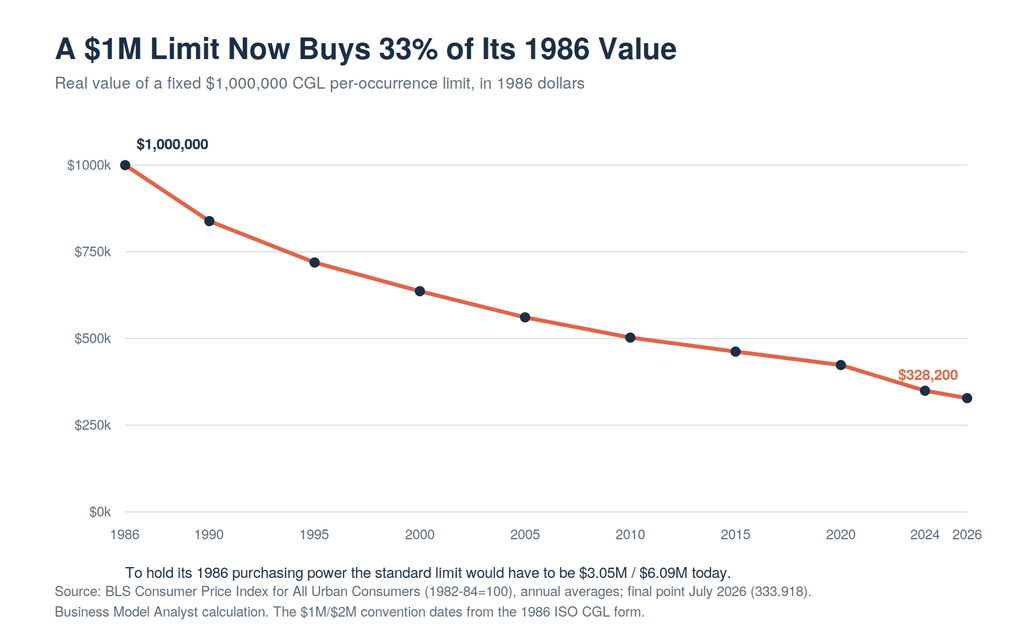
This is not an argument that everyone is underinsured by a factor of three. Most claims are small, and most businesses never touch their limit. It is an argument about what the limit is for. A number that has silently shed two thirds of its value while remaining the market default was never functioning as a considered estimate of maximum loss. It is a contractual convention, carried forward because contracts kept asking for it.
The buyer who treats the limit as the product is buying the wrong thing.
What the premium is really paying for, part one: the defense
Under the standard CGL, the insurer has a duty to defend any suit seeking covered damages, even a groundless one, and the cost of that defense is paid as a supplementary payment in addition to the limits. Attorney fees, expert witnesses, court costs, and investigation expenses do not erode the per-occurrence limit. The obligation continues until the applicable limit is exhausted by payment of judgments or settlements.
That structure is unusual and worth pausing on. Most professional liability, directors and officers, and cyber policies are written with defense inside the limits, so every dollar of legal spend is a dollar less available to pay a judgment. The CGL does the opposite. It hands a small business an effectively uncapped litigation budget for a median premium of about $45 per month.
Run the arithmetic from the buyer’s side. A defended lawsuit that goes to discovery and settles on the courthouse steps can consume several hundred thousand dollars in defense costs alone. At $538 a year, a business would need to buy the policy for centuries to fund one such defense out of its own premiums. The indemnity limit is the visible product. The defense obligation is the expensive one, and it is the reason the duty to defend is the most litigated provision in the entire form.
This also explains why insurers have spent the last three years narrowing the perimeter rather than raising the price. If the obligation attached to a covered claim is open-ended, the only lever with real leverage is the definition of a covered claim.
What the premium is really paying for, part two: the certificate
The second thing a business buys is permission to work.
A general contractor will not let a subcontractor on site, a landlord will not hand over keys, and a corporate client will not issue a purchase order without a certificate of insurance naming them as an additional insured. The endorsements that do this, principally CG 20 10 for ongoing operations and CG 20 37 for completed operations, cost most policyholders little or nothing. Their commercial value is enormous, because without them the business is not eligible to bid.
The trap sits in the 04 13 editions, further tightened in the 12 19 versions. Coverage for an additional insured now applies only to the extent permitted by law, and it will not be broader than what the named insured was required by contract to provide. On limits, the endorsement states that the most the insurer will pay on behalf of the additional insured is the lesser of the amount required by the contract or the amount available under the applicable limits shown on the declarations, and that the endorsement shall not increase those limits.
Read that last clause carefully. The underlying contract has been promoted into a coverage document. If the subcontract asks for less than the policy provides, the additional insured gets the smaller number. If it asks for more, the policy still governs. And every additional insured added during the year draws from the same pool.
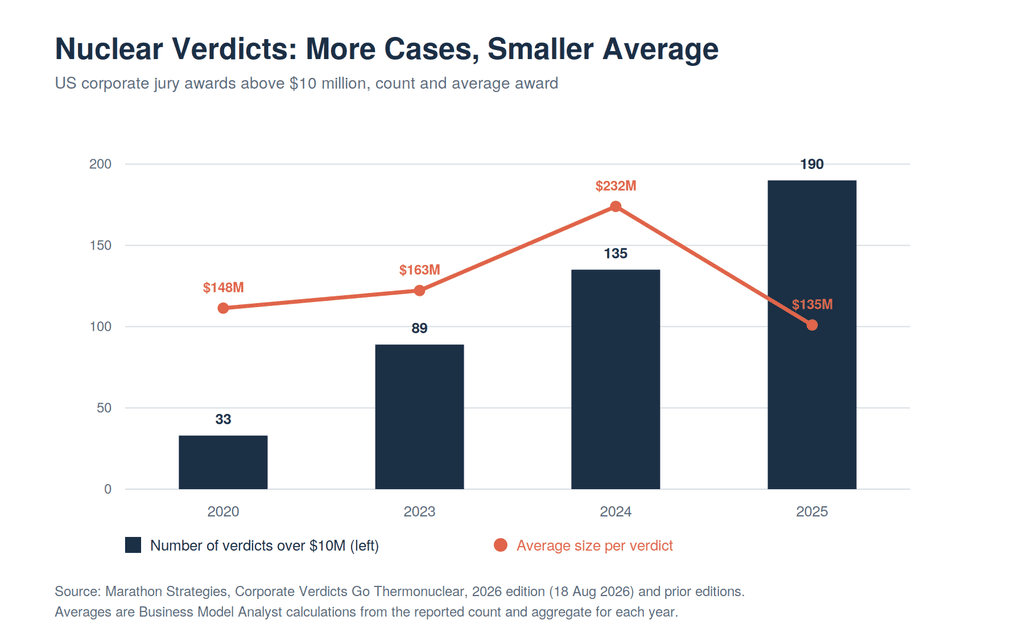
A contractor running fifty active jobs has not bought fifty policies. The general aggregate is one shared pool per policy year, and a bad year on three projects can exhaust it for the other forty-seven. Per-project aggregate endorsements exist and are worth asking about specifically. Most contractors have never been offered one.
Where the policy stops
The CGL is written on an all-risk logic: everything is covered unless it is excluded. The exclusions are therefore the real map of the product.
| Excluded | Where the risk goes instead |
|---|---|
| Injury to your own employees | Workers compensation and employers liability |
| Autos you own, operate, or borrow | Commercial auto |
| Rendering or failing to render professional services | Professional liability, errors and omissions |
| Damage to your own work or your own product | Nowhere, this is a business cost |
| Pollution, and PFAS under CG 40 32 05 23 | Environmental, pollution legal liability |
| Access or disclosure of personal information, CG 21 06 and CG 21 07 | Cyber liability |
| Liquor liability for those in the business | Liquor liability |
| Expected or intended injury | Nowhere |
Two of these deserve more than a table row.
The employee boundary. The CGL will not pay when your own employee is hurt on the job, because workers compensation already occupies that ground. The bargain there is exclusive remedy: the injured worker gets benefits without proving fault, and gives up the right to sue the employer in tort. The CGL picks up on the other side of that line, which is why the same forklift accident produces a workers compensation claim if it hits your warehouse employee and a general liability claim if it hits the delivery driver standing next to him. Businesses that misread this boundary end up with a gap where a leased or temporary worker sits, which is why staffing arrangements need to be reviewed against both policies rather than either one.
The your-work exclusion. A CGL is not a performance bond and not a warranty. If a roofer installs a roof badly, the cost of tearing out and redoing the roof is the roofer’s problem. If the bad roof lets water in and ruins the tenant’s inventory, that is property damage to someone else’s property and the CGL responds. Construction defect litigation is largely a forty-year argument about where that line sits.
The exclusions are the pricing lever
Here is the part most coverage explainers miss.
By Q2 2026 the commercial market had turned soft. Average premiums across all account sizes fell 2.0%, following a 1.2% decline in Q1 that ended a 33-quarter run of increases. Commercial property dropped 6.3%, its largest decline since 2010. Workers compensation and cyber each fell 3.2%.
Liability did not participate. Umbrella rose 5.3% in Q2, its 35th consecutive quarterly increase, and commercial auto rose 4.5%. General liability rose 2.6% in Q1 and was not among the ten lines posting decreases in Q2. Brokers put casualty loss-cost trend at 12% to 15%.
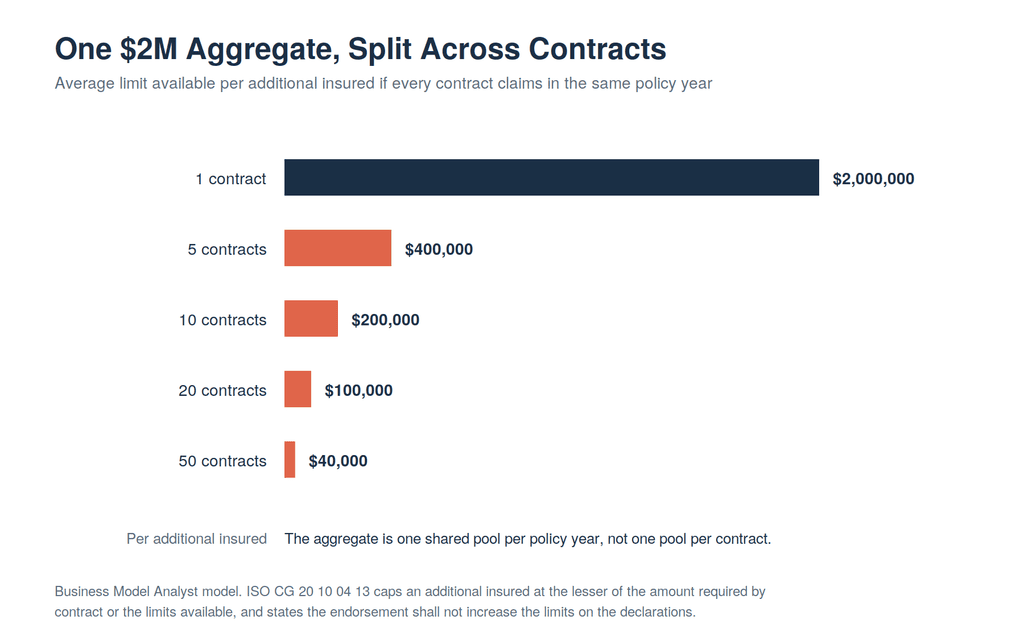
A line priced up 2.6% against a loss trend of 12% to 15% is not being priced to the risk. The gap has to close somewhere, and it is closing through the form.
Since 2023, ISO has published a PFAS exclusion for general liability, CG 40 32 05 23, alongside companion forms for products-completed operations and railroad protective. Effective January 1, 2026, it published three generative artificial intelligence exclusions: CG 40 47 removing bodily injury, property damage and personal and advertising injury arising out of generative AI under both Coverage A and Coverage B; CG 40 48 covering Coverage B alone; and CG 35 08 for products-completed operations. The same multistate filing added underwriting tools for assault or battery, human trafficking, and a punitive damages exclusion.
That is the actual story of the 2026 general liability market. Rate relief on the declarations page, coverage contraction in the endorsement schedule. A business that renews on price and never reads the attached forms may be paying 2.6% more for materially less policy, and the loss will only surface at claim time.
Why the tail risk is moving down-market
The usual justification for all of this is social inflation, and the numbers behind it changed direction in a way worth reading carefully.
Marathon Strategies counted 190 US corporate jury awards above $10 million in 2025, a record and a 40.7% increase over 2024. Those verdicts landed in 97 courts across 28 states and touched a record 68 industries. Georgia led with $4.9 billion across ten cases.
But the aggregate fell. The 2024 cohort of 135 verdicts totaled $31.3 billion; the 2025 cohort of 190 totaled $25.6 billion, down 18%. That works out to an average of $231.9 million per verdict in 2024 and $134.7 million in 2025, a drop of 42%. Marathon’s own framing supports the same reading: it reported the median up 143% from 2020 through 2024, and up 51% from 2020 through 2025, which on its stated 2020 base of $21.5 million implies the median fell from roughly $52 million to roughly $32 million in a single year.
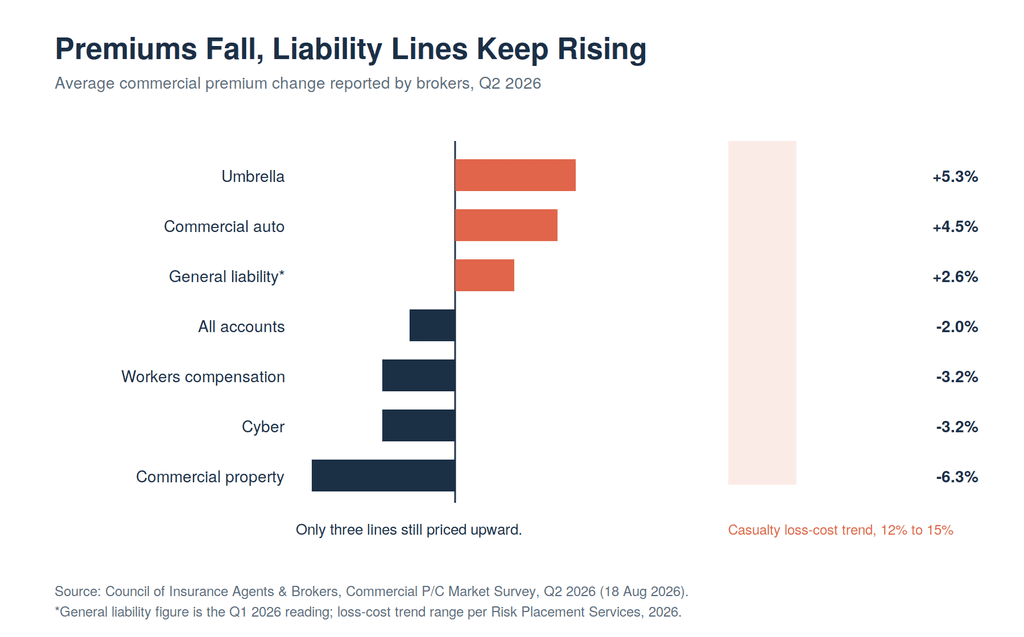
More verdicts, smaller verdicts, spread across more industries and more courtrooms. For a mid-market CGL buyer that is a worse distribution, not a better one. The headline-grabbing billion-dollar award was always an excess-layer problem for a handful of large defendants. A broadening population of awards in the tens of millions, reaching 68 industries, is a primary-layer problem for everyone, because it raises the probability of being in the sample while leaving the individual award far above any standard primary limit.
Which loops back to the beginning. A $1 million occurrence limit is about 0.7% of the average 2025 nuclear verdict. It was never going to pay one. Its function is to attach an umbrella and to fund a defense, and both of those functions are intact.
What it costs
Pricing is driven by industry classification and revenue or payroll far more than by carrier choice.
| Benchmark | Figure |
|---|---|
| Median small-business GL premium | $45 per month, about $538 per year |
| Typical quote range | $22 to $110 per month |
| Modeled average, 1 to 4 employees | $123 per month, about $1,474 per year |
| Lowest-cost sector, modeled | Technology and IT, about $27 per month |
| Highest-cost sector, modeled | Construction and contracting, about $337 per month |
| Business owner’s policy, bundled | About $83 per month |
The spread between a technology consultancy and a roofing contractor at identical limits is roughly twelve to one. That gap is classification, not negotiation. The same logic drives workers compensation pricing, where the class code matters far more than the state.
For businesses financing an acquisition, note that general liability coverage is usually a closing condition rather than an option. Lenders working through SBA 7(a) acquisition financing will typically require evidence of coverage, with the lender named, before funds are disbursed.
Frequently asked questions
Is general liability insurance the same as a business owner’s policy? No. A BOP bundles general liability with commercial property and business interruption into one package, usually for small, low-hazard businesses that meet eligibility rules. The liability part of a BOP is similar to a CGL but not identical, and eligibility caps mean growing businesses often get moved off a BOP onto a package policy.
Does CGL cover my employees? No. Injuries to your own employees arising out of employment are excluded and belong to workers compensation. This is deliberate, and it is the reason both policies exist.
Does it cover professional mistakes? No. Rendering or failing to render professional services is excluded. Advice, design, diagnosis, and other judgment-based work needs professional liability or errors and omissions coverage.
What is the difference between occurrence and claims-made? An occurrence policy, CG 00 01, responds to injury or damage that happened during the policy period no matter when the claim arrives, even years later. A claims-made policy, CG 00 02, responds to claims first made during the policy period, subject to a retroactive date. Nearly all US CGL is written on the occurrence form, which is why long-tail exposures such as products liability and construction defect can reach back into policies written decades ago.
Do defense costs come out of my limit? Not under the standard CGL. Defense is paid as a supplementary payment in addition to the limits. Verify this on any non-standard or surplus lines form, where defense-within-limits wording does appear.
What does naming someone as an additional insured actually give them? Access to your policy for liability caused in whole or in part by your acts or omissions, capped at the lesser of what your contract required or what your limits allow, and only to the extent permitted by law. It does not increase your limits, and it draws on the same aggregate as every other additional insured on the policy.
Is $1 million enough? It is the number your contracts will ask for, which is not the same question. Whether it is adequate depends on your exposure, your contract count, and what sits above it. For most businesses the useful conversation is about the umbrella attaching to the primary and about a per-project aggregate, not about moving the primary from $1 million to $2 million.
The Business Model Analyst Take
Commercial general liability is sold as an indemnity product and consumed as two other things: a litigation-defense subscription and a credential that makes a business contractually employable. The limit is the part everyone negotiates and the part that matters least, because it has been a nominal constant since 1986 and has lost two thirds of its real value while nobody renegotiated it.
The interesting dynamic in 2026 is that carriers appear to have concluded the same thing. They are not repricing the limit to match a 12% to 15% loss trend. They are trimming what triggers the defense obligation, one endorsement at a time, and PFAS and generative AI are simply the two most recent. A soft market that shows up as a 2.6% increase on a line facing double-digit loss trends is not relief. It is the price of a narrower promise, and the narrowing is happening in the endorsement schedule where almost nobody looks.
The practical conclusion for an operator is unglamorous. Read the endorsement schedule at renewal before you read the premium. Ask what was added since last year. Ask whether the aggregate is per policy or per project. Then ask what attaches above the primary, because that is where the money that would actually pay a modern verdict lives.