
The cable giant is splitting into two companies. Strip away the corporate poetry and this is the final death certificate for a 15-year industry bet: that owning the pipes and the content was better than owning either one well.
On Monday, Comcast told the world it is splitting in two. NBCUniversal and Sky go into a brand new publicly traded media company. The broadband and wireless business stays behind under the Comcast name. Wall Street’s reaction was not subtle: the stock spiked as much as 22% before the open and was still up double digits once trading started, after a year in which it had fallen roughly 30%.
Translation: investors had been valuing the combined company at a discount for being a confusing two-headed beast, and the moment management agreed to chop off one head, the math improved. That tells you most of what you need to know about why this happened. But the deeper story is more interesting than a sum-of-the-parts trade, so let us get into it.
What Comcast actually announced
Here is the deal in plain terms, with no investor-relations fog.
| Item | Detail |
|---|---|
| Structure | Tax-free spinoff of NBCUniversal and Sky into a separate public company |
| The new media company | Universal film and TV studios, theme parks, NBC, Telemundo, Bravo, Peacock, Sky |
| The remaining Comcast | Broadband, Xfinity Mobile wireless, business services, cable TV |
| Who runs media | Mike Cavanagh, currently co-CEO, becomes NBCUniversal CEO |
| Who runs connectivity | Michael Angelakis, former CFO, returns as Comcast CEO |
| The retained stake | Comcast keeps up to 19.9% of NBCUniversal for up to a year, then sells it down |
| Timeline | Expected to close in about 12 months, pending board and regulatory approval |
| One more thing | Comcast paused share buybacks while the split is underway |
Existing shareholders end up holding stock in both companies. Nobody is being bought out, and no cash is changing hands. This is a divorce, not a sale. At least for now (more on that comedy bit later).
First, a definition: what is a tax-free spinoff, and why does it matter?
A spinoff is when a parent company hands its shareholders stock in a subsidiary, turning one company into two independent ones. Do it the “tax-free” way under the right IRS rules, and neither the company nor its shareholders owe tax on the separation itself. That is the whole appeal. It lets a conglomerate unbundle without torching value on a tax bill.
The strategic reason companies bother: a focused business is easier for investors to value, easier for managers to run, and crucially, easier to use as a currency for future deals. A pure-play media company can merge with another pure-play media company. A telecom-plus-media hybrid carrying both can do neither cleanly. Hold that thought.
Why now: the convergence bet is officially dead
For about 15 years, the biggest idea in media was “convergence.” The theory: if you own both the content (studios, networks) and the distribution (cable lines, satellite, wireless), you control the customer end to end, and the two halves feed each other. Comcast bought NBCUniversal from General Electric to live this dream, taking control in 2011 and full ownership by 2013 in a deal valued around $30 billion.
Comcast was not alone. It was a religion, and the high priest was AT&T, which went even bigger and lost even harder. If you want the full anatomy of how that played out, the AT&T business model is a useful map, because AT&T ran the exact same playbook two sizes larger and reversed it first.
The problem with convergence is that streaming quietly dissolved the logic underneath it. When distribution was scarce, owning the pipe gave your content a captive audience and owning the content gave your pipe something exclusive to sell. Once anyone could stream anything over any broadband connection, the pipe stopped being a moat for the content, and the content stopped needing your specific pipe. The synergy did not weaken. It evaporated. Cavanagh said it cleaner than most analysts would dare: the company simply changed its mind about whether these businesses belong together.
The convergence graveyard
The fastest way to see why Comcast blinked is to look at what happened to everyone who made the same bet. Every major media-plus-distribution mega-deal of the last decade has been unwound. All of them.
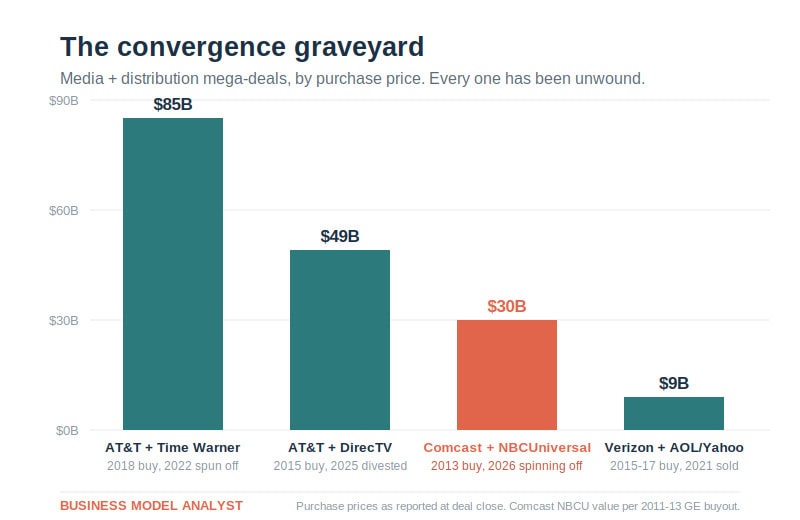
AT&T spent $85 billion on Time Warner in 2018 and spun the whole thing off as part of Warner Bros. Discovery by 2022. It spent $49 billion on DirecTV in 2015 and had fully exited by 2025. Verizon stitched together AOL and Yahoo for roughly $9 billion and sold the mess to a private equity firm in 2021 for less than it paid. Comcast’s NBCUniversal spinoff is simply the last big domino. The graveyard is now full.
Follow the money: where the profit actually sits
Here is the part the celebratory headlines skip. The two companies are not equals, and the split quietly exposes which half was carrying which.
| Comcast (stays) | NBCUniversal (spins off) | |
|---|---|---|
| Core business | Broadband, wireless, cable | Studios, theme parks, networks, Peacock, Sky |
| Cash profile | Strong, steady cash generation | Heavier investment, thinner margins |
| Main threat | Fixed wireless and Starlink eating broadband | Streaming economics and the need for scale |
| Growth story | Xfinity Mobile wireless | Theme parks and franchise IP |
| The catch | Slow growth, defensive | Needs a partner to reach real scale |
Comcast keeps the cash cow but inherits the slow-growth label, with cellphone carriers beaming home internet through the air and Starlink raining down competition from orbit. NBCUniversal gets the glamour assets and the franchises (Minions, Fast and Furious, Wicked), but also the harder question: can a mid-sized media company survive a streaming war that rewards only the giants? Comcast already lost a bidding war for Warner Bros. Discovery assets, which went to Paramount. Scale is the whole game, and NBCUniversal does not yet have enough of it.
The M&A tell: management says no, analysts say obviously yes
Now for the fun part. On the investor call, Chairman Brian Roberts said shareholders should “absolutely not” view the separation as a step toward strategic transactions. Cavanagh added that the split is “definitely not” a precursor to selling NBCUniversal assets.
Reader, the analysts were not buying it. Within hours, the consensus read was that this split is a starting gun, not a finish line. The two most-cited next moves:
| The obvious deal | The logic |
|---|---|
| Comcast merges with Charter | Two shrinking cable players combine to defend broadband. Charter stock jumped on the news, which is the market voting yes. |
| Netflix or a rival buys NBCUniversal | A clean pure-play media company is finally swallowable. Netflix lost the Warner Bros. war and may want the consolation prize. |
Remember the earlier point about a focused company being useful “currency” for deals? A telecom-media hybrid cannot easily merge with either a pure telecom or a pure studio. Two clean pure-plays can. Management saying the split is “definitely not” about future M&A while creating the two cleanest M&A targets in the industry is a bit like clearing your schedule, putting on a nice shirt, and insisting it is “definitely not” a date. The denial is part of the choreography. You do not telegraph a deal twelve months before regulators weigh in.
What this means for founders and operators
You probably do not run a $200 billion conglomerate, so why care? Because the underlying lesson is portable and brutal.
The bundle is only valuable while the thing you are bundling is scarce. Comcast bolted content onto distribution when distribution was the bottleneck. The instant streaming made distribution abundant, the bundle became a tax instead of a moat: two businesses with different growth rates, different investors, and different capital needs, stapled together and trading at a discount for the confusion.
If your business model leans on bundling A with B, the real question is not whether the bundle is convenient today. It is what happens to the bundle the moment one half stops being scarce. Comcast just spent 15 years and a stock-price hangover learning that lesson in public.
Frequently asked questions
Is Comcast being sold or going bankrupt?
Neither. Comcast is splitting itself into two separate publicly traded companies through a tax-free spinoff. Current shareholders will own stock in both. No buyer is involved, and the company is not in financial distress. It is restructuring to lift a valuation discount and gain deal-making flexibility.
What goes into the new NBCUniversal company?
The new media company includes Universal’s film and TV studios, the theme parks division, the NBC and Telemundo networks, Bravo, the Peacock streaming service, and the European broadcaster Sky.
What stays with Comcast?
Comcast retains its broadband internet, Xfinity Mobile wireless, business services, and cable TV operations. This is the connectivity half of the old company.
When will the Comcast split be finalized?
The company expects the spinoff to be completed in about 12 months, subject to board and regulatory approval. Comcast plans to keep a stake of up to 19.9% in NBCUniversal for up to a year afterward and sell it down over time.
Why did Comcast stock go up on the news?
Investors had been applying a conglomerate discount, valuing the combined company below the sum of its parts. Separating the slow-growth connectivity business from the higher-investment media business makes each easier to value and to trade, so the stock jumped on the announcement.
Is the NBCUniversal spinoff a setup for a merger?
Comcast leadership publicly said it is not a precursor to strategic transactions. Many analysts disagree, noting that two focused, pure-play companies are far easier acquisition or merger candidates than a combined telecom-media business. Frequently cited possibilities include a Comcast-Charter cable merger and a sale of NBCUniversal to a streaming rival.
The Business Model Analyst Take
Comcast did not break up because it failed. It broke up because the strategic premise that justified the merger stopped being true, and management was honest enough (or cornered enough) to admit it. That is rarer than it sounds. Most conglomerates cling to a dead thesis for years past its expiration date, defending “synergies” that exist only in slide decks.
The real signal here is not about Comcast specifically. It is that the entire “own the pipes and the content” era is now formally over, buried next to AT&T’s Time Warner adventure and Verizon’s AOL fever dream. What replaces it is consolidation within lanes, not across them: cable companies merging with cable companies, streamers buying studios, each side chasing scale in its own arena instead of pretending the two arenas are one.
So watch the next twelve months closely. Management swears this is not about deals. The cleanest read of the chessboard says it is about almost nothing else. When a company spends a year creating two perfectly merger-ready entities while insisting it has no interest in mergers, believe the structure, not the script.