
What is a SWOT analysis? A SWOT analysis maps a company across four quadrants: Strengths and Weaknesses (internal factors it controls) and Opportunities and Threats (external forces it does not). For Coinbase, the exercise cuts to one tension: a business that dominates U.S. crypto and keeps diversifying its revenue, running inside a market whose volumes still rise and fall with the price of Bitcoin.
Coinbase closed 2025 as the most trusted crypto exchange in the United States and the largest crypto derivatives platform in the world. Then the market turned. First quarter 2026 revenue fell 21% from the prior quarter, and the company posted a $394 million net loss. The Coinbase business model is built to survive exactly this kind of quarter, and the diversification it spent three years building did soften the blow. This analysis breaks down where Coinbase stands in 2026: what protects it, what still exposes it, and the moves that decide whether the next cycle looks different from the last one.
Coinbase Company Overview
| Attribute | Detail |
|---|---|
| Company | Coinbase Global, Inc. |
| Founded | 2012, by Brian Armstrong and Fred Ehrsam |
| CEO | Brian Armstrong |
| Headquarters | Remote-first (no official corporate HQ) |
| Public listing | NASDAQ: COIN (direct listing, April 2021); joined the S&P 500 in May 2025 |
| Business | Cryptocurrency exchange, custody, staking, stablecoin distribution, derivatives, and blockchain infrastructure |
| FY2025 net revenue | $6.9 billion (about $7.2 billion total revenue) |
| FY2025 net income | $1.3 billion |
| U.S. market position | Roughly 67% of the U.S. retail and institutional exchange market |
Coinbase SWOT Analysis at a Glance
| Strengths | Weaknesses |
|---|---|
| Dominant U.S. share and regulatory trust | Revenue still tied to crypto trading cycles |
| Diversified revenue (subscriptions now 44% of net revenue) | Crypto-asset portfolio distorts reported earnings |
| Derivatives leadership after the Deribit deal | High and rising expense base |
| Profitable across bull and bear markets | Heavy reliance on the Circle/USDC revenue stream |
| Base blockchain and USDC economics | Small global footprint versus Binance |
| Opportunities | Threats |
| Stablecoins and payments under the GENIUS Act | Crypto market cyclicality and macro shocks |
| Derivatives and international expansion | Fierce competition from Binance, Robinhood, and Kraken |
| Tokenization of real-world assets | Fee compression and migration to on-chain trading |
| Institutional custody via a national trust charter | Legal and regulatory exposure |
| Prediction markets and new product lines | The Circle relationship turning competitive |
Strengths
Coinbase enters 2026 with the two things that matter most in crypto: scale at home and a reputation regulators trust. Both are hard for a rival to copy quickly.
| Strength | Why it matters |
|---|---|
| U.S. market dominance | ~67% of U.S. retail and institutional exchange volume; over 12% of all crypto worldwide sat on Coinbase in 2025 |
| Regulatory trust | Highest trust scores among global exchanges; a licensed, compliance-first operator |
| Revenue diversification | Subscription and services reached $2.8B in FY2025, 44% of net revenue in Q1 2026 |
| Derivatives leadership | Deribit gives Coinbase roughly 87% of Bitcoin options and 94% of Ether options volume |
| Profitability through cycles | 13 straight quarters of positive adjusted EBITDA |
A near-monopoly at home. Binance runs bigger worldwide, but inside the United States Coinbase owns about 67% of retail and institutional exchange activity. When crypto prices fell in early 2026 and nervous traders looked for safety, they moved toward the venue they trusted, and Coinbase reached an all-time high in trading volume market share even as absolute volumes dropped. Its compliance record and public-company disclosure give institutions a reason to route flow through Coinbase rather than an offshore competitor.
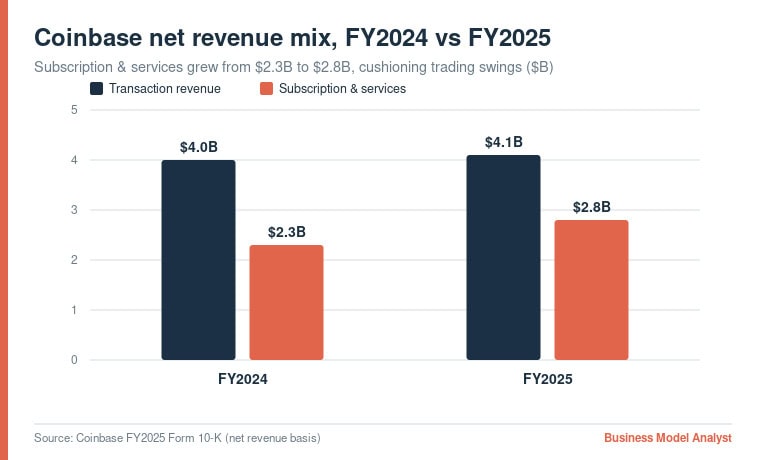
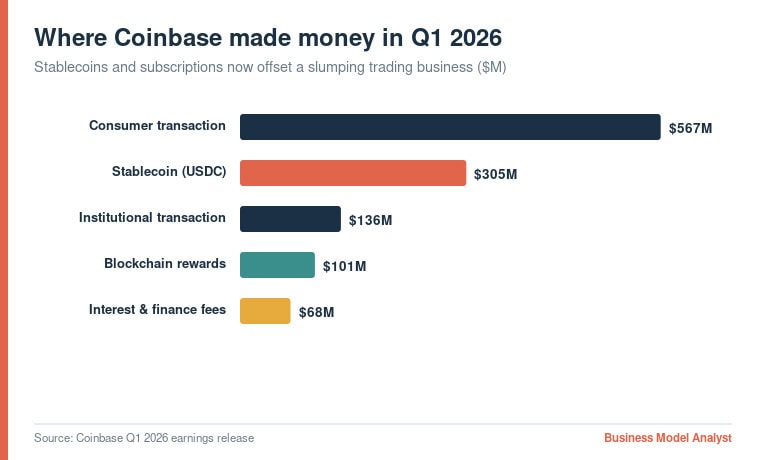
Diversification is doing its job. For years Coinbase lived or died on trading fees. That has changed. Subscription and services revenue, which covers stablecoins, staking, custody, and the Coinbase One membership, hit $2.8 billion in FY2025 and made up 44% of net revenue in the first quarter of 2026. Stablecoin revenue alone contributed $305 million in the quarter, and Coinbase One passed one million paid subscribers. This is the “everything exchange” thesis in numbers: build enough recurring revenue that a slow trading quarter no longer decides the whole year.
Derivatives leadership, bought and paid for. In August 2025 Coinbase closed its $2.9 billion acquisition of Deribit, the largest deal in crypto history and the move that made it the leading global crypto derivatives platform. Deribit brought a commanding share of Bitcoin and Ether options and pushed institutional transaction revenue to a record, up 37% year over year. Derivatives trade far larger volumes than spot, so this hands Coinbase a growth lane that runs on professional and institutional demand rather than retail sentiment.
It makes money when others do not. Coinbase has now posted 13 consecutive quarters of positive adjusted EBITDA across both bull and bear conditions. Free cash flow ran near $1.6 billion, and the company holds close to $10 billion in cash and USDC resources. That balance sheet is what let Coinbase buy Deribit outright and keep investing while smaller exchanges retrench.
Weaknesses
The same design that makes Coinbase resilient also leaves it tethered to forces it cannot control. The first quarter of 2026 put every one of these on display.
| Weakness | The exposure |
|---|---|
| Trading dependence | Transaction revenue still ~55% of net revenue; consumer volume fell 54% year over year in Q1 2026 |
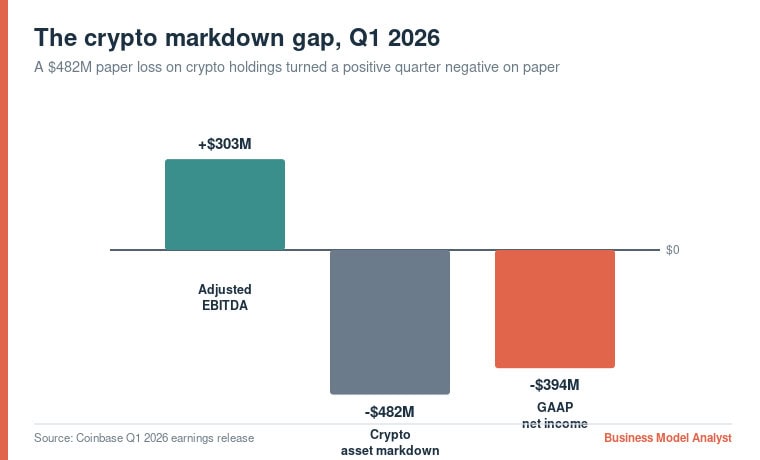
| Earnings volatility | A $482M paper loss on crypto holdings drove the Q1 2026 net loss |
| Rising costs | 2026 adjusted expense guidance of $4.3B to $4.6B; a Q2 headcount cut costing $50M to $60M |
| Circle dependence | Roughly $908M a year in USDC distribution income, up for renegotiation in August 2026 |
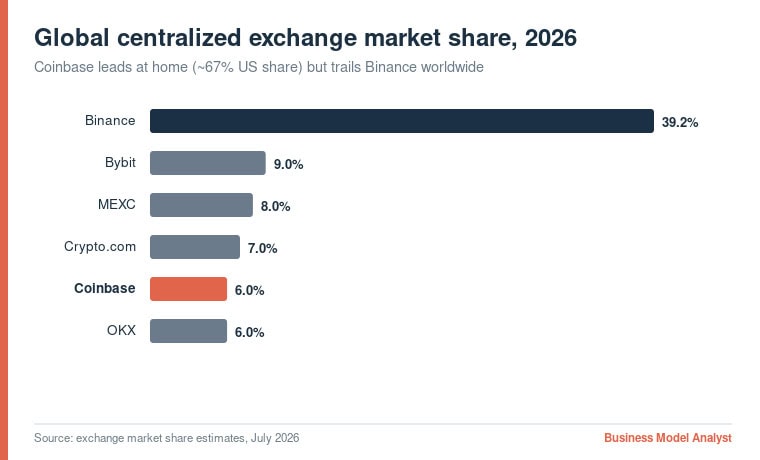
| Global scale | About 6% of global centralized exchange volume versus Binance at 39% |
Trading still runs the show. Diversification helps, yet transaction fees remain the largest single revenue source, and they move with the market. Consumer spot volume fell 54% year over year in the first quarter of 2026, dragging consumer transaction revenue down 23% in a single quarter. When crypto cools, Coinbase feels it faster and harder than a diversified brokerage would.
Reported earnings swing on paper losses. Coinbase holds a large crypto-asset investment portfolio, and accounting rules force it to mark that portfolio to market every quarter. In Q1 2026 a $482 million decline in those holdings turned a quarter with positive $303 million adjusted EBITDA into a $394 million GAAP net loss. The operating business was not the villain, but headline losses spook investors and make the stock harder to value.
Costs are climbing. Operating expenses rose 35% year over year heading into 2026, and management guided full-year adjusted expenses to between $4.3 billion and $4.6 billion. To hold the line, Coinbase announced a headcount reduction in the second quarter that carries a $50 million to $60 million restructuring charge. Chasing the everything-exchange vision across derivatives, payments, and tokenization costs real money, and in a down market that spending shows up as margin pressure.
Reliance on one partner for a big slice of revenue. Coinbase collects roughly $908 million a year from Circle for distributing USDC. That single stream sits inside the subscription business that investors prize for its stability, which makes the dependence a genuine soft spot. More on why below, under Threats.
Opportunities
Every weakness above has a mirror image. The regulatory thaw and the shift of finance onto blockchains give Coinbase more room to grow than at any point in its history.
| Opportunity | The upside |
|---|---|
| Stablecoins and payments | GENIUS Act clarity; USDC near $74B market cap; the Coinbase One Card and payments rails |
| Derivatives and international | Deribit integration, U.S. perpetual futures, unified spot-futures-options trading |
| Tokenized real-world assets | Tokenized equities and commodities settling on Base; the RWA sector already at $31B to $34B |
| Institutional custody | OCC conditional approval for a national trust charter, unlocking custody mandates |
| New product lines | Prediction markets, retail derivatives, and other everything-exchange bets |
Stablecoins get a legal runway. The GENIUS Act gave U.S. stablecoins the regulatory clarity the industry waited years for. USDC now carries a market cap near $74 billion, and Coinbase is pushing it beyond trading into payments through products like the Coinbase One Card. Stablecoin income already cushions weak trading quarters. As regulated dollar-backed tokens move into everyday commerce, Coinbase sits at the distribution center of the second-largest one.
Derivatives and the world outside the U.S. Deribit did not only buy market share, it bought reach. Most of Deribit’s users sit outside the United States, giving Coinbase a larger international and institutional base than it built on its own. The plan to merge spot, futures, and options into one trading experience, plus newly launched U.S. perpetual-style futures, opens revenue that retail spot trading never touched.
Tokenization could be the next platform. Moving stocks, bonds, and commodities onto blockchains is the industry’s biggest long-term bet, and Coinbase owns Base, a fast-growing Layer 2 that can serve as the settlement layer. The tokenized real-world asset sector already sits between $31 billion and $34 billion excluding stablecoins. Coinbase has described its planned tokenized stocks as 1:1 backed assets carrying shareholder rights, a stronger structure than the derivative-style tokens some rivals offer. Winning here would tie Coinbase revenue to traditional capital markets, a pool many times larger than crypto trading.
A charter that unlocks institutional money. In April 2026 the Office of the Comptroller of the Currency granted Coinbase conditional approval for a national trust company charter. That approval lets Coinbase pursue institutional custody mandates that require a federally chartered custodian, deepening the recurring, low-volatility revenue that makes the business less cyclical.
Threats
The external risks are the reason COIN trades like a high-beta stock. Competition is intensifying from every direction at once, and the market itself remains the wildcard.
| Threat | The danger |
|---|---|
| Market cyclicality | Volumes and revenue swing violently with crypto prices and macro conditions |
| Competition | Binance globally, Robinhood on momentum and tokenization, Kraken on new features |
| On-chain migration | Decentralized exchange share rose to 13.6%; fee compression on spot trading |
| Legal and regulatory risk | A New York AG lawsuit over prediction markets; shifting global rules |
| The Circle wildcard | An August 2026 revenue renegotiation with a partner now selling competing products |
The market giveth and taketh away. Total crypto market cap and trading volumes each fell more than 20% in the first quarter of 2026, and Coinbase revenue fell with them. No amount of diversification fully escapes this. A prolonged bear market compresses trading fees, staking rewards, and even the interest income tied to crypto balances, all at once.
Rivals are circling from every side. Binance still processes roughly 39% of global centralized exchange volume, dwarfing Coinbase at about 6% worldwide. Binance’s business model scales on low fees and a vast international base Coinbase cannot easily reach. Closer to home, Robinhood grew revenue nearly 52% in 2025 against Coinbase’s 9%, launched its own blockchain, and pushed tokenized stocks into more than 120 countries. Kraken is rebuilding around agentic trading and now offers tokenized equities. The competition to define how crypto exchanges reach new users has never been sharper.
Trading is moving on-chain. Decentralized exchanges climbed from 6.9% of spot volume in January 2024 to 13.6% two years later. Every trade that settles on a DEX bypasses Coinbase’s fee entirely. Combined with steady pressure on retail take rates, this squeezes the spot-trading economics that still generate the majority of transaction revenue.
The courts and regulators cut both ways. The same government that passed the GENIUS Act can also constrain Coinbase. The New York Attorney General sued the company over its prediction markets, alleging they amount to gambling. Rules on tokenized securities, derivatives, and stablecoins are still being written, and a single adverse ruling can close a product line overnight.
The Circle relationship is turning tense. Coinbase earns roughly $908 million a year distributing USDC, and that agreement comes up for renegotiation in August 2026. The partner on the other side is no longer purely an ally. Circle launched cirBTC in April 2026 to compete with Coinbase’s own cbBTC, and analysts expect Coinbase’s share of USDC economics to drift toward a straight 50/50 split by 2027. Coinbase answered in June 2026 by joining the Open USD consortium, a rival stablecoin project that offers partners a majority of reserve income. That move both diversifies Coinbase away from USDC and hands it leverage going into the renegotiation, but it also signals that the most reliable line in the subscription business is now contested.
Coinbase by the Numbers
| Metric | Figure | Source |
|---|---|---|
| FY2025 net revenue | $6.9 billion | Coinbase FY2025 Form 10-K |
| FY2025 net income | $1.3 billion | Coinbase FY2025 Form 10-K |
| FY2025 adjusted EBITDA | $2.8 billion | Coinbase FY2025 Form 10-K |
| Q1 2026 revenue | $1.41 billion (down 21% QoQ) | Coinbase Q1 2026 earnings |
| Q1 2026 net loss | $394 million | Coinbase Q1 2026 earnings |
| Q1 2026 adjusted EBITDA | $303 million (13th straight positive quarter) | Coinbase Q1 2026 earnings |
| Subscription and services share | 44% of net revenue | Coinbase Q1 2026 earnings |
| Average USDC on platform | $19 billion (record) | Coinbase Q1 2026 earnings |
| Coinbase One subscribers | 1 million+ paid | Coinbase Q1 2026 earnings |
| Deribit acquisition | $2.9 billion, closed August 2025 | Coinbase / Deribit |
| USDC distribution income | ~$908 million per year | Circle disclosures |
| U.S. exchange market share | ~67% | Bernstein / industry estimates |
| Global CEX market share | ~6% | Industry estimates, 2026 |
Coinbase vs Key Competitors (2026)
| Coinbase | Binance | Robinhood | Kraken | |
|---|---|---|---|---|
| Model | Full-stack crypto exchange, custody, stablecoin, derivatives | Global exchange, lowest fees, broadest asset list | Retail brokerage plus crypto, stocks, options | Crypto exchange plus tokenized stocks |
| Global CEX share | ~6% | ~39% | Not ranked among top CEXs | Top-5 by trust score |
| U.S. position | Dominant (~67%) | Restricted U.S. access | Large retail base | Strong, compliance-focused |
| Edge | Regulatory trust, derivatives, USDC economics | Scale, liquidity, international reach | Growth momentum, tokenization lead | Advanced features, agentic trading |
| Weak spot | Cyclical, U.S.-concentrated | U.S. regulatory friction | Payment-for-order-flow exposure | Smaller scale |
Frequently Asked Questions
How does Coinbase make money in 2026? Coinbase earns revenue two ways. Transaction fees from buying, selling, and trading crypto make up a bit over half of net revenue and rise and fall with the market. The rest comes from subscription and services: stablecoin distribution income from USDC, staking rewards, custody, interest income, and the Coinbase One membership. That second bucket reached 44% of net revenue in early 2026 and gives the business a recurring cushion.
Is Coinbase profitable? It depends on the measure. Coinbase has posted positive adjusted EBITDA for 13 straight quarters and earned $1.3 billion in net income for full-year 2025. On a GAAP basis, individual quarters can show losses, as in Q1 2026, when a $482 million paper markdown on its crypto holdings produced a $394 million net loss even though the operating business ran positive.
Who are Coinbase’s biggest competitors? Binance is the largest crypto exchange worldwide by volume, though its U.S. access is restricted. Robinhood competes hard for retail users and has moved fast on tokenized stocks. Kraken targets advanced traders and is expanding into tokenized equities. In derivatives, Coinbase also faces traditional venues like CME Group.
Why did Coinbase buy Deribit? Deribit was the global leader in crypto options. The $2.9 billion acquisition, closed in August 2025, made Coinbase the largest crypto derivatives platform in the world, gave it roughly 87% of Bitcoin options and 94% of Ether options volume, and added a large international and institutional user base. Derivatives trade far higher volumes than spot, so the deal opened a growth lane less dependent on retail sentiment.
What is the biggest risk to Coinbase? Its dependence on crypto market cycles. When prices and volumes drop, transaction revenue drops with them, as the 21% revenue decline in Q1 2026 showed. Layered on top are intense competition, the migration of trading to decentralized exchanges, legal exposure, and the August 2026 renegotiation of its USDC revenue-sharing deal with Circle.
The Business Model Analyst Take
Coinbase spent three years turning a trading-fee business into something sturdier, and the first quarter of 2026 was the stress test. The verdict is split. The diversification worked: subscriptions and stablecoins kept adjusted EBITDA positive through a brutal quarter, and the Deribit deal handed Coinbase a derivatives franchise that runs on institutional demand rather than retail mood. The vulnerability is also clear: transaction fees still drive the top line, a paper markdown can flip the headline to a loss, and the most dependable subscription line now rests on a Circle partnership that is turning competitive.
The bet worth watching is tokenization. If Coinbase brings real stocks and bonds on-chain through Base with genuine shareholder rights, it stops being a crypto exchange and becomes infrastructure for a much larger market. Robinhood moved faster on tokenized equities, and that lead is the sharpest competitive signal on the board. Coinbase has the balance sheet, the regulatory standing, and the charter to win the institutional version of this race. Whether it wins the consumer version depends on catching up on products where a hungrier rival got there first. The everything exchange is a strong idea. In 2026, execution against Robinhood is the variable that decides how strong.