
The company gave CNBC a tour of its Atlanta innovation labs, where it is automating dirty soda and prototyping an unbranded energy drink for restaurants to name themselves. The equipment is becoming the moat.
Coca-Cola’s newest foodservice products are designed to carry someone else’s name. A white-label lemonade already runs through more than 40,000 dispensers, some of it sold as Wendy’s Dave’s Craft Lemonade. An unbranded energy drink arrives with operators in the first half of 2027. The company that turned a trademark into the most valuable asset in packaged goods is now renting out the parts of its business that do not include the trademark, because that is what restaurant operators want to buy.
Walk into an anonymous office park a short drive from Coca-Cola’s global headquarters and you find two buildings facing each other across a parking lot. One holds the Equipment Innovation Center, where a wall-sized screen shows what people are pouring from Freestyle machines right now, by hour, by region, by type of venue. AHA sparkling water is climbing in office buildings and hospitals. The other building is called The Vault, where Coke brings its largest customers to taste things. Neither building sells a single case of Coca-Cola. Both exist because the restaurant is the one place in the world where Coke controls the whole chain from syrup to cup, and it has decided to defend that position with hardware.
What Happened
CNBC published a tour of Coca-Cola’s Atlanta innovation labs on August 22, 2026, and the equipment list is the story. Coke engineers built a prototype that bolts a dairy module onto a standard Freestyle dispenser so a machine can produce a dirty soda, the drink category that mixes pop with syrup, cream and other add-ins. The prototype runs a preprogrammed recipe with little room for customization, keeps the signature drip down the side of the cup, and took about three weeks to build.
Alongside it sits a Micro Matic mixology dispenser Coke is testing with AMC Theatres to pour brightly colored refreshers, and a Freestyle Mini built for bars with no counter space. The Mini holds 16 drink options against roughly seven on a conventional soda gun, launched first in Europe, and appeared at the National Restaurant Association Show in Chicago this spring. Coke has not put it on sale in the United States yet.
The most consequential item on the list has no flavor at all. Coke is developing a colorless, near-neutral energy drink in frozen and liquid form, built so an operator can tint it, flavor it and put its own brand on the cup. The company plans to launch it with foodservice partners in the first half of 2027. A 12-ounce serving carries 106 milligrams of caffeine, roughly a Red Bull and about half a Celsius, and Coke intends it to be employee-served to cap how much any guest can order.
Megan Tallman, who runs dispensed equipment and innovation for Coke’s North American business, framed the demand side plainly: unique beverages are no longer a bonus with consumers, they are the expectation, and Gen Z will pay ten dollars for a drink that photographs well. Circana’s David Portalatin told CNBC that beverage servings at US restaurants outpaced both food-only and food-with-beverage servings in the second quarter.
The Backstory
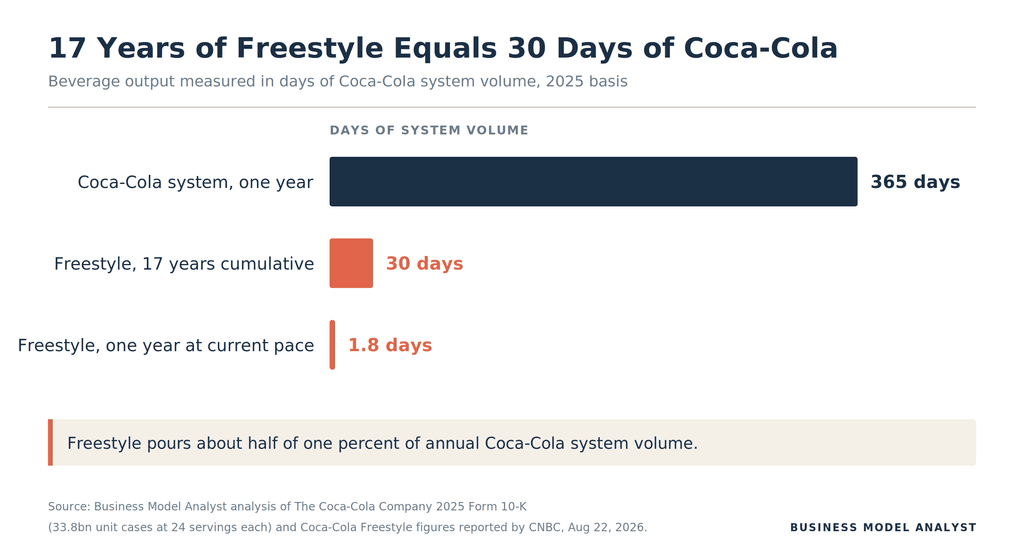
Freestyle turned 17 in July. When Coke launched it in 2009, the pitch was variety, more than a hundred combinations from one cabinet. What Coke got instead was telemetry. More than 50,000 machines now report what gets poured, where and when, and the company says the fleet has dispensed over 67 billion eight-ounce servings since launch.
Those numbers are smaller than they sound. The Coca-Cola system sold 33.8 billion unit cases in 2025, and a unit case is 24 eight-ounce servings, so the system moved about 811 billion servings last year. Freestyle’s entire 17-year output equals roughly 30 days of that. At Coke’s own current figure of about 11 million servings a day, the fleet pours around four billion servings a year, close to half of one percent of system volume. The two disclosures do not reconcile cleanly either, since 67 billion across 17 years implies the fleet ran near its present pace from the first machine, which nobody believes. Treat 67 billion as a generous ceiling and the share gets smaller.
Freestyle earns its keep on cycle time. Coke says data from the fleet turns an idea into a market-ready drink in as few as 90 days against roughly 18 months through the traditional route, and it points to Fanta Crimson Sour Cherry at White Castle and Sprite Loco Lime at Wingstop as examples that went from concept to nozzle in under three months. Coca-Cola Orange Cream reached grocery shelves after the fountain data said the combination worked. Tallman calls the fleet the largest testing platform in the business, and on that framing she is right. It is a laboratory that happens to sell soda.
Two other things changed while Coke was watching. Technomic now tracks more than 100 specialty beverage chains running over 41,000 US locations, all of them promising the customizations a soda gun cannot. And Coke’s own core stopped growing in its home market: North American unit case volume fell 1% in 2025, in a portfolio where sparkling soft drinks still make up 69% of worldwide volume and Trademark Coca-Cola alone accounts for 47%, a concentration the Coca-Cola SWOT analysis treats as both the strength and the exposure.
The Plan
Coke’s answer runs on three tracks. The first is hardware that removes a labor step. A dirty soda made by hand is a crew task with cream, syrup pumps and mess; a dirty soda made by a dairy module is a button. The same logic applies to the mixology station pouring refreshers and iced coffee. Coke is selling operators the handcrafted drink without the hand.
The second track is category definition. Starbucks invented the refresher in 2012 to fill the afternoon lull, and it now carries roughly $2 billion of annual sales. Refreshers appear on 8.1% of national chain menus, according to Datassential, and Brian Niccol told analysts in late April that the imitation counts as a compliment. Sarah Kate Sims, who directs dispensed innovation for Coke North America, admits there is no accepted definition of a refresher and says Coke wants to set one: a lighter drink with a lift, built on green tea or a natural coffee extract rather than a coffee base, and good-looking in the cup.
The third track is the one Coke says least about. It is building products for operators to brand themselves. Coke worked with Whataburger for about 18 months on the Whatafreshers line, which the chain put on its permanent menu on July 1, 2025, meaning the collaboration started around the beginning of 2024. Coke calls itself a pioneer of premium lemonade after white-labeling one more than a decade ago, and that lemonade now flows through over 40,000 bubbler dispensers including Wendy’s. The energy drink coming in 2027 takes the same idea further by shipping with no color and almost no flavor.
The Business Model Angle
Start with why any of this happens in a restaurant rather than a supermarket.
Everywhere else, a bottler stands between Coca-Cola and the customer. Coke sells concentrate, the bottler mixes, packages, sells and owns the shelf relationship, which is the arrangement the Coca-Cola business model has run on since 1899 and the sequence the Coca-Cola value chain analysis maps step by step. In the United States, the 10-K describes something different: Coca-Cola manufactures fountain syrups itself and sells them to fountain retailers or to authorized wholesalers, and those sales land in the North America segment. Fountain is the one channel where Coke makes the product, places the equipment, signs the account and reads the data. Concentrate operations produce 59% of the company’s $47.9 billion in 2025 revenue at a 61.6% gross margin, and fountain is the slice of that where nobody else touches the customer.
That explains the labs. It also explains why Coke will trade its name to keep the position.
Restaurant operators have worked out that beverages carry the best margin on the menu and the best differentiation. McDonald’s chief executive Chris Kempczinski told analysts in early August that US drink sales are running ahead of plan, checks are higher and new occasions are appearing across the day. Once an operator wants a signature drink, a branded Coke product becomes a problem rather than a solution, because a signature drink cannot carry a supplier’s logo. Whataburger did not want a Coca-Cola refresher. It wanted a Whatafresher.
Watch what happened when Coke insisted on a brand. McDonald’s spent 70 years as Coke’s flagship account. In May 2026 it added refreshers and crafted sodas using Sprite and Hi-C. On August 11 it announced the Red Bull Dragonberry Energizer, its first energy drink, rolling out from August 17. Coca-Cola bought 16.7% of Monster Beverage in 2015 for $2.15 billion net cash and holds close to a fifth of it today, plus board seats and a distribution agreement, one of the stakes catalogued in the Coca-Cola subsidiaries breakdown. Given the choice of energy partners, McDonald’s took the one Coke has no stake in. Coke chief executive Henrique Braun told analysts in late April that the McDonald’s partnership is intact and that Coke respects its customers’ other relationships, which is what you say when a customer has just picked someone else.
The same press release announcing Red Bull introduced the Vanilla Swirl, a cold-foam dirty soda built on Coca-Cola, Diet Coke or Coke Zero Sugar. McDonald’s took a rival’s brand for the energy slot and used Coke as the base layer for its own crafted line. That is the shape of the whole transition. Coke keeps the liquid and the machine, McDonald’s keeps the name.
Read the two development clocks and the strategy gets clearer. A flavor that lives inside Coke’s own Freestyle machine ships in 90 days. A drink that carries an operator’s name took Whataburger 18 months. Coke is pushing into the slower, lower-margin lane on purpose, because a brand can be swapped at contract renewal and a dairy module bolted to a Freestyle cabinet cannot.
The Risk
The obvious objection is that Coke is walking into the private-label trap it spent a century avoiding. Concentrate margins exist because the trademark does the demand generation; the operator pays a premium for a drink customers already want. Sell an unbranded syrup and the next conversation is about price. Dave’s Craft Lemonade belongs to Wendy’s. Coke supplies it for exactly as long as it stays the cheapest qualified supplier, and the day a co-packer quotes lower, there is no consumer to complain.
Against that, Coke has run the lemonade white label for more than a decade across 40,000 dispensers and its gross margin still rose to 61.6% in 2025 from 61.1%. The trap is a risk, not a verdict.
The harder problem is whether any of this adds volume. Coke tracks a metric it calls incremental volume, which asks whether a guest buys the new refresher who would otherwise have bought nothing. A Kalinowski Equity Research survey of several dozen US McDonald’s franchisees found more than half saying specialty drinks perform in line with expectations, with one operator putting it bluntly: the drinks sell well, but most of it trades off other beverages, and transaction counts have not moved. If a $10 refresher replaces a fountain soda, the operator’s check rises and Coke’s servings fall. PepsiCo ran into the same measurement problem in snacks, where a flavor boom produced spectacular mix data and zero segment volume. That McDonald’s beverage launch also landed in a quarter with US comparable sales up 0.8% and a new US president brought in to fix the domestic business, the same print that exposed how little McDonald’s guest counts matter to its landlord margin.
The category is smaller than the coverage suggests. Refreshers reach 8.1% of national chain menus. Dirty soda, per Datassential figures CNBC cited earlier this year, sits on about 2.7% of US eating establishments, up from 1.5% a decade ago. Doubling from a small base over ten years is a trend, not a wave.
Then there is the equipment itself. Coke has guided 2026 capital expenditure to roughly $2.2 billion against $14.4 billion of operating cash flow, and it has spent a decade telling investors the model is getting more asset-light. Fitting dairy modules, mixology stations and self-cleaning nozzles across a fleet of 50,000 machines pushes in the other direction. Dairy inside a soda fountain is a cleaning and food-safety obligation for the operator, not a flavor decision, and the fast-food graveyard is full of products that died at the crew station rather than the counter. Burger King killed the hand-breaded Ch’King about 15 months after launch for exactly that reason.
Coke has also designed a liability constraint into its energy product before launch. Employee service to limit consumption is not a feature anyone asked for; it is a response to the wrongful-death litigation Panera faced over Charged Lemonade. Caffeine in a self-serve dispenser is a category with legal history.
One last caution on the reporting. The 67 billion serving figure and the 11 million per day figure come from the same company and do not fit the same ramp. Both make Freestyle look like a data asset rather than a volume asset, but neither should be treated as audited.
Quick Questions
Is Coca-Cola going private label? In foodservice, part of it already has. The premium lemonade in 40,000-plus bubblers has been white-labeled for over a decade. The 2027 energy drink extends the model to a growth category rather than a commodity one.
Why would Coke give up its brand on purpose? Because operators are the ones choosing now, and they want the differentiation for themselves. An unbranded product inside Coke’s own machine is harder for a customer to switch than a branded one on a menu board.
Does Freestyle make money? Not on liquid volume. It pours around half a percent of Coca-Cola system servings. It earns its place by cutting product development from roughly 18 months to as little as 90 days and by telling Coke what to launch in grocery.
Is the McDonald’s relationship in trouble? Coke says no. McDonald’s picked Red Bull over Monster for its first energy drink while using Coca-Cola as the base for its own crafted sodas. Both things are true, and together they describe a customer that wants Coke’s liquid without Coke’s branding.
What would prove the strategy is working? Coke’s own incrementality test. If North American unit case volume turns positive while operators keep adding their own named drinks, the machines are creating servings. If volume stays flat, restaurants are redistributing the same cups at a higher price and Coke is funding the equipment.
The Business Model Analyst Take
Coca-Cola is unbundling itself in the one channel it owns outright. For 140 years the trademark, the liquid and the distribution moved together. In American foodservice, Coke is now willing to sell any two of the three, and the customer decides which two.
The trade is defensible on its own terms. Fountain is where Coke makes the syrup, owns the account and reads the data, and no bottler sits in the way. Handing an operator the branding rights buys Coke the whole beverage program instead of a slot on it, and the machine in the corner is stickier than a logo on a cup. The prototype that took three weeks to build tells you how cheap the option is.
The cost shows up later, at renewal. Every drink Coke ships without its name on it teaches an operator that the liquid is separable from the brand, and that lesson does not expire. Coke has one number that will settle it and publishes it every quarter. Watch North American unit case volume, not the flavor announcements.