
Asia Pacific volume grew 8% while price per case fell 9%. Coca-Cola now runs two opposite pricing models inside one income statement, and North America pays for both.
Coca-Cola reported second-quarter 2026 net revenues of $13.4 billion, up 7%, with comparable EPS of $0.97, up 11%, and global unit case volume up 5%. Management lifted full-year comparable EPS guidance to 9% to 10% growth from 8% to 9%, and shares climbed more than 3% before the open.
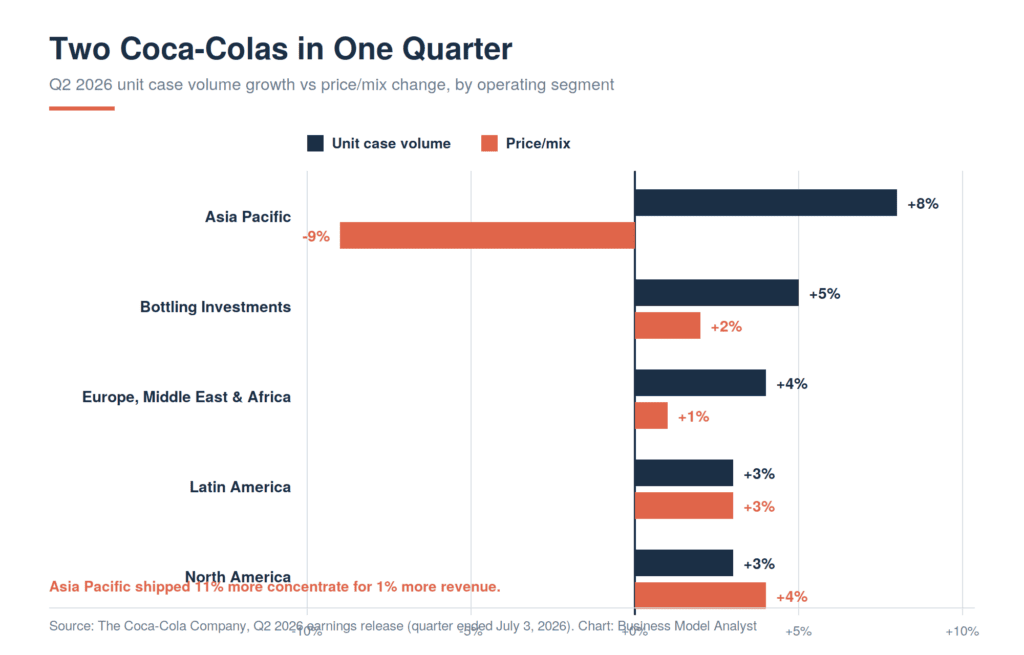
The segment table says something the headline does not. North America grew volume 3% and price/mix 4%, producing 12% comparable currency neutral operating income growth. Asia Pacific grew volume 8% and cut price/mix 9%, producing zero. Coca-Cola is buying case volume in India and China with lower price points, and it is funding that purchase with pricing power in the United States.
Henrique Braun called the consumer landscape “dynamic” in his first set of results as CEO. Three weeks earlier, Ramon Laguarta at PepsiCo used tighter language and worse numbers: North American beverage volume down 4%, core operating margin down 40 basis points, guidance held rather than raised.
The gap between those two prints will drive most of the coverage today. Coke wins, Pepsi struggles, one of them owns snacks and the other does not. That comparison is true and it explains almost nothing about how Coca-Cola made this quarter work. The answer sits four tables deep in the earnings release, in a row where price/mix carries a minus sign.
What happened
Coca-Cola closed the quarter on July 3 with revenue and earnings above consensus and a raised outlook. Operating margin reached 34.9% against 34.1% a year ago. Comparable operating margin reached 35.6% against 34.7%. Reported EPS of $1.03 grew 16%, helped by a 4-point currency tailwind. Year to date, the company converted $7.5 billion of operating cash flow into $6.9 billion of free cash flow.
Zero-sugar carried the brand story. Coca-Cola Zero Sugar volume grew 16% across all four geographic segments. Trademark Coca-Cola grew 5%, Diet Coke grew 7%, water grew 6%, and coffee fell 2%.
The segment detail is where the quarter splits in half.
Asia Pacific shipped 11% more concentrate and collected 1% more revenue for it. The region delivered the largest volume gain in the company and no incremental profit at constant currency. Over the first half, Asia Pacific volume grew 7%, price/mix fell 8%, and comparable currency neutral operating income fell 8%. Coca-Cola also lost value share in the region, with gains in Japan and China outweighed by a loss in India.
The backstory
Coca-Cola sells concentrate, not drinks. Bottlers buy the syrup, add the water and sugar, fill the cans, and run the trucks. That structure has been the point of the company since 1899, and refranchising since 2017 has pushed it further: the parent now owns bottling operations only where it considers direct control strategic, with the Africa business currently under sale agreement.
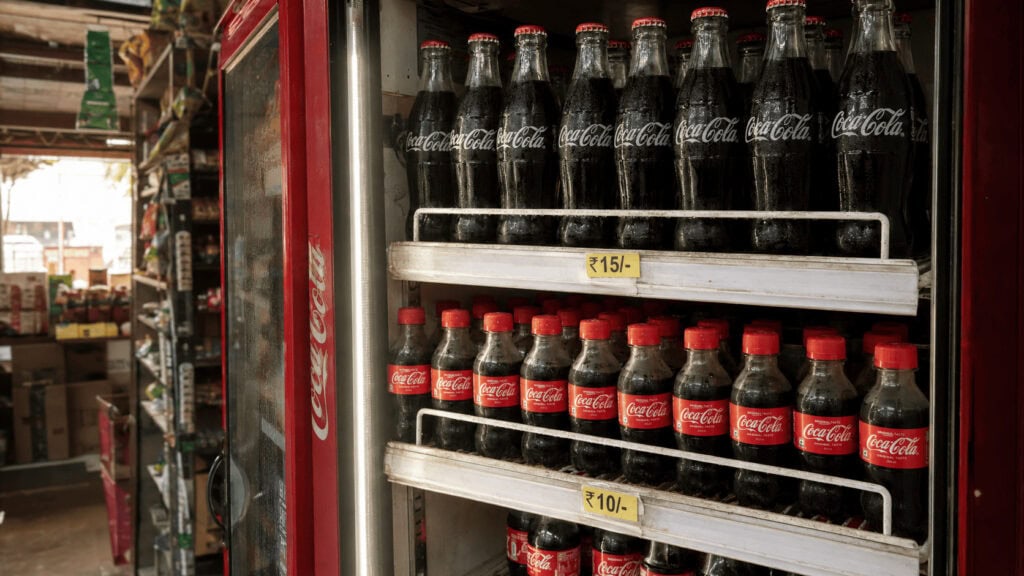
Concentrate pricing looks simple from the outside and behaves in a complicated way. When a bottler in Gujarat sells a 200-milliliter bottle at 10 rupees to widen the customer base, the concentrate price per case has to move with it or the bottler stops making money. Coca-Cola’s price/mix line absorbs that decision. Affordability at the shelf becomes a revenue cut at the concentrate level, one segment at a time.
India and China are where Coca-Cola has the most room to grow servings and the least ability to charge. Per-capita consumption in India runs a fraction of Mexico’s. Every incremental drinker there arrives at a price point that would be uneconomic in Atlanta. Coca-Cola has been running smaller packs, returnable glass, and lower entry prices across South Asia for several years, and Q2 shows the cost of that program with unusual clarity.
The plan
Braun spent his first quarter as CEO putting money behind volume rather than price. Two programs carry that spend.
The FIFA World Cup campaign ran across more than 180 markets. Coca-Cola moved the trophy through roughly 30 countries and 70 stops, activated in more than 20 million retail outlets, and generated over 60 billion impressions with 2,500 content creators. Trademark Coca-Cola grew 5% and Powerade grew 8% during the tournament.
The number worth pulling out of that section is smaller and stranger: 25 million first-party data records, collected from more than 80 million consumers through connected packaging. Coca-Cola has spent 140 years selling through intermediaries and has almost no direct relationship with the people who drink its product. Bottlers know the retailer. Walmart and Amazon know the shopper. Coca-Cola knows the brand. A QR code on a World Cup can is the cheapest route it has found to a customer list.
The second program is a set of regional innovation hubs, built to move a product that works in one market into others faster. Coca-Cola Zero Zero moved from Europe toward Asia Pacific and Latin America. The Sprite and tea combination developed in the United States came back as a lemon-forward version for China.
Both programs point the same direction: more occasions, more drinkers, lower average price.
The business model angle
An asset-light franchise system is supposed to make growth cheap. Coca-Cola takes roughly 35% operating margins on concentrate because the bottler carries the plants, the fleet, and the working capital. That arrangement holds only while the concentrate price holds.
Asia Pacific is a live test of what happens when it does not. Coca-Cola gets the volume, the bottler gets the volume, and the parent’s margin per case compresses to fund entry pricing. The franchise structure does not protect Coca-Cola from affordability programs. It transmits them.
North America is running the mirror image and paying the bill. Volume up 3%, price up 4%, comparable currency neutral operating income up 12%, and share gains in a category where PepsiCo lost 4% of its beverage volume. American consumers absorbed a fourth consecutive year of beverage price increases through a quarter when gas hit $4.56 a gallon. That is a durable competitive fact, and it is the only reason the consolidated numbers look balanced.
Currency is doing the rest of the work in the headline. Latin America reported 16% revenue growth, of which 11 points came from exchange rates, and reported operating income growth of 23% against 4% on a comparable currency neutral basis. At the group level, the raised comparable EPS guidance of 9% to 10% includes about 3 points of currency tailwind. The underlying figure, comparable currency neutral EPS excluding acquisitions and divestitures, moved from 6% to 7% up to 7% to 8%. The business improved by one point. The dollar supplied the rest.
The guidance table carries one more structural signal. Coca-Cola now expects acquisitions and divestitures to cut comparable net revenues by 2% to 3% while cutting comparable EPS by about 1%. Selling revenue that carries a third of the company’s average profit contribution is the arithmetic signature of an asset-light strategy working as designed. The Africa bottling sale, expected to close late in Q3 or during Q4, is the next installment.
The risk
Three items sit outside this print.
fairlife. Coca-Cola disclosed a ransomware event at fairlife on July 16 and confirmed on July 27 that most production had restarted across its four US plants. The quarter closed July 3. None of the disruption appears in these numbers, and fairlife sits inside the juice, dairy, and plant-based line that helped drive North American volume. Q3 will carry whatever the shutdown cost.
The India share loss. Coca-Cola is cutting price in Asia Pacific and losing value share there anyway. Volume growth that does not buy share is a subsidy rather than an investment. One quarter is not a trend, and the first-half figures point the same way.
The price ceiling in North America. The entire structure depends on American consumers continuing to pay 4% more per case. PepsiCo’s quarter suggests the ceiling exists. Coca-Cola has not hit it, and the gap between the two companies on that measure is now the most important number in the beverage sector.
Quick questions
Did Coca-Cola beat expectations in Q2 2026? Yes. Revenue of $13.38 billion came in above the $13.13 billion consensus, and adjusted EPS of $0.97 beat the $0.93 estimate. Coca-Cola raised full-year comparable EPS guidance to 9% to 10% growth from 8% to 9%.
Why did Coca-Cola’s price/mix fall 9% in Asia Pacific? The company is running affordability programs across the region, led by India and China: smaller packs, lower entry price points, and returnable formats aimed at increasing the number of people who drink its products rather than the amount each one spends. Unfavorable product and package mix flows through to the concentrate revenue line as negative price/mix.
How does Coca-Cola make money? Coca-Cola sells concentrate and syrup to a network of independent and partially owned bottlers, who manufacture, package, and distribute finished drinks. The parent company keeps the brand, the formula, and the marketing, which is what produces operating margins near 35% on a fraction of the capital a full manufacturer would need.
Is Coca-Cola beating PepsiCo? In beverages, yes, on both volume and pricing. Coca-Cola grew North American volume 3% with price/mix up 4%; PepsiCo’s North American beverage volume fell 4% and its North American revenue slipped about 2%. PepsiCo’s advantage remains its snack business, which Coca-Cola has no equivalent of.
How much of the guidance raise is currency? About 3 points of the 9% to 10% comparable EPS growth guidance comes from foreign exchange. Stripping out currency and portfolio changes, the underlying guidance moved from 6% to 7% growth up to 7% to 8%.
The Business Model Analyst Take
Coca-Cola posted a strong quarter and the market read it correctly at the surface level. Look one layer down and the company is running a portfolio trade rather than a single business: harvest North America, buy occasions in Asia, and let a weak dollar smooth the reported numbers.
That trade makes sense on a ten-year view. India adds drinkers faster than any market Coca-Cola has left, and the company built its Mexican business the same way, one affordable serving at a time, until Mexico became the highest per-capita market on earth. The concentrate model rewards patience because every new drinker compounds without new capital.
Two things would break the logic. If North American pricing stalls, the subsidy stops and Asia Pacific becomes a drag with nothing offsetting it. If the dollar reverses, three points of guided EPS growth disappear and investors get a clear look at a business compounding in the mid-single digits. Neither is a 2026 problem. Both are worth watching, because Coca-Cola’s stability has always been a composition effect rather than a property of the drink.
The most interesting line in the release remains those 25 million first-party data records. A company that has never owned its customer relationship spent a World Cup building one. That is a bigger strategic move than a guidance raise, and nobody will write about it today.