
The consultants are right that resilience pays for itself. They are measuring a return that clears for an investment-grade balance sheet and fails for everyone else.
McKinsey puts the payback on proven climate adaptation at three dollars of avoided damage per dollar spent. Convert that into the language a lender uses and it becomes a 9.31% internal rate of return on a 30-year asset. An investment-grade corporate borrows at 5.22% and the project clears with room to spare. A single-site operator on an SBA 7(a) loan borrows at 10% to 11.5% and the same project posts a negative net present value. Same equipment, same avoided damage, opposite decision. The adaptation gap that every consultancy calls a planning failure is a credit spread.
In early June a storm took the power out at Stephanie Hart’s bakery on Chicago’s South Side. She had $30,000 of cake sitting in a walk-in freezer and 500 ice cream bars already gone. She spent $1,700 on dry ice, called every politician who owed her a favor, and got the power back the next day. She saved the inventory. She is now weighing a backup generator for next summer and has not bought one.
Price her choice. A commercial standby unit sized for a bakery, in the 30 to 50 kilowatt range, runs roughly $35,000 installed once you include the transfer switch, the concrete pad, the electrical integration and the permits. Finance that over ten years at the high end of the SBA 7(a) variable range and add a service contract, and it costs about $6,900 a year to own. Dry ice costs $1,700 an event. Hart needs something like four freezer-threatening outages a year before the generator beats the dry ice. Chicago handed her two, maybe three. She is not being short-sighted. She is doing the arithmetic correctly.
What Happened
NOAA confirmed on Monday that July 2026 averaged 76.9°F across the contiguous United States, 3.3°F above the 20th-century average and the warmest month in the 132-year record. The composition of that record is the part worth reading twice. Daytime highs averaged 89.5°F and ranked sixth warmest. Overnight lows averaged 64.2°F, ranked first, and beat July 2022 by 0.7°F.
The peak was not the record. The missing trough was. Every refrigeration compressor, every rooftop condenser and every distribution transformer is sized on the assumption that nights give it a recovery window. Strip out the recovery window and the equipment runs at a duty cycle nobody specified it for, which is how a walk-in freezer full of cake ends up depending on a phone call to an alderman.
NOAA also logged the third driest July on record, with roughly 48.5% of the contiguous United States in drought as of August 4. In northern Illinois, two days of storms in June knocked out power to approximately 684,000 ComEd customers, and a later round peaked above 530,000 outages across the Chicago area, with ComEd telling customers the storms are becoming more frequent, more powerful and more destructive.
The New York Times gathered these threads on Tuesday into a piece about businesses accepting that new investment is unavoidable. The reporting is solid. The framing has a hole in it: it treats adaptation as a decision, and adaptation is a financing.
The Backstory
Allianz Research supplied the number every outlet has been quoting. Replay each country’s five hottest years from 2014 to 2024 in ascending order across 2026 to 2030 and cumulative GDP losses reach 5% to 7% for the most exposed economies: $240 billion for France, $354 billion for Japan, $147 billion for Italy, $131 billion for Germany and $120 billion for Spain. Fiscal balances deteriorate by around 0.5% of GDP a year, with annual tax revenue losses of 1.8% in France and 1.3% in Italy and Spain, because progressive systems shed revenue faster than output.
Almost nobody quoted the sentence sitting between those two. Allianz found that the decline in fixed capital formation systematically exceeds consumption losses, reaching 8% on average across affected countries, because heat compresses expected returns on capital and investment falls in response.
Read that against the adaptation advice and the contradiction is hard to miss. Businesses are being told to invest their way out of a shock whose primary economic signature is a collapse in investment. Heat does not arrive as a cost line that firms absorb and move past. It arrives as a hurdle-rate event. It raises the required return on every project at the same moment it adds a new project to the queue.
The Plan
Look at what the operators in the Times piece are doing rather than what the economists recommend.
Hart moved her bakery from make-to-stock to make-to-order, which means slower delivery and choppier shifts. Paloma Corona keeps toddlers indoors at her two Los Angeles day cares and warns parents she may send children home. Nikki Bravo, who runs the Momentum Coffee chain in Chicago, watched Lollapalooza weekend come in 40% below last year on rain and plans to flex staffing against the forecast.
Every one of those responses is a variable cost. Not one is a capital expenditure. Hart traded finished-goods inventory for labor flexibility. Corona traded outdoor programming for higher electricity bills. Bravo traded scheduling stability for payroll control. They are converting a capital problem into an operating problem because operating problems can be paid for out of this month’s cash and capital problems require a lender.
That pattern is not a Chicago story. McKinsey Global Institute puts current global adaptation spending at $190 billion a year against $540 billion needed, which means the world is buying a little over one-third of the protection it already needs despite the economics. Its own explanation names capacity to pay first, with 85% of people in low-income regions lacking any of the 20 measures studied against a quarter in high-income places.
Capacity to pay is not a moral failing. It is a discount rate.
The Business Model Angle
Take McKinsey’s headline number and turn it into something a credit committee can price.
Every dollar spent on proven measures like cooling, irrigation and sea dikes avoids three dollars in damages on average, rising to seven to one at 2°C of warming. McKinsey also notes that many of these measures take a decade or longer to implement and have lifetimes of multiple decades.
A benefit-cost ratio is undiscounted. Spread three dollars of avoided damage evenly across a 30-year asset life and you get ten cents a year against one dollar of capital, which is an internal rate of return of 9.31% and an undiscounted payback of exactly ten years. Shorten the life to 20 years and the return climbs to 13.89%. Stretch it to 40 and it drops to 7.00%.
Now put the borrowers next to it.
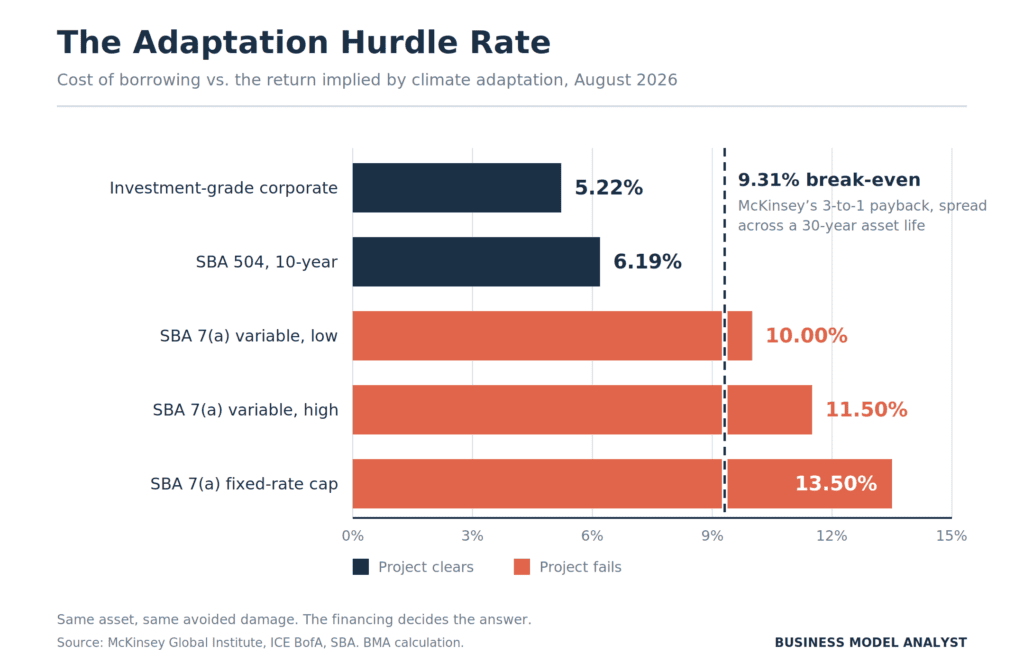
The break-even sits at 9.31%, which lands between the two credit classes. Climate adaptation is priced almost exactly on the line that separates who can finance it from who cannot. With the WSJ prime rate at 6.75% through mid-2026 and SBA 7(a) maximums running from 9.75% to 14.75% depending on size and term, that line runs straight through the middle of American small business.
The same asymmetry shows up in cash. Borrow $30,000 over ten years and an investment-grade issuer pays about $8,572 in interest. An SBA 7(a) borrower at 11.5% pays about $20,614. Two and a half times the financing cost for identical steel. The climate does not discriminate between those two buyers. The credit market does, and the credit market is the binding constraint.
Three structural consequences follow.
First, adaptation raises minimum efficient scale. Generator pricing guides make the mechanism explicit: installation costs run proportionally high for small units because permitting, concrete work and electrical integration do not shrink with the generator. Fixed costs that refuse to scale down are the textbook definition of a scale barrier, and they now sit in front of a capability every business needs. Carry a $35,000 asset against $1 million of revenue and it eats 0.69% of the top line. Carry it against $10 million and it costs 0.07%. The cost is the same. The burden differs by a factor of ten.
Second, insurance becomes the enforcement mechanism rather than the safety net. Brokers heading into 2026 describe commercial property as more competitive for well-protected, non-catastrophe risk while older buildings, habitational risks and high-catastrophe zones stay difficult and carry higher deductibles and sub-limits. That is not a market retreating. That is a market sorting. Underwriters are now the parties deciding which adaptation capex gets rewarded, which converts a discretionary investment into a condition of coverage, which converts it into a condition of holding a mortgage.
Third, and the part worth building a business on: the winner is whoever holds the asset. If the identical generator returns 9.31% and one party funds at 5.22% while another funds at 11.5%, there is a 600 basis point spread available to anyone willing to put the equipment on their own balance sheet and sell the output as a service. That is precisely the structure behind Base Power’s $13 billion valuation: install the battery at no hardware cost to the customer, keep the box, sell power below market, and earn grid-services revenue from the aggregated fleet. The customer never faces the hurdle rate. The balance sheet owner arbitrages it.
Adaptation as a product category is capital-intensive and slow. Adaptation as a cost structure conversion, moving resilience from customer capex to vendor opex, is the growth business hiding inside a summer of bad weather.
The Risk
Several things could break this argument, and they deserve stating plainly.
The 30-year assumption carries the whole IRR. McKinsey publishes a benefit-cost ratio, not a uniform asset life, and its 20 measures span air conditioners and sea dikes. Assume a 20-year life and the return hits 13.89%, which clears every rate in the table and dissolves the sorting effect. At 2°C the ratio rises to seven to one, and even on a 40-year life that is a 17.5% return. The hurdle-rate story is strongest for long-lived infrastructure and weakest for equipment that wears out in fifteen years.
Section 179 cuts hard against the interest framing. A US business can deduct the full purchase price of qualifying equipment in year one, with a 2026 limit above $1.1 million, and bonus depreciation may apply on top. For a profitable operator that shifts after-tax economics enough to change the answer. The 9.31% break-even is a pre-tax number and every reader should treat it that way.
Global averages tell you nothing about a specific address. A generator’s return depends on outage frequency at that meter, not on a worldwide mean across four hazards. Hart’s four-outage break-even is arithmetic, not prophecy, and one bad August rewrites it.
Small operators do not finance only through the SBA. Owners use retained cash, personal savings, equipment leases and vendor credit, each carrying a different implicit cost. Some of those are cheaper than 11.5% and some are far worse.
Consolidation is not guaranteed. Franchise systems, equipment-as-a-service vendors and utility programs can all push capital down to small operators, and if they do, the scale advantage compresses rather than compounds. Watch whether resilience-as-a-service reaches independent operators or stops at multi-site chains.
Finally, the commodity channel runs on separate machinery. Heat suppressing egg production at Pilgrim’s Pride, El Niño disrupting harvests and food prices climbing on scarcity are supply-side effects that hit through prices rather than through capital budgets. Our earlier piece on the 2026 El Niño covers that transmission line, and our piece on the European heat wave covers heat as a recurring operating expense. This one is about the capital budget, which behaves differently from both.
Quick Questions
Is the 9.31% figure McKinsey’s? No. McKinsey publishes a three-to-one benefit-cost ratio and notes multi-decade asset lifetimes. Converting that into an IRR on a 30-year life is our calculation, and the assumption is ours to defend.
Doesn’t a positive benefit-cost ratio mean the investment is obviously worth making? For a government or a development bank discounting at a social rate, yes. For a private borrower at 11.5%, an undiscounted three-to-one over three decades destroys value. Both statements are true at once, which is why the adaptation debate keeps talking past itself.
Why does the cost of capital matter more than the cost of the equipment? Because equipment prices are close to identical for every buyer and financing costs are not. The spread between an investment-grade issuer and an SBA 7(a) borrower is wider than most of the equipment discounts available anywhere in the market.
What should a small operator do with this? Stop benchmarking against the payback numbers in consultancy reports and start benchmarking against your own borrowing rate. Then ask whether someone will own the asset for you. The vendor financing the box is often selling a lower hurdle rate, and that is worth more than the hardware.
Where does this go next? Toward balance sheets. The margin in climate adaptation will accrue to insurers writing risk-based terms, to utilities running behind-the-meter programs, and to operators who own equipment and sell availability. Grid costs are already being reallocated toward whoever can absorb them, and resilience will follow the same path.
The Business Model Analyst Take
Climate adaptation has been framed as an awareness problem for a decade. Businesses did not understand the risk, so they underinvested. That framing survives because it flatters everyone: consultants get to sell education, executives get to announce commitments, and the underinvestment stays unexplained.
The numbers point somewhere less comfortable. Businesses understand the risk. Hart knows what a generator does. Corona knows what her electricity bill did. They are not confused about the weather. They are constrained by the terms available to them, and the terms available to them price a 9.31% project as a loss.
That makes climate adaptation a sorting mechanism operating on cost of capital, running underneath what looks like a story about heat. Firms that borrow cheap will buy resilience, amortize it across volume, and take share from firms that cannot. Firms that cannot will keep buying dry ice, which works until the year it does not.
For anyone building rather than reporting, the opportunity is the spread itself. Six hundred basis points sit between the two hurdle rates in the table above, on an asset class that regulators, insurers and lenders are all about to make mandatory. Whoever underwrites the small operator’s resilience, holds the equipment, and bills for uptime captures that spread. Environmental risk is already sitting in operating budgets under other labels. The next move is putting the asset that fixes it on somebody else’s balance sheet.
The bakery does not need a generator. It needs a landlord for one.