
Cintas rents work clothes to more than a million businesses and turns that into a 23.1% operating margin. Two direct competitors run near-identical trucks on near-identical routes and earn 7.6% and 2.4%. The gap explains what the business model really is.
Cintas closed fiscal 2026 on May 31 with revenue of $11.26 billion, up 8.9%, and operating income of $2.61 billion. Its market value sat near $81.5 billion in late August 2026. That puts a company built on picking up dirty shirts in the same valuation neighborhood as household software names.
The obvious explanation is scale. It is also wrong, or at least incomplete. Vestis, the uniform business Aramark spun off in 2023, runs routes that generate almost exactly as much annual revenue as a Cintas route. The money shows up somewhere else.
The Cintas business model
What it is: A route-based B2B rental and replenishment model. Cintas keeps ownership of the garments, mats, mops and towels its customers use, launders and replaces them on a weekly cycle, and bills a recurring per-item fee under multi-year service agreements.
How it earns: Revenue is contracted and recurring. Profit comes from stacking additional products and services onto delivery stops the driver already makes, where the truck, the driver and the fuel are already paid for.
Who pays: More than one million business customers across manufacturing, food service, healthcare, hospitality, retail, automotive and government.
What it owns: About 12,500 delivery routes, 496 facilities, 24,500 vehicles and roughly 48,100 employees as of May 31, 2026.
Segments: Uniform Rental and Facility Services, First Aid and Safety Services, plus Fire Protection Services and Uniform Direct Sale reported under All Other.
Where the $11.26 billion comes from
Cintas reports three revenue buckets. The largest one carries the company name, which is part of why so many descriptions of Cintas stop there.
| Reported line | FY2026 revenue | Share of total | Growth |
|---|---|---|---|
| Uniform Rental and Facility Services | $8,621.6M | 76.5% | +8.1% |
| First Aid and Safety Services | $1,391.9M | 12.4% | +14.3% |
| All Other (Fire Protection, Uniform Direct Sale) | $1,251.3M | 11.1% | see below |
| Total | $11,264.8M | 100% | +8.9% |
On the July 15, 2026 earnings call, management broke the rental segment down further. In the fourth quarter, uniform rental accounted for 47% of that segment. Dust control took 20%, hygiene services 16%, linen 11%, shop towels 3% and catalog sales 3%.
Apply that mix to the full-year segment figure and the picture changes.
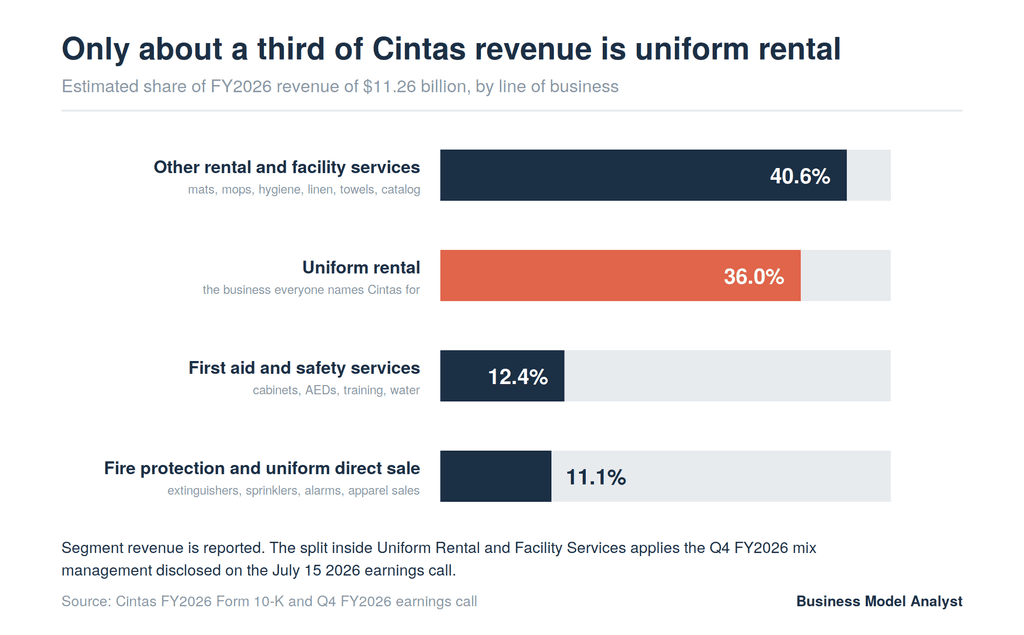
Uniform rental works out to roughly $4.05 billion, or about 36% of company revenue. Nearly two thirds of what Cintas sells has nothing to do with renting a shirt. The uniform gets the contract signed and puts a truck on a weekly schedule. Everything else rides along.
The route is the asset
Vestis makes the comparison possible because it discloses the same operating units. Its fiscal 2025 Form 10-K reports about 3,300 routes, 325 facilities and roughly 18,150 employees against $2.73 billion of revenue.
Divide revenue by routes and the two companies land close together.
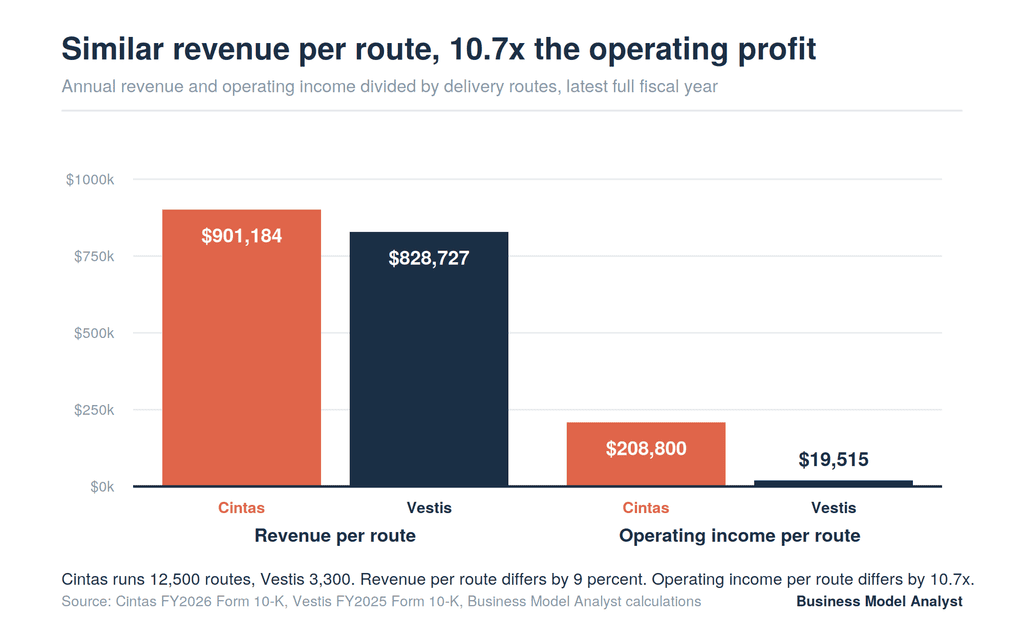
A Cintas route collects 8.7% more revenue than a Vestis route and drops 10.7 times as much operating profit. Route density, the explanation most write-ups reach for, does not survive that arithmetic. Both companies fill their trucks to a similar dollar level.
Two things separate them. Cintas gets 55% more revenue per employee, so it moves the same volume of goods with fewer hands. And it puts higher-margin items on the truck.
Cross-sell is the margin engine
Cintas discloses gross margin by business line each quarter. The fourth quarter of fiscal 2026 lays out the hierarchy.
| Business line | Q4 FY2026 gross margin | Q4 FY2026 organic growth |
|---|---|---|
| First Aid and Safety Services | 57.9% | +13.2% |
| Fire Protection Services | 50.8% | +10.7% |
| Uniform Rental and Facility Services | 50.2% | +7.9% |
| Uniform Direct Sale | 42.0% | -4.0% |
Read the table in order and the strategy reads itself. The one line where Cintas sells a garment outright, collects once and walks away carries the worst margin and the only negative growth number. The lines that put a recurring service on an existing stop grow fastest and earn most.
First aid and safety added $173.8 million of revenue in fiscal 2026 at a gross margin nearly eight points above the core rental business. A first aid cabinet restock takes a driver perhaps four minutes at a building he already visits every week. The incremental cost of that stop is close to the cost of the goods, which is why the margin sits where it does.
Fire protection carries a similar shape, and Cintas has been building it out. Management flagged an SAP implementation in fire during fiscal 2027 that will cost the segment roughly 100 basis points of margin for the year.
Two thirds of new customers came from nobody
On the same call, management said about two thirds of new customers had been handling the work themselves before signing.
That reframes the competitive question. Cintas does not primarily win accounts from UniFirst or Vestis. It wins them from a supply closet, a washing machine in the back and an office manager who orders mats from a catalog. Cintas CFO Mike Hansen said in 2016 that more than 600 operators competed in uniform rental across the United States and Canada, and that customers also had the option of buying direct. The fragmented tail and the do-it-yourself option are the real market.
That matters for the merger case, and it matters for the growth ceiling. As long as small and mid-sized employers keep outsourcing chores they used to do in-house, the addressable pool refills without Cintas taking a single account from a rival.
The capital hides in working capital
Cintas spent $395.1 million on capital expenditures in fiscal 2026, or 3.5% of revenue. For a business running 24,500 vehicles and 496 plants, that number looks implausibly light.
The reason sits one line up on the balance sheet. Cintas carries a separate current asset called uniforms and other rental items in service, which stood at $1.24 billion as of February 28, 2026 against $1.14 billion at the prior fiscal year end. Garments, mats and mops in customer hands are inventory, not equipment. Cintas amortizes them on a straight-line basis through cost of sales rather than depreciating them below the gross margin line.
So the capital intensity of the model shows up in gross margin, which is exactly where management points. Cintas attributed its fiscal 2026 gross margin improvement to more efficient use of in-service inventory. Translated: getting more weeks of billing out of each garment before it goes to rag.
Fiscal 2026 gross margin hit 50.7%, an all-time high, up from 50.0%. That 70 basis point move on $11.26 billion is worth about $79 million, and it came from squeezing the life cycle of cloth.
One industry, three margins
Put the three public route operators side by side using each one’s most recent full fiscal year.
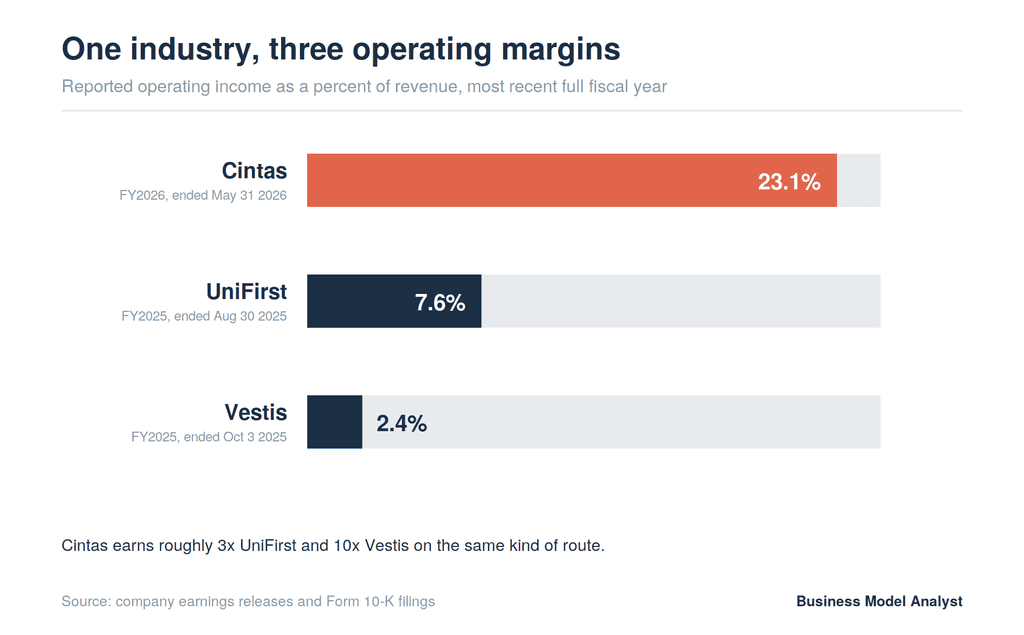
UniFirst grew 0.2% in fiscal 2025 and 2.1% excluding an extra week. Vestis shrank 2.5%, posted a $40.2 million net loss and finished the year at 4.72x net leverage, close enough to its 5.25x covenant to constrain reinvestment. Both companies run the same physical process Cintas runs.
Uniform rental is not a business model that confers margins. It is an execution ladder, and Cintas sits three rungs above everyone else on it.
The UniFirst deal is a bet on that gap
Cintas agreed on March 10, 2026 to buy UniFirst for $310.00 per share, made up of $155.00 in cash and 0.7720 Cintas shares, valuing the enterprise at roughly $5.5 billion. Cintas had tried twice before, in 2022 and again in December 2025 with a public $275 all-cash proposal that UniFirst rejected. The Croatti family, holding about two thirds of UniFirst’s voting power, signed a support agreement this time.
Cintas quoted the price at 8.0x run-rate trailing twelve-month EBITDA including about $375 million of operating cost synergies. Back the synergies out and the arithmetic gets interesting.
UniFirst reported a 13.8% adjusted EBITDA margin on $2.432 billion in fiscal 2025, or roughly $336 million. Against $5.5 billion of enterprise value, that is about 16.4x for the business as UniFirst runs it. The quoted 8.0x depends entirely on Cintas delivering the synergies.
Now size those synergies against UniFirst’s own P&L. Add $375 million to UniFirst’s $184.5 million of fiscal 2025 operating income and you get $559.5 million on $2.432 billion of revenue. That is a 23.0% operating margin. Cintas ran 23.1% in fiscal 2026.
Cintas is not paying for UniFirst’s revenue. It is paying for the right to run $2.4 billion of revenue at its own margin, and the synergy number is the difference between the two companies’ execution, priced and put in a press release. The bases are not identical, since run-rate EBITDA differs from a reported fiscal year and the savings will come from both sides of the combination. The magnitude still tells you what the deal is.
Cintas expects the transaction to be accretive to EPS by the end of the second full year after closing, with synergies realized within four years, and pro forma leverage near 1.5x debt to EBITDA at close. It has not modeled near-term revenue synergies.
The Risk
Antitrust. The FTC issued a second request on June 11, 2026, the day before UniFirst shareholders approved the deal. Cintas still guides to a close in the second half of calendar 2026. The precedent cuts in Cintas’s favor: the FTC issued a second request on the $2.2 billion G&K Services acquisition in September 2016 and cleared it with no divestitures in March 2017. The enforcement posture and the local-market math have both moved since. Third-party antitrust analysts have estimated the combined company would hold 45% to 50% of the North American uniform rental and facility services market, with concentration concerns focused on individual metros rather than the national picture. UniFirst’s nuclear and cleanroom garment operations are a further complication, since few buyers exist for a divested specialty unit.
Headcount exposure. Cintas bills per garment per employee per week. When a customer cuts blue-collar staff, revenue falls with no price offset. That is the cyclicality inside a business that otherwise looks like a subscription.
Integration. Cintas has never absorbed anything this size. G&K was one fifth the revenue. A combined 1.5 million customers across two route networks, two plant footprints and two ERP environments is a different problem, and management already flagged one SAP rollout costing fire protection 100 basis points in fiscal 2027.
Input costs. Energy costs rose about 20 basis points year over year in the fourth quarter. Cotton, polyester, fuel and healthcare claims all sit inside a gross margin that management has been grinding higher a few basis points at a time.
Quick Questions
Is Cintas a subscription business? Functionally, yes. Revenue is contracted, recurring and billed weekly under multi-year agreements. The mechanics differ from software because Cintas retains ownership of a physical asset it must launder, repair and replace, which is why the model looks more like the subscription business model crossed with equipment rental.
Does Cintas make money on the uniforms themselves? Less than the name suggests. Uniform rental is about 36% of revenue, and Uniform Direct Sale, where customers buy garments outright, carries the lowest gross margin in the company at 42% and was the only line to shrink in the fourth quarter. The garment functions as the entry product in something close to a razor and blade structure, where the recurring service is where the profit sits.
How big is Cintas compared to its competitors? Cintas generated $11.26 billion in fiscal 2026 against UniFirst’s $2.43 billion and Vestis’s $2.73 billion. Combining Cintas and UniFirst would produce roughly $13.7 billion of revenue on current figures and about 1.5 million business customers.
What is the biggest threat to the model? Employment in the industries Cintas serves. Every other risk is manageable at 23% margins and 1.5x pro forma leverage.
Who runs Cintas? Todd Schneider is CEO. Jim Rozakis became President and Chief Operating Officer on August 1, 2026, when the company split the President and CEO roles. Scott Garula serves as Executive Vice President and Chief Financial Officer.
The Business Model Analyst Take
Strip Cintas down and you find a distribution network wearing a uniform company’s name. The weekly stop is the asset. The garment is what persuades a facilities manager to accept a weekly stop in the first place.
Once that truck has a standing appointment, Cintas gets to sell mats, mops, restroom supplies, first aid cabinets, AEDs, safety training, fire extinguisher inspections and sprinkler service into a stop whose marginal cost is already sunk. That is why first aid grows at 13% with a 58% gross margin while the garment sale business shrinks at 42%.
The UniFirst price tells you Cintas knows this. The $375 million synergy number is not a cost-cutting estimate in any ordinary sense. It is the measured distance between how Cintas runs a route and how UniFirst runs one, converted into dollars and handed to UniFirst shareholders as a premium. If the FTC lets it through, Cintas buys 3,000-odd routes it can immediately run better, and it does so in a market where two thirds of new customers are still doing the work themselves.
The thing to watch is not the merger. It is whether cross-sell attach rates hold as the customer base gets larger and more mid-market. Cintas has compounded revenue for 55 of the last 57 years by adding one more item to the truck. The day that stops working, a 23% margin on a laundry business becomes very hard to defend.