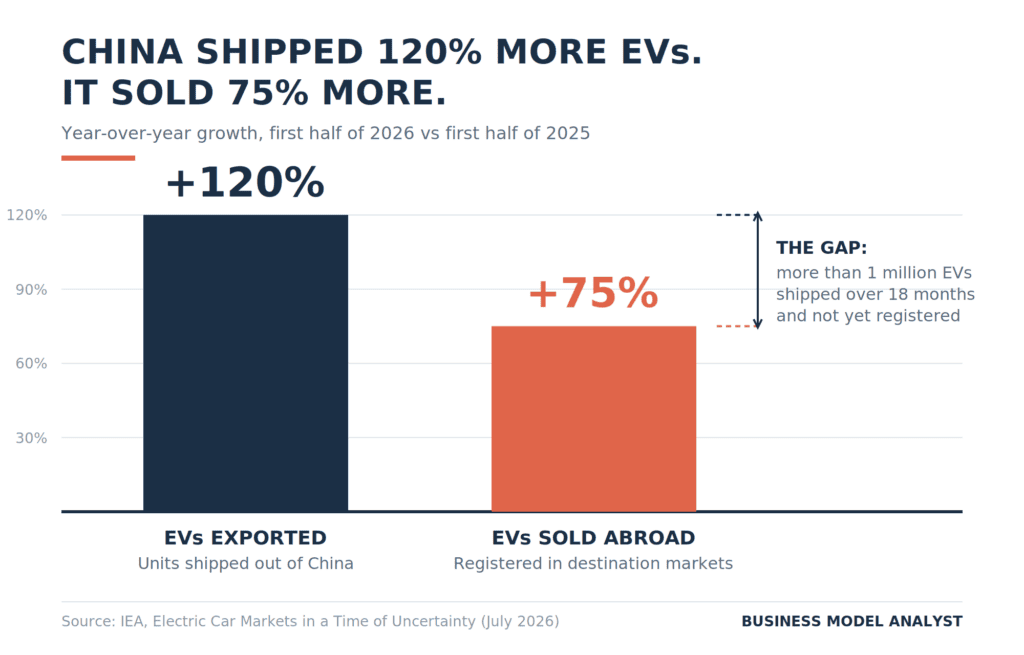
Chinese EV shipments rose 120% in the first half of 2026. Registrations abroad rose about 75%. The difference is more than a million cars sitting somewhere between a Chinese port and a buyer.
China’s EV exports jumped 120% year over year in H1 2026 while overseas sales of those vehicles grew roughly 75%, leaving over 1 million exported units unregistered in destination markets, according to the IEA. High gasoline prices from the Iran war gave Chinese carmakers a reason to ship inventory offshore, but shipping is not selling. The glut moved from Chinese lots to foreign ports, and the fuel-price premium that justified the move is already deflating in the forward curve.
Read the number the way a carmaker’s CFO reads it. An export is a wholesale transaction: the manufacturer books revenue when the car leaves the factory gate for an importer or a distributor, not when a driver in Bogotá signs finance papers. So a 120% export figure tells you how much product left China. It tells you nothing about how much product found an owner.
The IEA published both numbers. Only one of them made the headlines.
What Happened
The Wall Street Journal reported on August 10 that China’s EV makers are the one group hoping the Iran war drags on. Carol Ryan’s piece lays out the mechanics: Chinese carmakers began 2026 with excess EV inventory and soft domestic demand, and high pump prices abroad handed them a demand window. She cites IEA data showing exports up 120% in the first half, EV sales roughly doubling in Brazil, Australia, Korea and Vietnam since the war started, and quadrupling in Colombia.
The share numbers back it up. In June, five Chinese brands (Geely, SAIC Motor, BYD, Chery and Leapmotor) took 12.1% of new-car registrations across the EU and UK, up from 7.7% in the same month last year. Volkswagen, Renault and Ford all lost ground. Volkswagen’s deliveries into China fell 37% year over year in Q2, and its shares now trade at 2011 levels.
CAAM’s own tally for the half: 5.096 million vehicles exported, up 65.3%, of which 2.355 million were new energy vehicles, up 120%.
Now the number the coverage skipped. In the same July report the WSJ drew from, the IEA flags that Chinese electric car exports have outrun overseas sales of those cars, and that more than 1 million EVs shipped out of China over the past 18 months have not yet been registered as sales anywhere. Shipping times explain part of it. The agency says the scale points to inventory building up in destination markets. Its 2025 figure was already ugly: exports exceeded overseas sales by more than 25%.
The Backstory
China built the capacity long before the war gave it an outlet. Gasgoo Automotive Research Institute put national vehicle assembly capacity at 55.5 million units a year by 2024, with more than half of it idle. Industry capacity utilization sat at 73.2% in 2025, under the 75% line most analysts treat as healthy, and joint-venture plants ran at 40% to 60%.
Idle capacity is the most expensive thing a manufacturer can own. Depreciation, debt service and supplier commitments keep running whether or not the line moves, so the pressure to build something and move it somewhere is close to absolute. That pressure produced the domestic price war first. Chinese automakers posted an 18% drop in sector profit in Q1 2026 on an average margin of 3.2%. Xiaomi lost about $457 million on its auto operation in that quarter, close to $5,600 a car.
Then it produced a workaround. Dealers and traders started registering brand-new cars as used and shipping them out through the looser used-vehicle export channel. China’s used-car exports went from 15,000 units in 2021 to 436,000 in 2024, and a consultant to the China Automobile Dealers Association estimated 90% of that 2024 volume was zero-mileage. Beijing moved against it: from January 1, 2026, exporters must obtain manufacturer confirmation that after-sales service exists in the destination country before shipping any vehicle registered within the previous 180 days.
Regulators wrote that rule because carmakers were converting unsold inventory into recorded sales. The IEA’s million-unit gap suggests the conversion trick survived, and moved up the chain from traders to manufacturers.
The Plan
Chinese OEMs are not shipping at random. BYD raised its 2026 export target to 1.5 million vehicles in March, up about 15% from a January target of 1.3 million. Overseas volume hit roughly 45% of BYD’s Q1 deliveries, growing 55% while domestic sales fell. Chery, Great Wall, SAIC and Changan all pushed the same lever.
The logic is margin, not charity. BYD’s 2025 annual report shows a 28.1% gross margin on overseas vehicle sales against 17.2% at home. An Atto 3 lists above $41,000 in Germany and under $20,000 in China. Citigroup estimated BYD’s Chinese vehicle sales would turn unprofitable in Q1 2026, which puts the entire automotive P&L on the export book. The BYD business model is vertically integrated enough to survive a domestic price war, and its overseas price ladder is what funds the survival.
Europe got a second layer of engineering. EU countervailing duties from October 2024 apply to battery electrics only, stacking manufacturer-specific rates on top of the standard 10%: 17.0% for BYD, 18.8% for Geely, 35.3% for SAIC, up to 45.3% on some models. Plug-in hybrids pay the 10% and nothing more. Chinese exporters read the boundary and drove around it. In Q1 2026, Chinese vehicle exports to Europe hit 438,400 units, with BEVs up 94.6% and PHEVs up 152.4%. BYD became Germany’s best-selling plug-in hybrid brand in May with 4,290 registrations. Brussels started drafting PHEV duties in June, having denied any such plan in January.
So the 12.1% EU share figure is not purely an electrification story. A growing slice of it is tariff arbitrage on a powertrain the tariff never covered.
The Business Model Angle
Every industry that has ever channel-stuffed leaves the same fingerprint: shipments growing faster than registrations. Software vendors book bookings that never renew. Consumer brands sell in to retailers who never sell through. Carmakers wholesale to distributors who cannot move the metal.
The mechanic is a working-capital transfer. Finished goods on a manufacturer’s balance sheet are dead cash carrying storage cost and obsolescence risk. Push those units to an importer and three things change at once. Revenue gets recognized. Cash converts from inventory into receivables. The unsold-car risk lands on a distributor who has no pricing power, no brand equity to defend and no service network to fall back on.
For a Chinese OEM in 2026, that transfer is close to irresistible. It rescues plant utilization, feeds a headline export number that local governments reward, and prints a gross margin roughly eleven points better than the domestic one. Every incentive in the system points at the port.
The problem is what the transfer does not do. It does not create a buyer. It relocates the decision about price to a foreign dealer lot, six to twelve months later, at whatever clearing price that lot can find. The manufacturer’s revenue is already booked. The market’s price expectation has not been set yet.
Europe learned this with solar panels. The WSJ makes the comparison and it holds, though the mechanism deserves stating plainly: Chinese solar did not kill European manufacturers with demand. It killed them with the clearing price of surplus. Once a market discovers what a surplus panel costs in a distress sale, no domestic producer ever gets the old price back. Cars carry a second lever solar never had, which is the residual value that underwrites lease and finance offers. A million units clearing at a discount resets used values, and used values set monthly payments across the whole market.
The Risk
The exposure runs in two directions, and the more interesting one points back at China.
Start with the fuel-price assumption. Brent opened 2026 at $61, hit $118 by the end of Q1 after the Strait of Hormuz closed, then fell back to an $85 average in June following the June 18 US-Iran memorandum of understanding. The EIA’s July outlook forecasts Brent at $74 in Q3 2026 and an average of $65 in 2027, with US pump prices around $3.80 a gallon this quarter. ClearView Energy Partners puts the US breakeven for an EV against a combustion car at roughly $4.80 a gallon. Brent traded near $83 on August 7 and lost more than 7% over that week on reports of an Iran-Oman deal to reopen the strait. The demand subsidy is being priced out of the forward curve while the inventory is still on the water.
Now the part that should worry Shenzhen more than Wolfsburg. BYD’s export margin advantage exists because overseas markets are scarce, novel and undiscounted. Dumping a million-unit overhang into those same markets is the fastest available way to destroy it. The sector has one profitable price point, and the glut it just relocated is now sitting directly on top of it.
The steelman cuts the other way, and it is not weak. Manufacturing an EV runs about 35% cheaper in China than in Europe on labor and supply chain alone, and Chinese firms have shown they will accept thin operating margins for years to take share. If clearing a million cars at a discount buys durable position in markets expected to deliver 60% of global car demand over the next decade, that is a rational customer-acquisition cost rather than a mistake. Chinese brands already hold 60% of EV sales across emerging markets against 10% for combustion cars. In Southeast Asia their share of new-car sales went from 4% to 11% between 2023 and 2025 while Japanese brands lost more than 10 points, per PwC.
That defense holds only if the installed base generates an annuity. A first-time car buyer in Cambodia or Colombia is worth owning for twenty years of parts, service, financing and replacement. Owning that customer requires a dealer network, a parts supply and a warranty operation, which is the exact infrastructure Beijing’s own zero-mileage rule was written to force exporters to prove they had. Ship a car without it and you have not acquired a customer. You have created a warranty liability with wheels.
Quick Questions
Is the export surge real or an accounting artifact? Both. The units physically left China, and CAAM’s 2.355 million NEV exports is a real count. Whether they became sales is a separate question the export figure does not answer.
Why does the registration gap matter more than the share number? Registrations record a person taking delivery. Exports record a shipment. A market-share figure built on units still awaiting a buyer describes intent, not position.
Does the war ending kill Chinese EV exports? It removes the running-cost argument, which matters most in markets where fuel is a large share of household income. Sticker-price advantage survives. Payback-period advantage does not.
Who carries the inventory risk? Importers, distributors and dealers in the destination markets, plus anyone financing them. The manufacturer already recognized the revenue.
Which incumbent is most exposed? Toyota and the Japanese brands in Southeast Asia, where share was already sliding before the war. Volkswagen faces the same pressure at home and in China at the same time.
The Business Model Analyst Take
The war did not fix Chinese overcapacity. It gave Chinese carmakers a defensible reason to move the problem offshore and book it as growth, which is a working-capital decision wearing the costume of a strategy.
Watch the gap, not the growth rate. If overseas registrations converge on export volume over the next two quarters, the demand is real and incumbents have a structural problem that no tariff schedule fixes. If the gap widens while oil settles toward the EIA’s $65 forecast, then a million discounted EVs hit dealer lots in markets with no charging build-out, no service depth and no residual-value history, and the first casualty is the 28% overseas margin holding up the entire Chinese auto sector.
Detroit and Wolfsburg are reading the 12.1% figure and preparing to match on price. Ford is already funding a cheap-EV bet out of expensive trucks, and BYD is attacking the premium tier from above with Denza. Matching on price against a competitor clearing surplus is how you lose money for four years and still lose the share. The better response is to compete on the layer the exporters have not built, which is service density, parts availability and residual-value guarantees. Toyota’s business model was constructed around exactly that in the markets now under attack, and the field of Tesla competitors and alternatives is about to get a lot more crowded at the bottom.
Cheap cars are easy to ship. Owning the customer who bought one is the hard part, and nobody has priced that in.