
Beijing never destroyed demand. It spent a stockpile it bought cheap in 2025 and turned a warehouse full of crude into pricing power over Saudi Arabia.
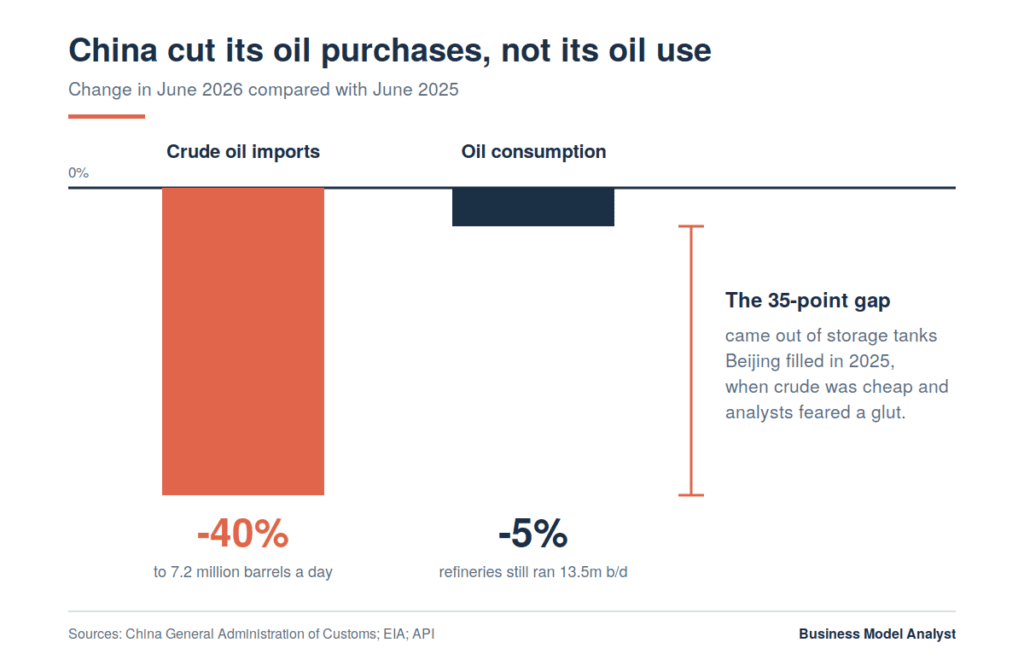
China’s crude imports dropped more than 40% year over year in June 2026, to roughly 7.2 million barrels a day. Its actual oil consumption fell about 5%. The gap came out of storage tanks Beijing filled during 2025, when forecasters were predicting a glut and $50 crude. Holding that inventory bought China something more valuable than the barrels themselves: the ability to stop buying for six months. Gulf exporters responded by cutting their official selling prices to win the business back. For anyone running a business with a concentrated supplier, the leverage math is the same. Your bargaining power equals the number of days you can refuse to place an order.
Brent crude hit $126 a barrel on April 30, during the worst of the Iran war and the near-closure of the Strait of Hormuz. The world’s largest oil importer looked at that price and walked away from the counter.
China’s economy grew 4.3% in the second quarter. Its refineries kept processing crude at 13.5 million barrels a day through May. Chinese drivers kept driving. What stopped was the buying, and traders spent the spring trying to work out how a country could cut purchases by four million barrels a day without anything visible breaking.
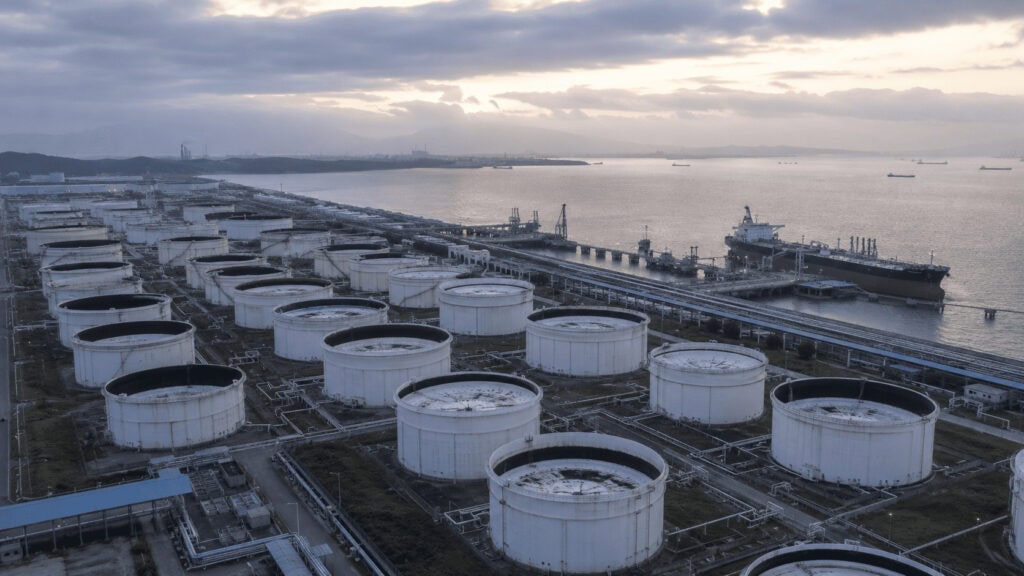
The answer sits in a set of steel tanks scattered across Shandong and Zhejiang, and it should worry every commodity supplier who assumed their biggest customer had no choice.
What Happened
Crude shipments through the Strait of Hormuz collapsed after U.S. and Israeli strikes on Iran escalated in late February. The Middle East supplied 57% of China’s seaborne crude in 2025, according to Kpler, so the exposure was direct and severe.
China imported an average of 11.6 million barrels a day in 2025, per the American Petroleum Institute. By June 2026, arrivals had fallen to about 7.2 million. Imports from Iraq and Kuwait, neither of which has meaningful export capacity that bypasses the strait, went to zero in May.
A single country pulling four million barrels a day out of the market has no precedent outside a global recession, and China was not in one. The Wall Street Journal, reporting the collapse, framed it as proof that Chinese oil demand is discretionary. Kpler’s head of crude analysis put it more colorfully, joking that China has become the OPEC of oil demand.
That reading is half right, and the half that is wrong matters more.
Chinese oil consumption in June fell about 5% against the same month a year earlier, based on EIA figures. Imports fell more than 40%. Demand elasticity accounts for roughly one eighth of the move. The rest is balance sheet.
The Backstory
Rewind to late 2025. Analysts were forecasting $50 oil into year end. Supply was running ahead of consumption, OPEC+ was unwinding cuts, and the consensus trade was short. The glut never arrived, and the reason confused people at the time: Beijing was absorbing between 700,000 and 1.1 million barrels a day of surplus crude and putting it into storage.
Chinese state buyers were the marginal bid holding up a market that everyone else had written off. They took delivery of oil they did not need at prices nobody expected to see again.
By early 2026, China held somewhere between 1.2 and 1.4 billion barrels across strategic reserves, commercial storage, and refinery stocks. Estimates vary by source, but the working number is roughly 100 to 120 days of import cover.
Then the strait closed, and the position that looked like sloppy capital allocation in November turned into the only functioning shock absorber in the global energy market.
Beijing added two administrative levers on top of the inventory. On March 5, regulators told the largest refiners to suspend diesel and gasoline exports, which kept domestic fuel supplied without importing another barrel. Refinery run rates came down where margins justified it. Neither move required a single Chinese consumer to change behavior.
The Plan
The structural piece is real, and it deserves credit even though it is slower than the headlines suggest.
More than half of all new cars sold in China in 2025 were electric. High-speed rail has been eating domestic aviation for a decade. The renewable buildout got large enough that Chinese AI companies were not fighting for grid capacity last year while their American counterparts were signing nuclear contracts. Every one of those shifts trims the baseline.
Those trims are what produced the 5%. They compound, and over ten years they will matter more than any stockpile. Suppliers looking at 2036 should be paying attention to BYD and the rail network, not the tank farms.
Suppliers looking at 2026 should be looking at the tanks.
The strategy Beijing executed this spring is a working capital play, not an energy transition. Buy the input when the market hates it, hold more than you need, and use the position to sit out the panic. China is now building 11 additional storage facilities targeting another 169 million barrels of capacity by the end of 2026, which tells you they intend to run the same play again with a bigger book.
The Business Model Angle
Four decades of operations orthodoxy taught managers that inventory is waste. Toyota built the template, kanban cards and all, and the rest of global manufacturing copied it. Inventory turns became a scorecard metric. Working capital tied up in raw materials became a sin. We covered how badly that model has aged in our piece on the Iran war and just-in-time supply chains, where a survey of more than 500 CEOs at companies above $500 million in revenue found nearly three quarters would accept a cost increase above 10% to guarantee supply.
China did something sharper than building resilience. It built a negotiating position.
Think about what the stockpile actually is in financial terms. Beijing paid a carry cost through 2025: storage, capital tied up, price risk on a commodity that consensus said was heading to $50. That carry cost is an option premium. The option was the right to not buy oil for six months at any price the market threw at it. Volatility was cheap when they bought it. In April, when Brent printed $126, the option paid.
The payoff shows up in a place most people are not watching. Saudi Arabia, Iraq, Kuwait, and the UAE cut their official selling prices for July and August cargoes. Sellers in a supply crisis, with a chokepoint closed and inventories draining worldwide, lowered prices. They did that because the buyer who sets Asian price discovery was not at the table, and no combination of other buyers could absorb the equivalent volume.
Sellers competing on price during a shortage is not how the oil market is supposed to work. The traditional mechanism runs entirely through supply. OPEC sets quotas, U.S. shale adds barrels above roughly $65, and demand takes whatever price results. China inverted it by holding enough inventory to make its own participation optional.
Here is the transferable version for a business with one dominant supplier, whether that is a contract manufacturer, a cloud provider, or a single-source component vendor. Your leverage in that relationship is not your volume. It is not your relationship with their sales team. It is the number of days you can go without placing an order. Just-in-time drives that number to about zero, then calls the result efficiency. No dashboard anywhere tracks “days we could walk away,” and that is the only procurement metric that determines what price you pay in a crisis.
The Risk
Three things could break this reading, and BMA readers should hold all three.
The buffer is finite and the rebuild will be violent. Kpler estimates China can suppress imports for about six more months at the current drawdown rate, which would still leave close to 1.1 billion barrels in storage. Inventories sat at 1.07 billion in early 2025 when Beijing announced its stockpiling drive, so that number may be the floor that sends Chinese buyers back to the spot market. When they return, they will be replenishing reserves and filling 169 million barrels of new tank capacity at the same time. Analysts expect Chinese buying to resume in volume once crude approaches $60. The demand was deferred, not destroyed, and it comes back with interest.
The option premium is expensive and most companies cannot pay it. China spent a decade and state capital building reserve infrastructure that no public company could justify to shareholders. A CFO who proposes holding six months of input inventory will be explaining the return on invested capital hit for the next four earnings calls. The strategy is correct and the incentive structure punishes it. That gap is the actual reason few firms will copy this.
Storage only works on storable inputs. You cannot stockpile fab capacity, GPU allocation, specialized labor, or regulatory approval. For businesses whose critical input is a service rather than a physical good, the leverage math needs a different answer, usually a second qualified supplier carried at a cost premium.
Brent traded near $87 on July 28, up sharply over the past month even with China absent. That move tells you the market is already pricing the return.
Quick Questions
Did China’s oil demand actually collapse? No. Consumption fell about 5% year over year in June while imports fell more than 40%. Refineries kept running at 13.5 million barrels a day through May. The import drop reflects a switch from stockpiling to drawing down stockpiles.
How long can China keep this up? Kpler’s estimate is roughly six more months at the current drawdown rate. The Baker Institute puts practical working runway closer to 60 to 90 days before refiners would cut runs to protect minimum stocks. The range reflects genuine disagreement about how much of the reserve Beijing considers usable.
Why did Gulf producers cut prices during a supply crisis? Saudi Arabia, Iraq, Kuwait, and the UAE set monthly official selling prices for term contracts by region. With the largest Asian buyer sitting out and no alternative buyer able to absorb similar volume, those producers cut prices to encourage China back into the market.
Does this mean oil prices stay low? The opposite risk is larger. OECD commercial inventories have been drawing down since the conflict started, and the U.S. Strategic Petroleum Reserve sits near its lowest level since 1984. China’s absence has capped prices so far. Its return removes the cap.
What should a mid-sized business take from this? Calculate how many days you could operate without ordering from your largest supplier. If the answer is under two weeks, you have no negotiating leverage in a disruption, whatever your contract says.
The Business Model Analyst Take
The oil industry priced itself for a century on one assumption: the customer has to buy. Refineries need feedstock, cars need fuel, and demand shows up regardless of price. Every quota decision OPEC ever made rested on that.
China spent 2025 quietly buying the right to violate that assumption, then exercised it in April.
Calling this demand elasticity, as the market has, gives Beijing too much credit and misses the mechanism. Chinese consumption barely moved. What moved was the decision about when to buy, and that decision belongs to a state that can hold a billion barrels on its balance sheet and ignore quarterly return metrics. Most buyers cannot replicate that. The ones who can, or who can get partway there, will discover that supplier pricing power has always been a function of buyer desperation rather than seller scarcity.
Watch for the copycats. Imports of electric vehicles and solar panels have surged across Southeast Asia since the war started, which suggests governments are already drawing the same conclusion about long-term exposure. The faster and cheaper version of Beijing’s play is the boring one though: buy the input when nobody wants it, hold more than the textbook allows, and price the option value of being able to say no.