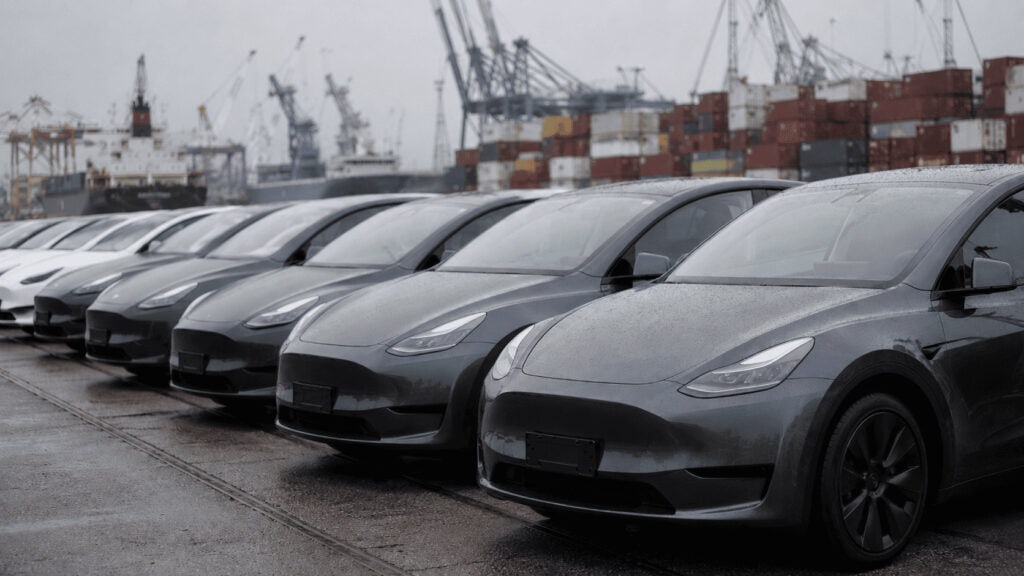

Europe is hooked on cheap Chinese goods, and breaking the habit could get ugly.
Europe is inching toward a trade war with China as a wave of cheap imports, especially electric vehicles, threatens its factories. Beijing’s export push, fueled by subsidies and a weak home market, helped drive a roughly $418 billion EU goods trade deficit in 2025, with imbalances hitting record levels in early 2026.
Picture a Volkswagen plant in Emden, Germany, the spiritual home of the affordable car, where the line keeps moving but the math no longer works. A few hundred miles west, shoppers in Angers, France, are lining up for a Shein store. Same continent, two very different moods. One side is trying to compete. The other just wants the discount.
What Happened
Brussels is openly nervous. The EU’s top diplomat compared cutting Europe’s China dependence to chemotherapy: necessary, and painful. One think tank director summed up the mood in a single word: “panic.”
The trigger is volume. In the first quarter of 2026, Chinese imports into Europe jumped sharply, with the trade imbalance hitting record levels as electric vehicles poured in. China is now the EU’s second-largest goods trading partner, behind only the United States, and European leaders are scrambling for a “more robust and coherent response.”
The Backstory
This didn’t come out of nowhere. After a property crisis hammered China’s economy, Beijing leaned harder on manufacturing as its growth engine, backing factories with subsidies and support programs. Then US tariffs made selling into America harder, so those factories pointed their excess output at the next big wealthy market: Europe.
The timing was brutal for European carmakers. Chinese EV makers were already battling weak demand at home, so they pushed into Europe right as European drivers were switching to greener cars amid higher fuel prices. Cheap, abundant supply met rising demand. For consumers, great. For German auto and chemical giants, less so.
The Plan
Europe’s counter is starting to take shape. The proposed Industrial Accelerator Act aims to rebuild the bloc’s manufacturing base, and it’s designed to effectively shut Chinese companies out of certain key subsidies, giving European-made EVs a leg up. France has pushed for tools to protect strategic industries, and France, Italy, Spain, Lithuania, and the Netherlands drafted a paper urging a tougher response, taking aim at trading partners with “systemic and structural industrial overcapacity.”
Beijing’s reaction? It called the plan protectionist and warned it will hit back. It has leverage, too. Last year China twice halted exports of rare-earth minerals and magnets, materials Europe needs for high-tech and green energy. In April, it introduced rules letting officials inspect corporate records and even block executives from leaving the country if they’re seen helping move supply chains out. The European Chamber of Commerce in China warned the move could inflict unprecedented damage on Europe’s economy.
The Business Model Angle
Strip away the geography and this is a story every operator should recognize: what happens when a competitor builds a cost structure you literally cannot match.
China’s edge isn’t magic. It’s scale, vertical integration, and state support stacked on top of each other until the per-unit cost falls below what rivals can survive. When a low-cost player has surplus capacity and a soft home market, they export the glut, and prices crater across the whole category. Incumbents who built their moat on brand and engineering suddenly discover that price is a moat too, and they’re on the wrong side of it.
The second lesson is sharper: concentration is a hidden liability on your balance sheet. Europe didn’t just buy cheap goods. It quietly outsourced control of critical inputs like rare earths to a single supplier. That feels efficient right up until that supplier turns the tap into a negotiating tool. If one vendor can halt your production with a policy memo, that’s not a supply chain. That’s a leash. Smart founders price that risk in before it bites, not after. If you want more on how cost structure and dependency shape competitive strategy, the Business Model Analyst blog digs into these patterns regularly.
The Risk
Here’s the honest counterpoint: Europe’s cure might hurt as much as the disease. Consumers are addicted to cheap Chinese EVs and fast fashion, and voters rarely thank politicians for making popular products pricier. The bloc’s 27 members don’t move fast or speak with one voice, and businesses are genuinely afraid of retaliation that could choke off the rare earths they still depend on.
There’s also a credibility gap. The EU has already tried, and failed, to stop the EV flood once. Tariffs and subsidy walls can buy time, but they don’t fix the underlying cost gap, and they risk inviting a tit-for-tat spiral that leaves European firms worse off. As one observer put it, Beijing’s read is that Europe’s “best friend forever” in Washington is distracted, so this is a bad moment to pick a fight. Acting tough is easy in a press release. Following through without blowing up your own supply chain is the hard part.
Quick Questions
Why is Europe fighting with China over trade?
Cheap Chinese goods, especially electric vehicles, are pouring into Europe and undercutting local manufacturers. With a roughly $418 billion goods trade deficit in 2025 and record imbalances in early 2026, Europe sees a threat to its own factories and jobs.
Why are Chinese EVs so cheap?
A mix of scale, government subsidies, and support programs, plus a weak home market that left carmakers with surplus cars to sell. When US tariffs made America harder to crack, those exports flowed to Europe instead.
What are rare-earth minerals and why do they matter?
They’re materials used in high-tech and green-energy products. China dominates supply, and last year it twice paused exports of rare earths and magnets, showing Europe just how dependent it had become.
What is the Industrial Accelerator Act?
A proposed EU policy to rebuild Europe’s manufacturing base. Its design would effectively block Chinese companies from some key subsidies, giving European-made EVs an advantage. Beijing has already called it protectionist.
The Bottom Line
Cheap competition and convenient dependency feel like wins until the moment they don’t. The lesson for founders and operators is the same one Europe is learning the expensive way: know exactly where your cost disadvantages and single points of failure live, and build the buffer before someone forces the issue. Efficiency that you can’t control isn’t a strength. It’s exposure waiting to be exploited.
Based on reporting from The New York Times.