
Rival Chinese labs have run an unpriced R&D pool since 2023. Z.AI and MiniMax are already listed, Moonshot wants Hong Kong within six months, and DeepSeek is aiming at Shanghai. Shared research rarely survives a share price.
Chinese AI labs closed the capability gap on roughly one-fifth of the capital and one-fifth of the high-end chips their American rivals had. The explanation is not a national talent secret. Four companies that compete for the same customers have been handing each other their best engineering work for free, which cut every participant’s private research bill. Economists named this arrangement in 1983 and documented how it ends. It ends when one of the sharers gets big enough to keep the returns. In 2026 all four Chinese labs either listed or filed to.
Tang Jie taught Yang Zhilin at Tsinghua more than a decade ago. Tang now co-founds Z.AI. Yang runs Moonshot AI. Both companies are worth tens of billions of dollars, both sit months behind the American frontier rather than years, and both are accused by Anthropic of large-scale distillation of its models. The Wall Street Journal used those biographies to explain how China caught up. The biographies are the least interesting part. The interesting part is what these men do with the techniques they invent, which is publish them where their competitors can take them.
What Happened
The Journal reported this week on the Tsinghua lineage behind China’s frontier labs, tracing Z.AI, Moonshot and their peers back to a single university lab and a 2018 rule change that let state researchers commercialize their work. Tang spun Z.AI out of his Tsinghua lab in 2019, funding it in part with a data-analytics platform whose clients included Google and IBM.
Buried in the piece is a two-way technical exchange between direct competitors. DeepSeek developed multihead latent attention, which compresses what a model has to hold in memory during a conversation and cuts the compute bill. DeepSeek was also among the first Chinese labs to adopt mixture-of-experts routing, where a dispatcher sends each problem to a specialist sub-model rather than waking the whole system. Moonshot then built both into Kimi K2 and K3. DeepSeek turned around and adopted a training-efficiency technique Moonshot had optimized.
Neither company paid for the exchange. Neither signed anything. DeepSeek founder Liang Wenfeng, asked by investors in May how he expects to make money while giving away his secrets, told them he is not worried about competition because the market is big enough.
Investment bank Jefferies calculated that Chinese tech companies spent under a fifth of what their US counterparts spent through these years. Researchers at Alibaba and Z.AI say they get roughly a fifth of the high-end chips their peers at OpenAI and Google can use. The output of that arithmetic is a capability gap that industry leaders on both sides now measure in months.
The Backstory
Robert Allen published a paper in 1983 on the blast furnace industry of northeast England between 1850 and 1875. Iron producers in the Cleveland district let rivals and consultants walk through their plants, then published furnace heights, blast temperatures and fuel efficiency. Over two decades furnace stacks roughly doubled in height and blast temperatures more than doubled. Almost none of that improvement traces to private research spending, because almost none of these firms did private research.
Allen called it collective invention, and he explained why rational owners behaved this way. Each firm expected to learn more from the pool than it contributed. Withdrawing meant risking the whole arrangement to protect one design that a competitor would reverse-engineer from the outside anyway. Sharing substituted for an R&D budget nobody had.
Alessandro Nuvolari later found the same pattern among Cornish steam engine builders, who published performance data on their pumping engines in a monthly trade report. Eric von Hippel documented it again in the 1980s among American mini-mill steelmakers, who traded process know-how informally with the plants they were bidding against.
Look at China’s AI industry through Allen’s three markers and it matches on all of them. Rivals release design and performance information to each other. Individual firms spend little on private discovery relative to what they ship. The advances are incremental, unpatentable and hard to attribute to one inventor. Add the licenses and the fit gets tighter: DeepSeek publishes under MIT, much of Qwen ships under Apache 2.0, GLM under MIT, Kimi under a lightly modified MIT. These are not marketing choices. They are the legal instrument of a shared pool.
The Plan
Every member of that pool is now walking toward a public market.
Z.AI and MiniMax both listed in Hong Kong in early January 2026. Z.AI raised around $560 million and became the first major Chinese LLM developer to go public. Its shares rose roughly 1,600% by late May, briefly pushing its market capitalization above $112 billion, and above $128 billion in June, before giving back a large share of that. MiniMax doubled on its first day.
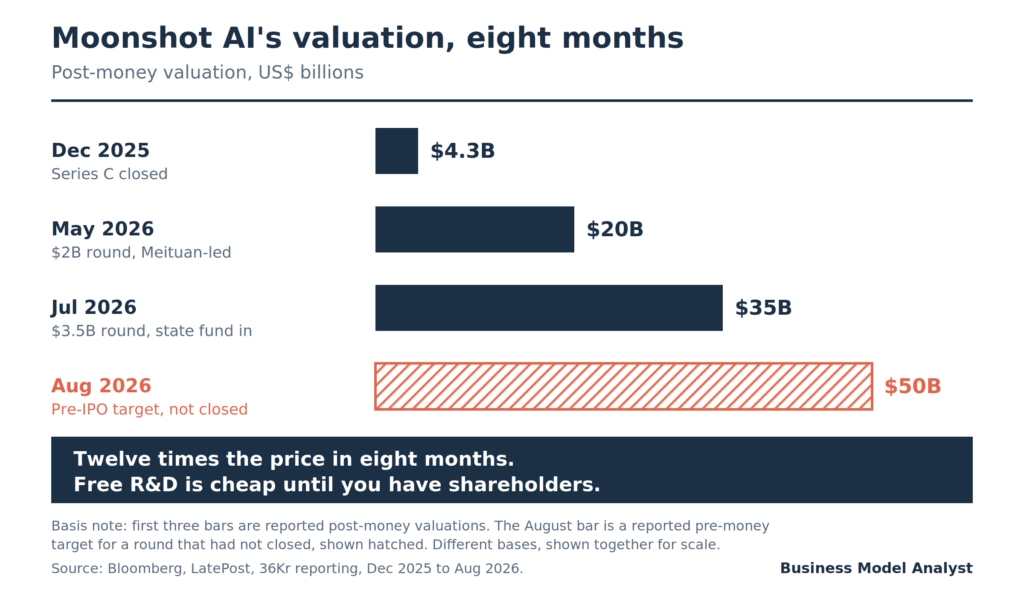
Moonshot has moved faster on the private side. Post-money valuation of $4.3 billion in December 2025, $20 billion after a $2 billion round led by Meituan’s fund in May, $35 billion after a larger-than-planned $3.5 billion round that closed in late July with the state-backed National AI Industry Investment Fund among the leads. Reporting in August put Moonshot in negotiations for a final pre-IPO round at a pre-money valuation up to $50 billion, and the company has circulated a shareholder resolution seeking approval for a Hong Kong listing as early as six months out.
DeepSeek raised $7.4 billion in June in its first outside round at a valuation north of $50 billion, with Liang writing roughly 40% of the check himself. Reports since put it in the market again at up to $71 billion, ahead of a Shanghai STAR Market listing targeted for as early as the second quarter of 2027.
Beijing built the on-ramp deliberately. Nearly half of all equity-capital investment in China went into AI in the first half of this year, most of it from government-backed funds, and regulators loosened listing rules to get these companies public.
The Business Model Angle
A pool works while nobody in it has anything worth defending. That condition expired.
Z.AI crossed $1 billion in annual recurring revenue in July, climbing from $100 million in about five months. Anthropic took roughly fifteen months to walk the same stretch. Z.AI now has a revenue line, a share price, a lock-up expiry behind it and a second listing planned in Shanghai. Moonshot’s ARR sat near $200 million in April and its price tag has moved about twelve times in eight months. DeepSeek, which needed no outside money for years because Liang’s hedge fund funded it, has taken $7.4 billion from investors who will want a return.
Public shareholders do not fund a competitor’s roadmap. That is the whole mechanism. The Cleveland ironmasters shared because they had no research budgets to protect and no equity analysts asking what happened to the money. The regime faded once firms built corporate laboratories and patents became worth filing, which changed the answer to Allen’s core question. Once you expect to lose more by contributing than you gain by receiving, you stop contributing.
Watch what Z.AI does with the weights of its next flagship. GLM-5.3 shipped this month with a claim of parity against Anthropic’s Mythos 5 on cybersecurity. If Z.AI keeps releasing under MIT while carrying a $70 billion-plus market capitalization and a $1 billion revenue line, the pool holds and Allen’s history does not travel. If the license tightens, or the release lags the API by a quarter, or the strongest checkpoint stays inside, the sharing era has a date on it.
The interior of this pool is voluntary. The exterior is not. Anthropic has accused both Z.AI and Moonshot of violating its terms through large-scale distillation, which means part of the input feedstock arrives from a counterparty who can change the rules. Anthropic pulled Fable 5 and Mythos 5 off the market for about two weeks in June under a US export-control directive before restoring access. An input that a foreign government can switch off is not a supply chain. It is a dependency with a good quarter behind it.
The Risk
The cost side moves against these companies at the worst moment. We covered China’s AI labs exiting the price war they started when Moonshot stopped selling Kimi K3 subscriptions because each new customer burned more compute than it paid for. If shared research thins out at the same time, the industry’s aggregate R&D bill rises while its pricing power keeps falling. Zhipu’s 2025 accounts show revenue of 724 million yuan against an adjusted net loss of 3.2 billion yuan. Losses running more than four times revenue leave little room to absorb a research bill that was previously subsidized by rivals.
The volume-versus-revenue split stays brutal. Chinese-origin models have held at least 30% of weekly token volume on OpenRouter every week since February 8, peaking near 46% by mid-year, up from 4.5% in the first half of 2025. On Vercel’s production gateway in June, open-weight models carried 29% of tokens and under 4% of the spending. Traffic without invoices is a distribution position, and we argued in the Africa kill-switch piece that China is winning the interface while America still collects the bill.
Then there is Gavekal analyst Laila Khawaja’s point, which cuts against the whole optimistic reading. Chinese firms chase cost efficiency to its limit. American firms with better chips and a tolerance for burning capital fund exploratory work that produces step changes. A pool is good at closing a known gap. Nobody has shown it is good at opening one.
Quick Questions
Is collective invention the same as open source? Related, not identical. Open-source licensing is the legal wrapper. Collective invention describes the economic behavior underneath, where competing firms release performance and design information because each expects to receive more than it gives. Allen documented it in an industry with no software and no licenses.
Why would DeepSeek help Moonshot beat it? Because Liang’s stated view is that a closed-model moat does not last long against a technology moving this fast, and that the market is large enough to absorb several winners. Both claims look reasonable while the labs are chasing a leader. Neither survives contact with a shrinking market.
Does an IPO actually stop a company from open-sourcing? Not by rule. It changes the question a CFO has to answer in public. Meta open-sources as a listed company because its revenue comes from advertising and its models carry no P&L. Z.AI’s models are its P&L.
Are Chinese models really only months behind? Leaders on both sides say months rather than years, and Z.AI claims parity with Anthropic’s Mythos 5 on cybersecurity for its GLM-5.3 release. Benchmarks and production reliability are different things, a gap we walked through in the piece on a free Chinese model matching a restricted US one.
What does this mean for buyers? Cheap open weights are cheap while the pool holds. Price your dependency on the assumption that the discount narrows, the way the solo founder who moved off Claude had to price his.
The Business Model Analyst Take
Sort your R&D into two buckets. One holds work your competitors will replicate within a year whatever you do. The other holds work only you can own, usually because it sits on a customer relationship, a data asset or a distribution position rather than a technique. Money spent defending the first bucket is money burned, and technical companies burn a lot of it.
China’s AI labs got that sort right. They treated model architecture as an industry-level public good, stopped paying to hide it, and moved their entire competitive budget to price and distribution. It bought them the fastest catch-up in modern industrial history on a fraction of the capital, and BMA readers running a challenger business should copy the logic without the geopolitics.
The second half of the lesson is harder. Pooling is a challenger’s strategy. It stops paying the day you become the firm with the best process and the most to lose, and that moment arrives with a valuation attached. Tang and Yang spent a decade building an arrangement that worked because nobody in it had money. All four members now do. The Cleveland ironmasters got twenty-five years out of theirs before corporate laboratories and patent lawyers ended it. These labs have had three, and the bell has already rung in Hong Kong.