
Ask most people to describe a Chime customer and you will get some version of the same sketch: young, broke, allergic to banks, probably found the app through a TikTok ad. It is a tidy story. It is also several years out of date.
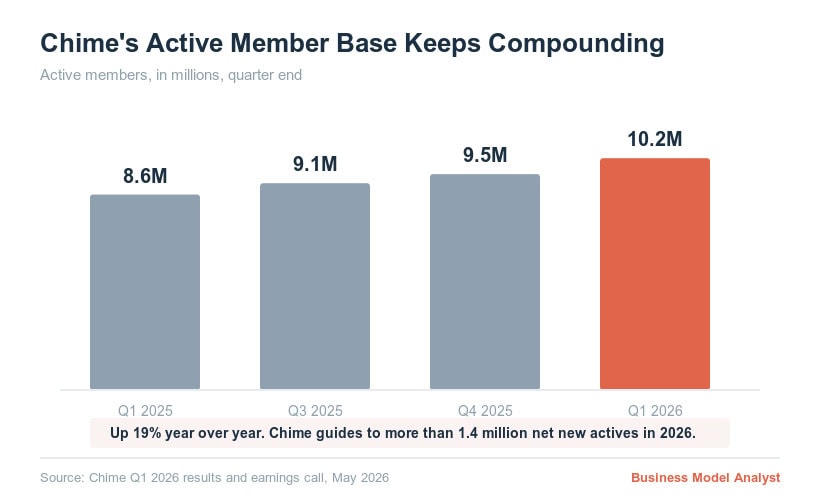
Chime now has 10.2 million active members, went public in June 2025, posted its first GAAP-profitable quarter in Q1 2026, and reports that its fastest-growing income group is people earning $75,000 or more. The average member is 36 years old. Fifty-five percent are women. Two-thirds treat Chime as their primary financial relationship, which is a level of banking primacy most credit unions would trade a limb for.
So the interesting question is not “who is Chime’s target market” in the demographic-sketch sense. It is this: what variable does Chime actually segment on? Because it is not income, and it is not age. It is the paycheck.
Chime’s target market is the roughly 75% of US households earning up to $100,000 per year, served through a fee-free, mobile-only banking model. But the segment that drives Chime’s economics is defined behaviorally, not demographically: members who route a qualifying direct deposit through Chime and make it their primary account. Chime formally defines a primary account relationship as a member with at least one qualifying direct deposit of $200 or more in the past calendar month, or 15 or more purchases on a Chime-branded card in that month.
The distinction matters commercially. Chime does not make money because you are 27 and underbanked. It makes money when your employer’s ACH file lands in a Chime account, because that is what turns you into an interchange-generating, cross-sellable, statistically low-risk borrower.
Chime’s Target Market at a Glance
| Dimension | Definition |
|---|---|
| Core income band | Households earning up to $100,000 per year, about 75% of US households |
| Fastest-growing income segment | Members earning $75,000 or more |
| Average member age | 36 |
| Gender split | 55% female |
| Geography | All 50 states, indexed toward non-urban, lightly banked states |
| Primary-account share | About two-thirds of active members |
| Active members | 10.2 million (Q1 2026), up 19% year over year |
| ARPAM | $263 annualized (Q1 2026) |
| Segment penetration | Under 3% of the target income band |
The Demographic Segment: Not Who You Think
Chime’s public positioning is “everyday Americans,” which is the kind of phrase that means nothing until you look at what it excludes. It excludes the affluent-urban-professional segment that Chase Sapphire and Amex fight over. It excludes small business banking. It excludes anyone whose financial life requires a mortgage officer.
| Demographic variable | Chime’s target |
|---|---|
| Income | Up to $100,000 household income, with growth now strongest above $75,000 |
| Age | Millennials and Gen Z primarily, average member age 36 |
| Gender | Skews female, 55% of members |
| Employment | W-2 employees with regular direct deposit, plus gig and hourly workers with volatile pay cycles |
| Banking history | 85% of new Chime direct depositors arrived with an existing direct deposit relationship, usually at a large incumbent bank |
That last row is the one that quietly kills the “unbanked” narrative. Chime is not primarily converting people from cash into the banking system. It is stealing them from Chase, Wells Fargo, and Bank of America. Chime ranked first in US checking account openings in J.D. Power’s Q1 2026 survey, 50% ahead of the next competitor. This is share-taking, not financial inclusion. The financial inclusion story is the marketing. The bank-switching story is the business.
The Geographic Segment: Where the Branches Are Thin
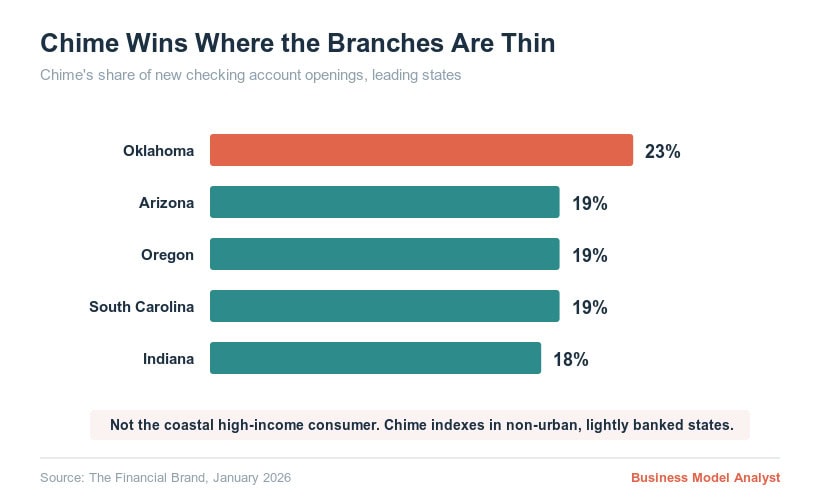
Chime does not index where you would expect a San Francisco fintech to index. Its strongest states for new checking account share are Oklahoma, Arizona, Oregon, South Carolina, and Indiana. Not New York. Not California.
| Region type | Fit with Chime |
|---|---|
| Non-urban and suburban states with thin branch density | Strongest. Chime’s mobile-only model is a feature, not a compromise, where the nearest branch is a drive |
| Large coastal metros | Weaker. Incumbent branch networks and premium card rewards compete harder |
| Rural cash-heavy areas | Served via cash deposits at Walgreens, CVS, Walmart, and 7-Eleven, though this remains friction |
The strategic logic is clean. A branchless bank wins fastest in places where the branch was never much of an advantage anyway. Anyone selling a “we are digital-first” story into Manhattan is fighting the incumbent’s strongest ground.
The Behavioral Segment: The One That Actually Pays
Here is where most analyses of Chime’s target market stop short. They list demographics and call it a day. But Chime’s own disclosures make it obvious that demographics are a proxy, and a loose one. The real segmentation variable is engagement depth.
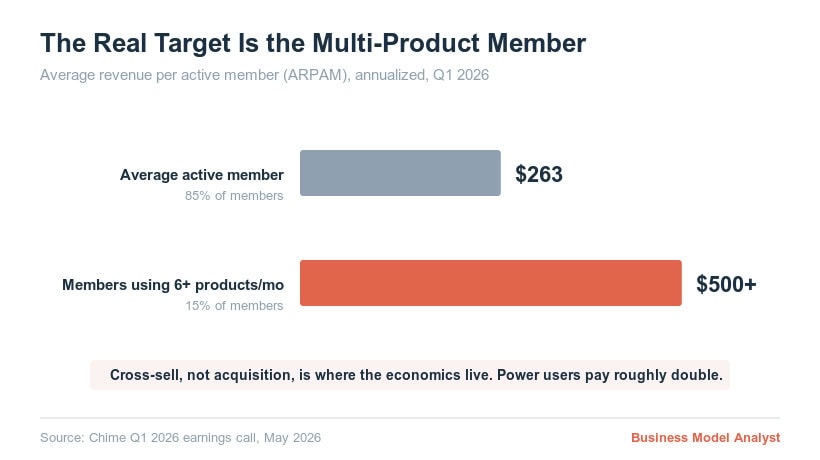
In Q1 2026, Chime’s average revenue per active member was $263 on an annualized basis. But the 15% of members who use six or more Chime products in a month generate ARPAM north of $500, roughly double. Chime’s active members averaged 3.3 products adopted as of March 2025.
| Behavioral tier | Share of members | Annualized ARPAM | What they do |
|---|---|---|---|
| Casual user | Majority | Below average | Card in the wallet, no direct deposit, low transaction count |
| Primary account holder | About two-thirds | Around $263 average | Paycheck lands at Chime, top-of-wallet card spend |
| Power member | 15% | Over $500 | Six or more products, likely MyPay, Instant Loans, Credit Builder, savings |
Roughly 70% of Chime card purchases go to non-discretionary spending like food and fuel. That is the tell. Chime is not competing for your vacation booking. It is competing to be the card you use for groceries, which is lower-margin per swipe but relentlessly repeatable and almost recession-proof in volume terms.
The Psychographic Segment: Fee Rage as a Growth Channel
Chime’s target customer is defined less by aspiration than by grievance. This is a segment that has been overdrafted, that has watched a $4 coffee turn into a $39 charge, and that has concluded, not unreasonably, that traditional banks profit from their worst moments.
| Psychographic driver | How Chime addresses it |
|---|---|
| Fee resentment | No monthly fees, no overdraft fees, SpotMe overdraft coverage up to $200 |
| Paycheck timing anxiety | Early direct deposit, MyPay earned wage access |
| Distrust of institutions | Brand positioning as a technology company on the member’s side, not a bank |
| Credit rebuilding | Credit Builder secured card, no interest, no credit check |
| Financial fragility | Instant Loans with fixed fee structures rather than compounding interest |
Chime commissioned research pitching itself as the top brand for new or switched direct deposit relationships among adults earning up to $100,000, capturing 17% of such relationships. Take company-commissioned surveys with the appropriate salt, but the directional point holds and J.D. Power’s independent data supports it.
The Upmarket Problem Nobody Talks About
Chime’s fastest-growing income segment is now $75,000-plus earners, and in April 2026 it launched Chime Prime, a premium tier for members putting at least $3,000 of qualifying direct deposits through the app each month. The company has openly discussed serving households up to $200,000.
This is a genuinely awkward strategic position, and it deserves more scrutiny than it usually gets.
Chime’s entire brand equity is built on being the anti-bank for people the banks treat badly. Its product suite is optimized for liquidity stress: overdraft coverage, wage access, small fixed-fee loans. Now aim that at a household earning $150,000. What does Chime offer them that Ally, SoFi, or a Chase relationship does not? SpotMe is not a selling point to someone with a $12,000 buffer. MyPay is irrelevant if the paycheck always clears before the bills.
The bull case, which Chime makes explicitly, is that nearly half of Americans earning over $100,000 live paycheck to paycheck, so financial fragility is not confined to low incomes. That is fair. But it requires Chime to sell fragility products to a segment that does not identify as fragile, which is a marketing problem more than a product problem.
The other reading is more cynical and probably closer to the truth: moving upmarket is how you raise ARPAM without raising fees, and a public company that just promised 22% to 23% revenue growth for 2026 needs the ARPAM line to keep moving.
The Untapped Market: Under 3% Penetrated
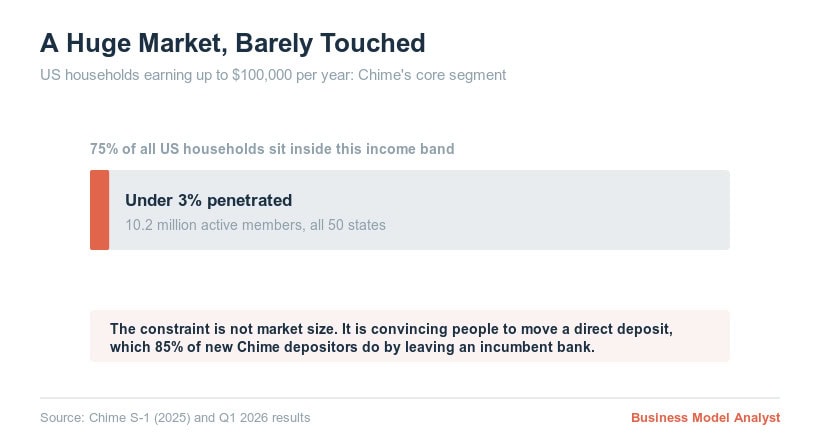
Chime estimates it has penetrated less than 3% of its core income segment. That number cuts both ways.
The bull reading is obvious: a 97% runway inside a group that covers three-quarters of American households. The bear reading is the one worth sitting with. If the product is genuinely this superior and the fee model this favorable, why is penetration still in low single digits after fourteen years?
The answer is switching friction, and it is the single most important constraint on Chime’s target market. Moving a direct deposit means logging into a payroll portal, updating routing numbers, and rerouting autopay. It is boring, it is fiddly, and it is exactly the kind of task people postpone forever. Chime’s customer acquisition cost has run around $124 per member. The bottleneck is not awareness. It is inertia.
Who Chime Is Not For
A target market definition is only useful if it excludes someone.
| Segment | Why Chime does not fit |
|---|---|
| Small business owners | No business banking product of consequence |
| Premium rewards chasers | No competitive travel or points ecosystem |
| Cash-intensive users | Cash deposits require third-party retail locations and can carry fees |
| Complex financial lives | No mortgages, no wealth management, no in-person advisory |
| International users | US-only footprint |
Chime vs the Competitive Set
| Player | Target overlap | Where it diverges |
|---|---|---|
| Cash App (Block) | High. Same income band, same age skew | Started peer-to-peer, layered banking on top. Lower acquisition cost thanks to viral P2P mechanics |
| Varo | High | Holds an actual national bank charter, competes on savings APY |
| Current | High | Skews younger, leans into teen and family accounts |
| Dave | High | Narrower, built around cash advances rather than primary banking |
| SoFi | Partial | Skews higher income and more credit-forward |
| Large incumbent banks | The source of Chime’s growth | Branch networks, full product suites, and the fee income Chime attacks |
Chime’s differentiator inside this set is not the fee model, which everyone copied. It is primacy. Cash App has far more users but a far weaker claim on the paycheck. Owning the direct deposit is what separates a payments app from a bank replacement, and it is the entire strategic thesis. For more on how the pieces fit together, see our full breakdown of the Chime business model and the Cash App business model.
Frequently Asked Questions
Who is Chime’s target customer? Households earning up to $100,000 per year, averaging 36 years old, 55% female, spread across all 50 states with strongest penetration in non-urban, lightly banked states. The members who matter most commercially are those who route their direct deposit through Chime.
Is Chime aimed at low-income customers? Partly, but that framing is increasingly wrong. Chime’s fastest-growing income group is members earning $75,000 or more, and the company has stated ambitions to serve households up to $200,000.
Does Chime target the unbanked? Less than the marketing suggests. Eighty-five percent of new Chime direct depositors came from an existing direct deposit relationship, most commonly at a large incumbent bank. Chime is primarily a bank-switching business.
How does Chime make money from its target market? Mainly interchange fees on card purchases, plus platform revenue from products like MyPay, Instant Loans, and instant transfers. Average revenue per active member was $263 annualized in Q1 2026.
How many customers does Chime have? 10.2 million active members as of Q1 2026, up 19% year over year. Chime defines an active member as someone who initiated a money movement transaction in the last calendar month.
The Business Model Analyst Take
Chime’s target market is usually described in demographic language because demographic language is easy to write. The company’s own numbers tell a different story: the segmentation variable that predicts revenue is not income, age, or credit score. It is whether the paycheck lands.
That reframing has a sharp consequence. Chime is not really in the business of banking underserved Americans. It is in the business of extracting primary account relationships from incumbent banks, one direct deposit at a time, and then monetizing the depth of that relationship through cross-sell. The fee-free positioning is the wedge. The primacy is the product.
Which brings us to the risk. Chime is now a public company with a promised growth curve, a customer acquisition cost of roughly $124, and a base of members whose interchange volume is heavily weighted toward groceries and gas. There are only two levers: more members, or more revenue per member. The first is throttled by switching inertia. The second is what Chime Prime and the $75,000-plus push are really about.
The bet is that Chime can climb the income ladder while keeping a brand built at the bottom of it. Very few financial brands have ever pulled that off. Discover did. Most did not. Watch the ARPAM line and the mix of that $75,000-plus cohort over the next four quarters. That is where you will see whether the upmarket move is working, or whether Chime is a very good business permanently capped by the segment that made it.