Brinker’s CIO killed the robot servers and spent two years on access points, iPads and kitchen screens. The ownership structure explains why that was the correct trade.
Chris Caldwell, chief information officer at Brinker International, told the Wall Street Journal his leadership team agreed Chili’s would not go all in on AI. He spent the budget on Wi-Fi access points in 1,200 restaurants, 23,000 iPads, 9,000 kitchen touch screens and 1,200 manager laptops. Chili’s has now posted 20 straight quarters of same-store sales growth, and Brinker stock has risen more than 500% since Kevin Hochman became CEO in June 2022. The decision reads as caution. It was a read on where Brinker’s money actually compounds: more than 90% of US Chili’s restaurants are company-owned, so a shift-level efficiency gain lands directly on Brinker’s own P&L rather than a franchisee’s.
You have stood in a Chili’s while a server taps at a tablet that will not connect. She apologizes. She walks to the terminal by the bar, waits behind two colleagues, keys the order again. Your appetizer arrives eleven minutes later than it should have. Nothing about that failure requires artificial intelligence to diagnose, and nothing about it gets fixed by a chatbot.
What Happened
Caldwell joined Brinker after more than 20 years at Yum Brands, most recently as CIO of KFC US. His assessment of Chili’s was that the chain had underinvested in basic restaurant technology for years while chasing visible novelties.
He cancelled the robot servers. In their place he ran a two-year network overhaul: new Wi-Fi access points across 1,200 restaurants, a renegotiated Comcast contract, cellular backup, and new fiber lines into locations with weak connectivity. The rollout finished earlier this year.
On top of that foundation he bought 1,200 laptops so each store manager could handle email and inventory without competing for the back-office desktop. He replaced aging server tablets with 23,000 iPads, because the old ones could not hold a charge through a full shift. He added 9,000 kitchen touch screens to help cooks sequence orders and installed tabletop payment devices. The server ordering app, which Caldwell described as cluttered with obscure abbreviations and too many taps per order, is being rewritten.
To win budget approval, he showed the leadership team a video of staff waiting on a spinning loading wheel.
On AI, Brinker’s leadership brainstormed a few dozen use cases and Caldwell kept six or seven worth testing. Inventory forecasting and automated replenishment made the cut. AI phone ordering did not, on the grounds that it would frustrate guests. A governance team now reviews new AI requests monthly and revisits old rejections. Caldwell expects to cut more than he approves. “I don’t expect it to be the Wild West of AI,” he said.
Forrester retail analyst Sucharita Kodali told the Journal she has yet to see a restaurant GenAI use case that changes the game, and that some customer-facing chatbots exist mainly so operators can say they have one.
The Backstory
Hochman took over Brinker in June 2022 with Chili’s losing relevance and unit economics to fast food. He cut roughly a fifth of the menu to speed the kitchen, eliminated fiddly prep tasks, replaced coupon clutter with the $10.99 “3 for Me” platform, and reformulated the baby back ribs and frozen margaritas.
The marketing did the rest. Chili’s positioned itself against fast food directly, launching the Big Smasher and later the Big QP burger, which the chain advertised as carrying 85% more beef than a McDonald’s Quarter Pounder with Cheese. A TikTok video of Triple Dipper mozzarella cheese pulls went viral in the fourth quarter of fiscal 2024 and delivered Chili’s first traffic growth under Hochman.
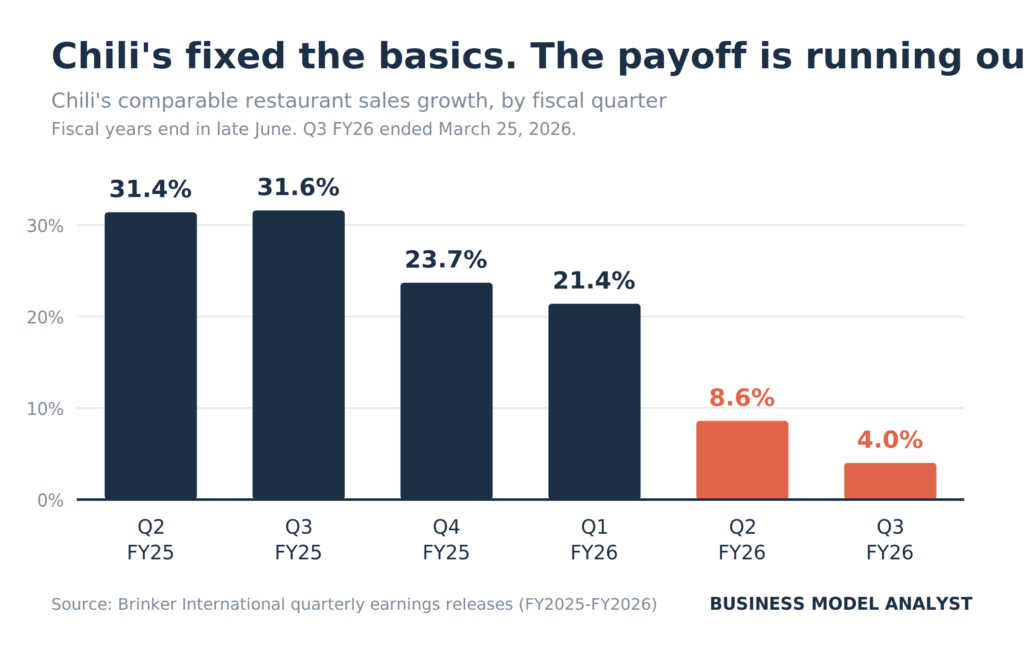
What followed was a run that casual dining has not seen in decades.
The unit economics moved further than the comps suggest. Average restaurant-level profit at Chili’s ran near $370,000 before the turnaround. By the end of fiscal 2025 it reached roughly $790,000. Restaurant-level margin went from 11.9% in 2022 to 19.1% in the most recent reported quarter.
The Plan
Hochman is not adding restaurants. Brinker plans no net Chili’s unit growth until fiscal 2029. Instead the company is remodelling about 10% of its US base each year and squeezing more volume out of the buildings it already owns.
Brinker executives study a cohort they call “North of 6”: locations generating more than $6 million a year against a chain average near $4.6 million. Traffic at those restaurants runs 20% to 80% above average. When Brinker asked their managers what made the difference, the answer was simpler operations, not better demand. “We know we have a lot more capacity in the buildings,” Hochman said.
That single sentence explains the entire technology budget. Chili’s growth in fiscal 2027 and beyond depends on how many covers a fixed number of dining rooms can turn. A server who reorders at the bar terminal costs Brinker a table turn. A cook working from a badly sequenced ticket screen costs Brinker a table turn. Those are the losses Caldwell bought equipment to stop.
The Business Model Angle
Compare the incentive structure to McDonald’s, where roughly 95% of restaurants belong to franchisees. The McDonald’s business model earns most of its money from royalties and rent on those franchised units, which means corporate captures a percentage of a franchisee’s top line and very little of the franchisee’s labour savings. When McDonald’s corporate wants to deploy new in-store technology, it has to sell the idea to thousands of independent operators who will pay for it themselves. Systemwide rollouts turn into negotiations. Novelty tends to win those negotiations, because novelty is easier to pitch than a router.
Brinker owns its restaurants. More than 90% of US Chili’s are company-operated, which puts every hourly wage, every wasted minute and every abandoned order on Brinker’s own income statement. Caldwell did not need to convince a franchise council that better Wi-Fi pays. He needed one video of a spinning wheel and a leadership team that reads the same P&L he does.
The capital allocation follows from the structure:
- Franchised systems buy brand assets. Marketing, menu IP, app ecosystems, loyalty programs. The franchisor monetizes the brand and pushes operating capex downstream.
- Company-operated systems buy operating leverage. Anything that lowers cost per cover or raises covers per hour flows straight to the owner’s margin.
Chili’s sits in the second category and is running a low-price, high-volume model on top of it. A $10.99 meal only works if you serve a great many of them per hour, and the fastest-growing customer cohort at Chili’s is households earning under $60,000. Throughput is the entire business.
Judged against that model, robot servers were a rounding error dressed as innovation, and generative AI phone ordering solved a problem Chili’s did not have. Inventory forecasting survived Caldwell’s cut because ordering accuracy touches food cost and manager hours, which are the two lines that move restaurant-level margin.
The Risk
Brinker got an extraordinary return on ordinary equipment because the equipment had been neglected for a decade. Replacing a tablet that dies mid-shift returns more than almost any AI pilot. You cannot replace it twice.
The comps show the arithmetic closing. Chili’s went from +31.6% to +4.0% in five quarters. Part of that is lapping monster numbers, and 4% still beat the casual dining industry by 420 basis points in the March quarter. But restaurant-level profit per unit cannot double again, and margin cannot repeat the jump from 11.9% to 19.1%. Brinker guided fiscal 2026 revenue to $5.78 billion to $5.82 billion, with non-GAAP EPS of $10.60 to $10.85. At least one sell-side view published in July 2026 argues the stock now prices in momentum the fundamentals no longer support.
There is a second risk in the framing. Caldwell’s restraint is a sequencing call, not a doctrine. He is already pursuing AI for inventory forecasting, which is the obvious next lever once throughput is fixed. Should a competitor with cleaner infrastructure start compounding labour scheduling and demand forecasting gains in fiscal 2028, Brinker’s caution stops looking like discipline. Caldwell’s advantage is that Chili’s now has the network to run those systems on. The chain that skipped the Wi-Fi does not.
Value positioning carries its own exposure. Chili’s took share by undercutting fast food during a stretch of consumer price fatigue. McDonald’s has cut prices on core items and Wendy’s has expanded its menu in response. Denny’s, Applebee’s and IHOP all pushed full-meal value deals. Brinker’s margin depends on holding the $10.99 mix constant, and Hochman has said as much on earnings calls.
Quick Questions
Did Chili’s ban AI? No. Brinker’s leadership reviewed several dozen use cases and kept six or seven for testing, with inventory forecasting and replenishment as the lead candidate. A governance team reviews new proposals monthly and reconsiders past rejections.
How much has Brinker stock risen? More than 500% since Kevin Hochman became CEO in June 2022, according to Bank of America restaurants analyst Sara Senatore, who called the Chili’s turnaround remarkable.
Is the Chili’s turnaround slowing? Chili’s comparable sales grew 4.0% in the quarter ended March 25, 2026, down from 31.6% a year earlier. Brinker attributes part of the deceleration to lapping outsized prior-year numbers and to Winter Storm Fern in January.
What is the “3 for Me” menu? A tiered value platform starting at $10.99 that bundles an entree, a side and a drink at price points aimed at fast food combo meals, with additional tiers at $14.99 and $16.99.
Why does restaurant ownership structure matter here? More than 90% of US Chili’s are company-operated, so Brinker captures the labour and throughput savings from in-store technology. In a heavily franchised system like McDonald’s, those savings accrue to franchisees who must fund the equipment themselves.
The Business Model Analyst Take
Caldwell made the right call, and the trade press will draw the wrong lesson from it. “Fix the basics before you buy AI” is a slogan that fits any company, which is what makes it useless. The transferable insight sits one level down: your technology budget should follow whoever captures the savings.
Brinker owns the boxes, so throughput is money and Wi-Fi is capex with a measurable return. A franchisor in the same category faces a different equation, because the operating savings land on somebody else’s books and the brand asset is what corporate monetizes. Neither is smarter. They are different models producing different correct answers.
Watch two numbers over the next four quarters. The first is Chili’s comparable sales, where anything below 2% means the operational fix is spent and the remodel program has to carry growth on its own. The second is restaurant-level margin, which Brinker held near 19% while spending heavily. If margin holds through fiscal 2027 with the infrastructure bill already paid, Caldwell’s boring capex will have bought Brinker something a chatbot never could: room to raise volume without raising cost.
Reporting on Brinker’s technology strategy from the Wall Street Journal, July 28, 2026. Financial and operating figures drawn from Brinker International quarterly earnings releases (FY2025 to FY2026) and company statements reported by Restaurant Business, Restaurant Dive and CNN.