
A record poultry glut erased a processor’s entire quarterly profit and barely moved the shelf price. The missing money did not vanish. It was captured, node by node, by whoever held the better contract.
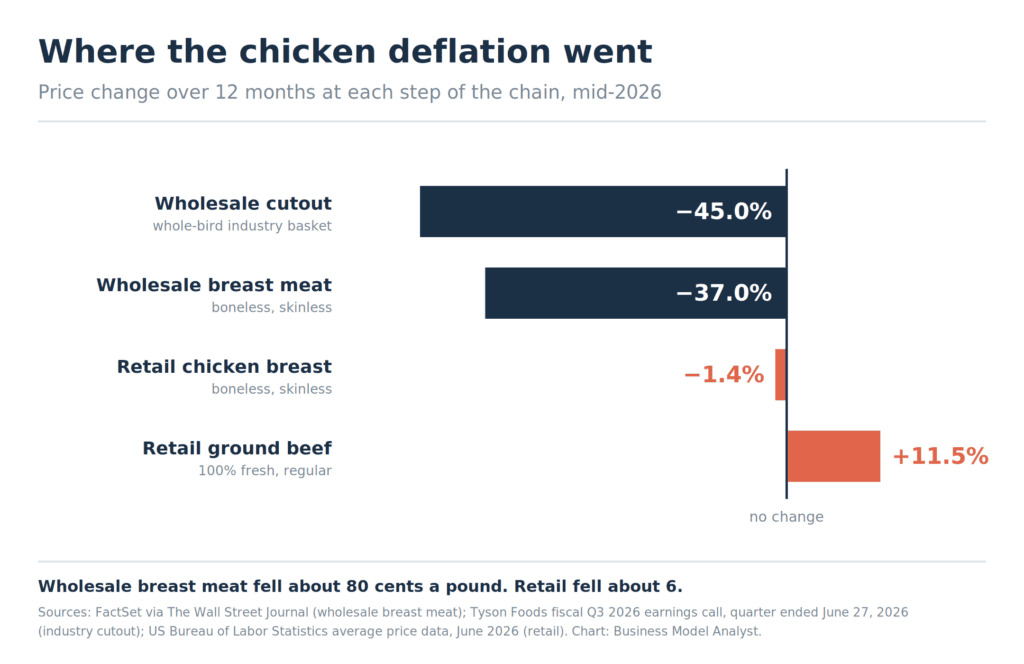
Wholesale boneless skinless chicken breast fell roughly 80 cents a pound over twelve months. The retail price fell about six. That gap is the story, and it is a story about contract structure, not about chickens. In the same three months, Pilgrim’s Pride watched its net income fall 96% while Tyson’s chicken business grew operating income almost 9%. Same birds, same barns, same collapsing commodity market, opposite outcomes. The difference was where each company’s output gets priced.
There is a specific kind of business news that looks like good news and is really a redistribution notice. “Poultry surplus lowers your grocery bill” is one of them. The surplus is real. The lower grocery bill is mostly not.
What Happened
Poultry processors produced more chicken in the first half of 2026 than the market wanted. Companies slaughtered more than 4.9 billion birds through June, up 3% on the year and 6% on five years ago, in an industry that runs through more than nine billion birds annually. Pilgrim’s Pride put total chicken supplies up about 4.5% in the quarter ended June 28.
Prices did what prices do. Wholesale boneless skinless breast fell about 37% over twelve months, according to FactSet. Tyson told investors that industry cutout values, the blended value of everything you can cut off a bird, fell 45% in its June quarter. The USDA’s weighted average for domestic fresh conventional breast meat sat at about $1.37 a pound in early June.
The financial damage landed unevenly.
Pilgrim’s Pride reported second quarter net sales of $4.63 billion, down from $4.76 billion. GAAP net income came in at $13.2 million against $356.0 million a year earlier. Adjusted EBITDA margin halved, from 14.4% to 7.8%. Consolidated GAAP operating margin was 1.4%. A $136 million legal settlement expense sat inside that number, but the direction was set by the market: management pointed straight at commodity cutout values.
Tyson, reporting a near-identical quarter ended June 27, posted chicken segment operating income of $488 million, up from $448 million, on an 11.2% margin. Seven straight quarters of growth in chicken. Adjusted operating income for the whole company rose 8% to $547 million, and the drag came from beef, not poultry.
Now look at the other end of the chain. The US Bureau of Labor Statistics put average retail boneless chicken breast at $4.18 a pound in June 2026, down about 1.4% from a year earlier. Ground beef, over the same twelve months, went from $6.12 to $6.83, up about 11.5%.
The Backstory
The interesting question is not why chicken got cheap. It is why the industry keeps doing this to itself, and the standard answer is wrong.
Stephens analyst Pooran Sharma summed up the consensus view: the industry shot itself in the foot, and all it had to do was be disciplined about production. That reads well and misdiagnoses the mechanism. Producers were reasonably disciplined about the thing they actually control.
Follow the cascade. Broiler growers placed 4.52 billion chicks in the first five months of 2026, up 2% year on year. Head slaughtered in the first half ran up 3%. Pounds of chicken supply ran up about 4.5%. The control variable moved 2%. The variable that sets the price moved more than twice that.
The amplification happens in the conversion. Roughly 90% to 95% of birds in a commercial barn survive the six to eight weeks to slaughter weight. Move that survival rate two points and you have added about 90 million birds to a 4.5 billion placement base without placing a single extra chick. Pilgrim’s CEO Fabio Sandri named exactly this on the July call: livability, he said, is what pushed production past what the industry expected.
Three things pushed in the same direction at once. Weather cooperated. Bird flu, which has repeatedly gutted flocks, stayed out of the main growing regions, an unusually benign outcome for a food supply chain built on a handful of concentrated production regions. And Cobb-Vantress, the breeding company Tyson owns, rolled out a genetic line that grows faster on less feed. Feed itself was cheap, sitting on a record 2025-26 US corn crop of 15.6 billion bushels and corn prices below their long-run average.
Every one of those is a yield improvement. In most businesses a yield improvement is a margin event. In a biological production system with a six month decision lag and no way to slow the line, a yield improvement is an unplanned supply event that arrives as a price cut you did not vote for. You cannot un-hatch an egg, and you cannot warehouse a live bird past its slaughter weight. The industry does not have an overproduction problem. It has a forecasting problem two derivatives away from the number it manages.
The Plan
Both large processors are running the same escape route, and they are running it at different speeds.
Tyson’s CEO Donnie King was blunt on the call: roughly 75% of chicken operating income now comes from a pull-based, value-added model built on customer commitments and branded products, not the open market. Most of the chicken moving through Tyson’s plants now goes into Tyson-branded frozen precooked products sold in grocery stores. Historically the company sold far more of it onward to other processors and distributors at wholesale prices. That shift is why an 11.2% chicken margin survived a 45% cutout collapse.
Pilgrim’s is doing the same thing from behind. Prepared foods volumes rose nearly 14% in the quarter. Its Just Bare brand grew retail sales more than 30% and now holds roughly 15% of the frozen fully cooked chicken category, from about 1% three years ago. Net leverage sits at 1.43x, below the company’s own 2x to 3x target, and it kept an approximately $900 million capital plan intact.
Neither company is describing this as branding. Both are describing it as insulation.
The Business Model Angle
Here is the finding that matters, and it generalizes far past poultry.
Pricing power in a commodity chain is a property of your contracts, not of your assets.
Tyson and Pilgrim’s run comparable vertically integrated systems: breeding stock, contract growers, feed mills, processing plants, cold chain. Textbook vertical integration, the strategy every case study says protects you from input volatility. It protected neither company from anything. What protected Tyson was that three quarters of its chicken profit sits behind negotiated commitments and branded shelf positions, while a larger share of Pilgrim’s big bird output clears against the spot cutout. Owning the whole chain does not set your price. Owning the last contract in the chain does.
Push that logic down to the shelf and the same rule explains the six cents.
A grocer buys chicken on formula and weekly negotiation, and sells it at a price it sets unilaterally against a shopper with no counterparty leverage at all. That is the strongest pricing position anywhere in the chain, and in mid-2026 it was used exactly as you would predict. Good Food Holdings, which owns Bristol Farms, said plainly that it is earning higher margins on chicken and spending part of the savings cutting prices on 80/20 ground beef and New York strip. Read that as a business model statement rather than a consumer story: the chicken buyer is funding the steak buyer’s discount, and the retailer is choosing the recipient.
The USDA’s own promotion data backs this up more than the anecdotes do. In the grocery feature report covering early June 2026, the chicken feature rate ran at 80.5% of outlets against 90.3% a year earlier, with the promotional activity index down about 6% even though more stores were reporting. During the largest chicken glut in years, the grocery trade promoted chicken less than it had the year before. Fareway’s $1.99 breast promotion is real and it is also not the pattern.
The arithmetic, which nobody in the coverage ran: apply the reported 37% decline to that early June wholesale level and the implied year-ago price is about $2.18 a pound, so roughly 81 cents of per-pound cost relief entered the chain. About six cents of it reached the shelf. The gross spread between the retail average and the wholesale quote widened from roughly $2.06 a pound to roughly $2.81, a gain of about 36% in twelve months.
Restaurants are the third claimant. Sysco’s CEO told operators the fastest way to cut food cost right now is a poultry-forward menu. Menu prices are not falling 37%, and the chains built entirely on chicken, Chick-fil-A among them, are the largest single beneficiaries of an input they never had to negotiate down.
The Risk
Several things could make this reading too harsh, and they deserve to be stated properly.
The two series are not the same product. The BLS retail average includes organic, antibiotic-free and frozen breast meat, categories whose prices never fell. The USDA quote is conventional fresh commodity meat. The absolute spread is therefore not a margin, and should never be read as one. The change in the spread is the defensible number, and even that carries mix noise.
Asymmetric pass-through is old news as economics. The pattern where retail prices rise like a rocket and fall like a feather is one of the best documented findings in food retail. What is new here is the size and the specific 2026 measurement, not the mechanism.
Lags are real and legitimate. Retail chicken is frequently bought on formulas with quarterly resets. Some portion of that 81 cents genuinely has not arrived yet and will show up in second half shelf prices. Anyone claiming the money is permanently captured is front-running the data.
The cross-subsidy is real relief, just not to the person who paid for it. A household buying strip steak got a genuine discount funded by the chicken aisle. That is a distributional judgment about who the grocer chose to help, not evidence of anything improper.
And the cycle turns. If placements slow and cutout values recover into 2027, the spread compresses fast, and the grocer that widened it on the way down will be the one absorbing it on the way up. The retailer’s position is strong, not permanent.
The sharper risk sits with Pilgrim’s. Its answer to spot exposure is to build a branded business, and Just Bare’s climb to 15% category share is genuinely impressive. But branded frozen prepared chicken is a slower, more capital-hungry, more competitive business than selling jumbo breast meat, and Tyson got a large head start. Pilgrim’s is trying to buy pricing power in the middle of a quarter that just proved it does not have any.
Quick Questions
Is chicken actually getting cheaper for shoppers? Barely. Retail boneless breast averaged $4.18 a pound in June 2026, about 1.4% below a year earlier, against a wholesale decline of 37% to 45% depending on the cut and source.
Why did Tyson’s chicken business grow while Pilgrim’s collapsed? Tyson says roughly 75% of chicken operating income comes from committed, value-added and branded volume rather than open-market sales. Pilgrim’s carries more exposure to spot commodity cutout values.
Who captured the difference? Mostly the branded processors and the grocery retailers. Retailers explicitly reported higher chicken margins, and at least one has said publicly that it is using them to cut beef prices instead.
Was this an industry discipline failure? Not primarily. Chick placements rose only about 2%. Better survival rates, heavier birds and new genetics turned that into roughly 4.5% more pounds.
Does it get cheaper from here? Possibly, with a lag, if wholesale stays low into the second half. Grocers reset shelf prices slowly and, so far in 2026, have been promoting chicken less than they did last year.
The Business Model Analyst Take
The instinct when a commodity crashes is to look for the victim. That is the wrong search. A commodity crash is not destruction of value, it is transfer of value, and the transfer follows contract structure with almost mechanical reliability.
Poultry made this unusually legible because the whole chain reported inside a two week window. The grower absorbed nothing and earned nothing, because contract growing was designed to strip out exactly this risk. The spot-exposed processor absorbed almost all of it and printed a 1.4% operating margin. The contracted, branded processor absorbed none of it and grew. The retailer captured it and spent it on a different category. The shopper, who is the only participant in this chain with no contract at all, got six cents.
If you run a business that buys or sells anything traded, the operating lesson is narrow and useful. Vertical integration is a cost strategy, and it is frequently sold as a pricing strategy. It is not one. The node that survives a price collapse is the node whose output is priced by agreement rather than by auction, and the cheapest way to buy that position is usually a brand or a committed customer, not another factory. Tyson bought it years ago and is collecting now. Pilgrim’s is buying it in the middle of the storm, which is when it costs the most.
And when a headline tells you a supply glut is lowering your grocery bill, check both ends of the chain before you believe it. Someone always collects the difference. It is rarely the person holding the cart.