
Subhead: The $10,000 franchise fee is the cheapest headline in fast food and the most misleading. Chick-fil-A buys the land, builds the store, owns the equipment, then charges 15% of sales plus half the profit.
What it is: Chick-fil-A operates a corporate-owned, operator-run restaurant system. Chick-fil-A Inc. selects and buys the site, funds construction, owns the building and the equipment, and then places a single full-time Operator in the restaurant under a one-year renewable agreement.
How it earns: Operators pay a Base Operating Service Fee of 15% of gross sales plus an Additional Operating Service Fee equal to 50% of the restaurant’s pre-tax profit. Corporate also collects equipment rent, an advertising contribution of up to 3.25% of monthly sales, and revenue from licensed and company-run locations.
Scale in fiscal 2025: $23.92 billion in US systemwide sales, $10.34 billion in total consolidated revenue, 3,287 US locations, and an average freestanding restaurant volume of $9.16 million.
Why it matters: Chick-fil-A books 43.2 cents of corporate revenue for every dollar its US restaurants ring up. McDonald’s books 19.0 cents.
Chick-fil-A charges the lowest entry fee in American fast food and takes the largest ongoing share of any restaurant system at scale. Both facts come from the same design decision. Chick-fil-A supplies the capital, so Chick-fil-A keeps the return on it.
Most coverage of this company stops at the $10,000 figure and calls it a bargain. Read the Franchise Disclosure Document and the arithmetic runs the other way. Chick-fil-A spends between $585,500 and $3,337,000 to open a restaurant. The Operator contributes $10,000. On the expensive end of that range, the Operator funds three tenths of one percent of the store they run.
Chick-fil-A at a glance
| Founded | 1946, Dwarf Grill, Hapeville, Georgia (first Chick-fil-A, 1967) |
| Headquarters | College Park, Georgia |
| Ownership | Private, Cathy family |
| CEO | Andrew T. Cathy (since 2021); Dan T. Cathy, chairman |
| US locations, year-end 2025 | 3,287 (2,863 franchised and company-operated, 424 licensed) |
| Net US additions, 2025 | 178 |
| US systemwide sales, 2025 | $23.92 billion (+5.2%) |
| Total consolidated revenue, 2025 | $10.34 billion (+14.1%) |
| Average unit volume, freestanding | $9.16 million (median $9.09 million) |
| Initial franchise fee | $10,000 |
| Ongoing fees | 15% of gross sales, plus 50% of pre-tax profit |
| Total investment funded by corporate | $585,500 to $3,337,000 per restaurant |
| International markets | Canada, Puerto Rico, United Kingdom, Singapore |
| Trading days | Six. Every location closes on Sunday |
What Chick-fil-A sells
The chicken sandwich is the product. The business is real estate and capital.
A typical franchise business model sells permission. McDonald’s licenses a brand and an operating system, and the franchisee brings the money for equipment, seating, signage and decor. Subway does a thinner version of the same thing at 8% of sales. In both cases the franchisee owns something, can borrow against it, and can sell it to the next operator at a gain.
Chick-fil-A retains the asset. Corporate picks the corner, negotiates the ground position, pays the general contractor, buys the fryers and the point-of-sale terminals, and holds title to all of it. The Operator brings labor, judgment and a $10,000 check. When that Operator retires, nothing changes hands, because nothing was ever theirs to sell.
That structure explains the selection process everyone finds strange. Chick-fil-A reviews tens of thousands of applications a year and accepts a fraction of one percent. Applicants write essays and sit through rounds of interviews. A conventional franchisor screens for a balance sheet, because the franchisee is funding the store. Chick-fil-A screens for a person, because Chick-fil-A is funding the store and the Operator is the only variable left.
The two fees, and the error almost every article repeats
Chick-fil-A charges two ongoing fees, and they work differently.
The Base Operating Service Fee takes 15% of gross sales. It comes off the top and does not care whether the restaurant makes money. On a $9.16 million freestanding location, that is $1.37 million a year.
The Additional Operating Service Fee takes 50% of the restaurant’s pre-tax profit. It sits at the bottom and moves with performance.
Read together, the two fees put Chick-fil-A on both ends of the income statement. Corporate gets paid before the Operator covers a single cost, and then splits whatever survives. Add the advertising contribution of up to 3.25% of monthly sales and equipment rent running $750 to $5,000 a month, and the Operator faces a cost stack no other major system imposes.
| System | Initial fee | Ongoing royalty | Who funds the build | Operator equity |
|---|---|---|---|---|
| Chick-fil-A | $10,000 | 15% of sales + 50% of pre-tax profit | Chick-fil-A ($585,500 to $3,337,000) | None |
| McDonald’s | $45,000 | 4% to 5% of sales, plus rent | Franchisee funds equipment, seating, signage, decor | Yes, resalable |
| KFC | $45,000 | 4% to 5% of sales | Franchisee | Yes, resalable |
| Subway | $15,000 | 8% of sales | Franchisee | Yes, resalable |
Work the store-level math and the split becomes concrete. Take the average freestanding restaurant at $9.16 million. Corporate collects $1.37 million from the base fee. Assume the restaurant then runs a 12% pre-tax margin, which lands the Operator inside the 5% to 7% of gross sales that outside analysts consistently estimate. Corporate takes half of that $1.10 million, or $550,000. Corporate ends the year with $1.92 million, or 21% of the restaurant’s sales. The Operator keeps $550,000, or 6%.
Corporate takes 3.5 times what the Operator does, from a restaurant the Operator works 60 hours a week to run.
Modeled illustration. Chick-fil-A does not publish store-level margins, and individual results vary with market, format and labor cost.
The capture rate, and where it is going
Franchise systems are usually easy to size. A franchisor collects a royalty of 4% or 5%, adds rent, and books maybe a fifth of what the restaurants sell. Chick-fil-A blows through that ceiling.
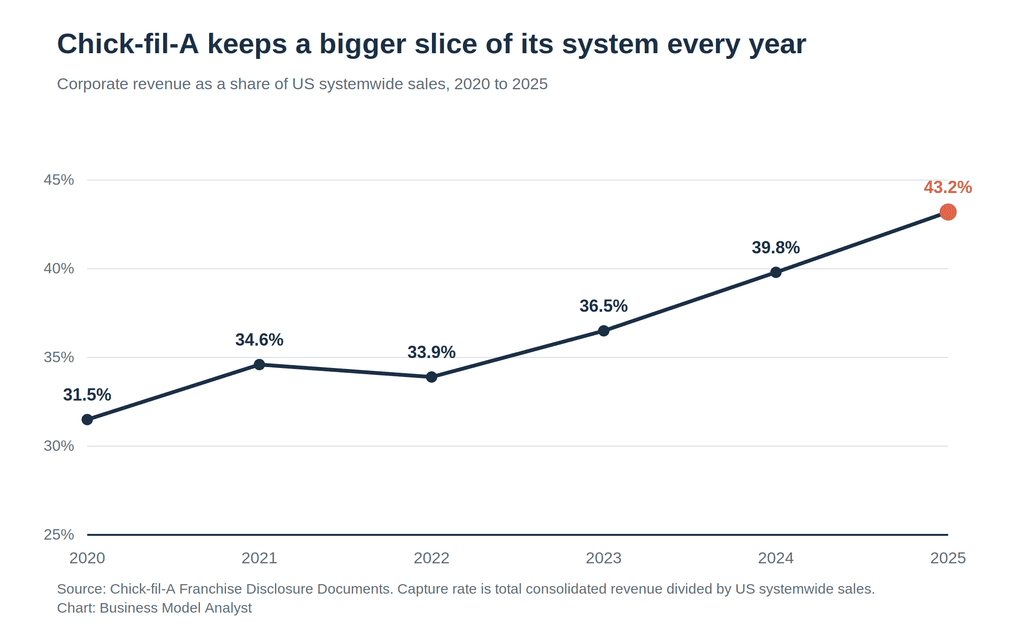
In 2020 Chick-fil-A booked $4.32 billion against $13.70 billion of systemwide sales, a capture rate of 31.5%. In 2025 it booked $10.34 billion against $23.92 billion, or 43.2%. The rate climbed almost 12 points in five years.
One caveat belongs here, because it is the caveat a skeptical reader will raise. Consolidated revenue is not a pure fee line. It includes the gross sales of restaurants Chick-fil-A runs directly, equipment rent, licensed-unit royalties and other corporate businesses. The 43.2% measures how much of the system’s economics ends up inside Chick-fil-A Inc., not the royalty rate. The 21% store-level figure above measures the fee take. Both are real and they answer different questions.
What neither number can be argued away from is the direction.
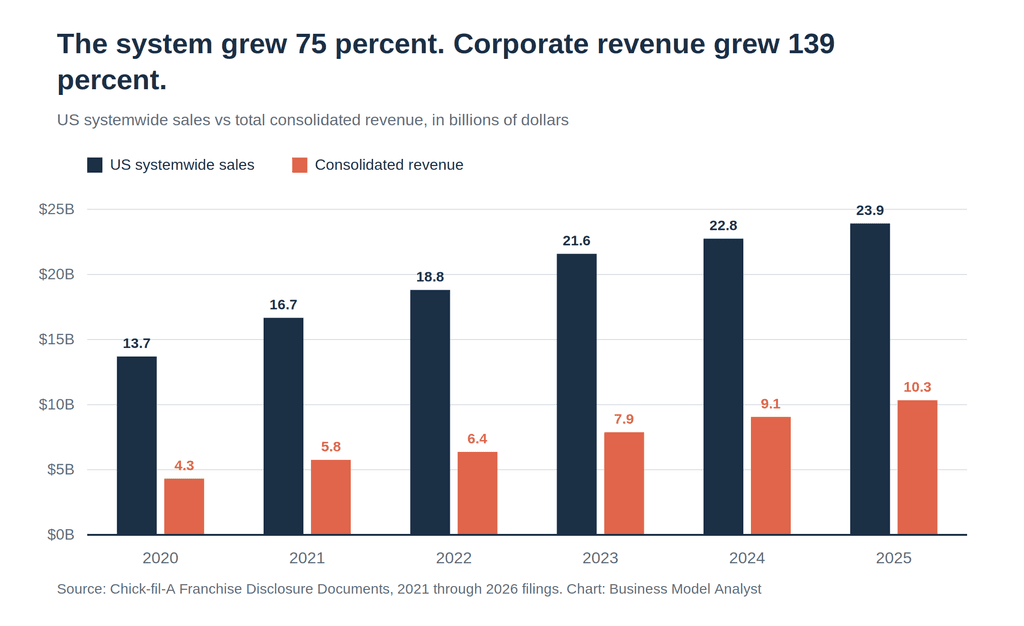
Since 2020, systemwide sales grew 75% and corporate revenue grew 139%. In 2025 alone, systemwide sales rose 5.2% and consolidated revenue rose 14.1%. Corporate revenue grew 2.7 times faster than the system it sits on, in a year when the average freestanding restaurant sold 1.7% less than it did in 2024.
The base fee explains only part of it. Fifteen percent of $23.92 billion is $3.59 billion, or 34.7% of the $10.34 billion Chick-fil-A booked. The royalty everyone quotes is the minority of the take.
Why Operators sign anyway
A 15% fee plus half the profit would kill an operator running a $2 million restaurant. Chick-fil-A restaurants are not $2 million restaurants.
The average freestanding Chick-fil-A sold $9.16 million in 2025 from a six-day week. McDonald’s US average unit volume was $4.09 million from seven. Roughly 1,120 Chick-fil-A restaurants, 49% of the qualifying base, hit the $9.16 million average or beat it. One location cleared $20 million.
Volume is what makes a punishing fee structure liveable. Our Chick-fil-A target market analysis covers how the company builds that demand. At 6% of sales, a $9.16 million restaurant pays its Operator around $550,000. The same 6% at a $2 million volume pays $120,000, and the model stops recruiting anyone worth having. Chick-fil-A’s entire fee structure is underwritten by the highest per-restaurant volume in the QSR 50 outside a handful of specialty formats.
The mall and delivery-kitchen numbers show the floor. Mall locations averaged $4.60 million and delivery kitchens $3.53 million. Both still clear what a strong McDonald’s does.
What the Operator does not get
Read the agreement rather than the marketing and the trade-offs stack up.
The Operator has no equity and no exit. A McDonald’s franchisee who retires sells the business to the next franchisee and books a gain on 20 years of work. A Chick-fil-A Operator hands back the keys. Chick-fil-A can end the relationship on 30 days’ notice without stating a cause. Disputes go to Georgia courts under Georgia law regardless of where the restaurant sits. Multi-unit ownership stays rare by design, so the Operator cannot compound into a second or third location the way Carrols compounded into a thousand Burger Kings.
Chick-fil-A pays for that constraint in a currency other franchisors do not have. Because Operators cannot accumulate units, no single Operator ever grows large enough to negotiate with corporate. Compare that to the franchisee associations that have fought McDonald’s and Burger King over remodel mandates and value pricing. Chick-fil-A never faces a counterparty with leverage, because it never let one form.
The trade the Operator accepts is a $550,000 income on a $10,000 investment, with no capital risk and no debt. Judged as a job, the return is extraordinary. Judged as an ownership stake, it is not one.
Corporate as the capital allocator
Owning every store makes growth a capital problem rather than a recruiting problem.
McDonald’s adds restaurants with other people’s money. Chick-fil-A adds 178 net new US locations a year and pays for all of them. At the midpoint of the FDD investment range, roughly $1.96 million per site, domestic expansion alone consumes something near $349 million of corporate capital annually. Chick-fil-A has no public equity, no rated debt program and no franchisee balance sheets to lean on, so retained earnings fund the whole thing.
Modeled from the FDD investment range and 2025 net unit additions. Chick-fil-A does not disclose development capex.
That constraint shows up in the growth rate. Systemwide sales grew 5.2% in 2025 and 5.4% in 2024, after a decade in which Chick-fil-A posted double digits through the pandemic. Some of the deceleration is industry-wide traffic weakness. Some of it is arithmetic. A self-funded system cannot outrun its own cash flow, and the freestanding volume that funds everything fell 1.7% last year.
Chick-fil-A also closed 18 restaurants in 2025: four mall locations, 13 traditional non-mall stores and one delivery kitchen. Small numbers against 3,287, and a reminder that corporate absorbs the cost of a bad site rather than passing it to a franchisee.
Converting the licensed units is the model eating its own exception
In December 2025 Chick-fil-A announced it would move most of its roughly 425 licensed locations to the Operator model over the next several years. College campuses, hospitals and theme parks are in scope. Airports stay out.
The company framed the change around guest experience, and that part is true: licensed locations cannot accept the Chick-fil-A app, Chick-fil-A One membership or branded gift cards, and converted stores will.
The financial logic is plainer. A licensed location pays a fee to a third-party foodservice contractor’s Chick-fil-A brand license. An Operator-led location pays 15% of sales plus half the profit. Chick-fil-A is converting its lowest-capture channel into its highest-capture one, across 425 sites, at a moment when its capture rate is already the story. Expect that 43.2% line to keep climbing for reasons that have nothing to do with sandwich prices.
The model goes abroad
Andrew Cathy committed roughly $1 billion to international expansion, targeting a presence in five markets by 2030. Chick-fil-A opened in Great Britain and Singapore in 2025, backed by more than $100 million over ten years in the UK and $75 million over ten years in Singapore. Anita Costello runs the international business.
Both entries use local Operators, which keeps the domestic structure intact. Both also expose its weakness. Five UK restaurants in the first two years against a $100 million commitment tells you the ratio: this model spends heavily and opens slowly, because corporate writes every check. McDonald’s entered new countries by finding partners with capital. Chick-fil-A has to bring its own, and it has to rebuild the cold-chain supply network that makes fresh, never-frozen chicken possible in each market.
A 2019 UK pop-up closed within months after protests over the Cathy family’s past donations. The reputational question has not disappeared.
Chick-fil-A against McDonald’s
The two systems sit at opposite ends of franchising, and the revenue lines make the contrast unmissable.
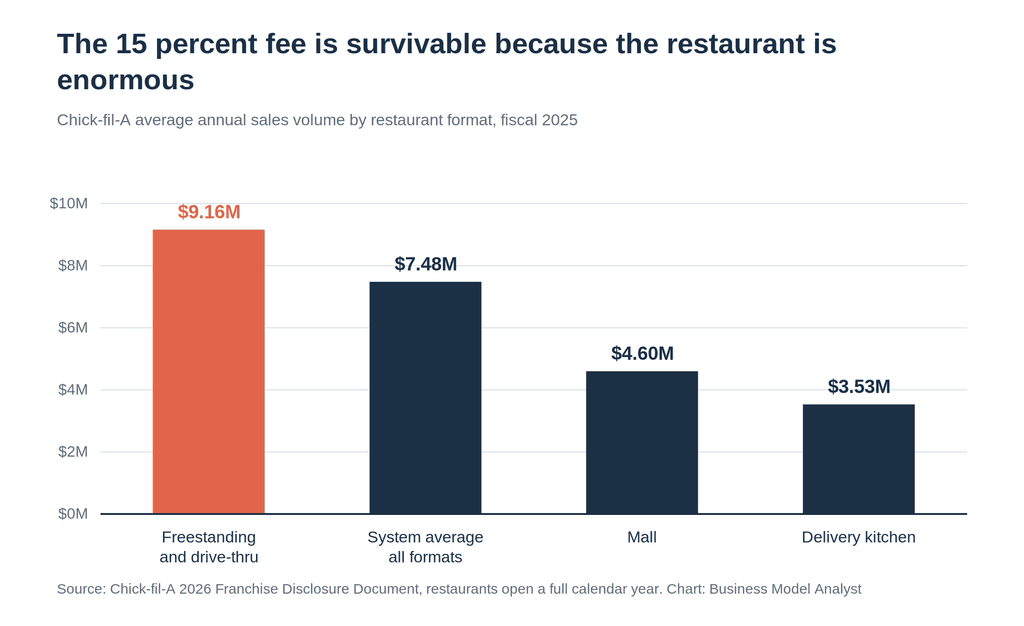
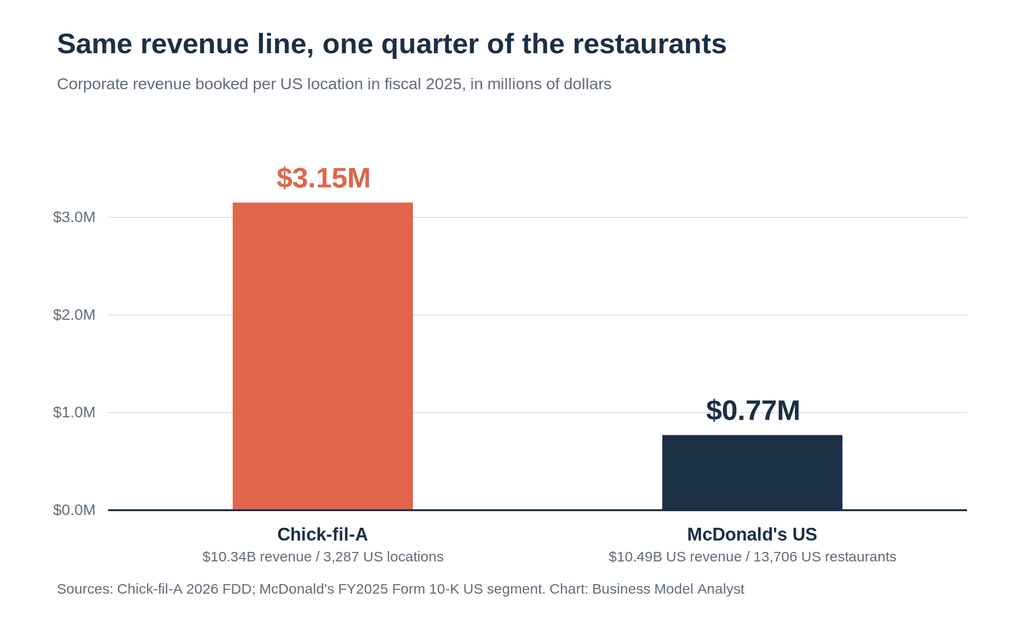
McDonald’s US business booked $10.49 billion of revenue in fiscal 2025 across 13,706 restaurants, or $765,000 per location. Chick-fil-A booked $10.34 billion across 3,287 US locations, or $3.15 million. Two companies with nearly identical US revenue lines, and Chick-fil-A gets there with a quarter of the buildings.
McDonald’s earns a higher margin on what it collects. Its US franchised segment runs an 82.5% margin because rent and royalty carry almost no cost against them, a split we broke down in McDonald’s Q2 2026 results. Chick-fil-A’s revenue is heavier and dirtier, loaded with the operating costs of restaurants it owns and equipment it depreciates. Higher capture, lower margin on the capture, more capital tied up.
Our McDonald’s SWOT analysis treats Chick-fil-A as the most uncomfortable comparison in the category. Both companies solved the same problem. McDonald’s decided to be a landlord and let franchisees carry the risk. Chick-fil-A decided to carry the risk and keep the upside.
What could break it
Our Chick-fil-A SWOT analysis works through the competitive picture in full. The capital structure adds four pressure points of its own.
The volume assumption. Everything rests on $9 million restaurants. Freestanding AUV fell 1.7% in 2025 and the chicken category, which grew 5.3% in 2025 against the burger category’s 1.5%, is drawing capital from every direction. Raising Cane’s, Wingstop and Popeyes all want the same customer. A sustained slide in AUV compresses the Operator’s 6% far faster than it compresses corporate’s 15%.
The capital ceiling. Self-funding caps unit growth at whatever cash flow allows. The $1 billion international commitment now competes with domestic development for the same dollars.
Operator supply. The model needs thousands of capable people willing to work full time for an income with no terminal value. It has never had trouble recruiting. A generation that measures success in equity may weigh the trade differently.
Single-family control. Andrew Cathy runs a private company with no external shareholders and no disclosure obligations. Strategy concentration cuts both ways, and the brand’s political exposure is a family matter rather than a board matter.
Sunday. Six trading days costs roughly 14% of available operating hours. Chick-fil-A absorbs it and still outsells almost everyone. It also means the AUV figures above understate throughput per open day by a wide margin, which is the strongest argument that the model has room left.
Frequently asked questions
How much does a Chick-fil-A franchise cost? The initial franchise fee is $10,000. Chick-fil-A funds the rest, between $585,500 and $3,337,000 per restaurant, and retains ownership of the property and equipment.
How much do Chick-fil-A Operators make? Outside estimates put Operator income at 5% to 7% of gross sales. On the 2025 average freestanding volume of $9.16 million, that is roughly $458,000 to $641,000. Chick-fil-A does not publish an average Operator income figure.
What is Chick-fil-A’s royalty rate? 15% of gross sales as a Base Operating Service Fee, plus 50% of pre-tax profit as an Additional Operating Service Fee. Both are far above the 4% to 8% typical of large franchise systems.
Does Chick-fil-A own its restaurants? Yes. Chick-fil-A Inc. owns or controls the real estate, the building and the equipment at Operator-led locations. Operators run the business and share the profit. They do not hold an equity stake.
How much money does Chick-fil-A make? Chick-fil-A reported total consolidated revenue of $10.34 billion in fiscal 2025 against US systemwide sales of $23.92 billion. As a private company it does not disclose net income.
Can a Chick-fil-A Operator own multiple locations? Rarely. Chick-fil-A designs the system around single-unit Operators working full time in the restaurant, which is the opposite of the multi-unit franchisee model at McDonald’s or Burger King.
Is Chick-fil-A bigger than McDonald’s? No. McDonald’s US systemwide sales were $55.06 billion in 2025 against Chick-fil-A’s $23.92 billion, from four times as many restaurants. Chick-fil-A ranks third in US systemwide sales and first among chicken chains.
The Business Model Analyst Take
The $10,000 franchise fee is real, and reading it as generosity gets the company backwards. Chick-fil-A does not sell franchises. It hires restaurant managers, pays them like partners, and keeps the asset.
That design converts a question other franchisors answer with recruiting into a question Chick-fil-A answers with cash. McDonald’s can open 1,000 restaurants next year if it finds 1,000 franchisees with financing. Chick-fil-A can open as many as retained earnings will fund, which came to 178 last year. Slower growth, and every dollar of the upside stays home.
Watch the capture rate. It climbed from 31.5% to 43.2% in five years, and the licensed-unit conversion will push it further. A system that keeps taking a larger share of flat store volumes is running a margin story, not a growth story. Chick-fil-A can afford that for a long time, because $9 million restaurants leave room for both sides to do well. The day AUV stops covering the 15%, the Operator feels it first and corporate feels it second, and the model discovers whether its people stayed for the money or the arrangement.