
Every link in the chain is tuned to one number the framework never asks about: how many times a day the building gets used.
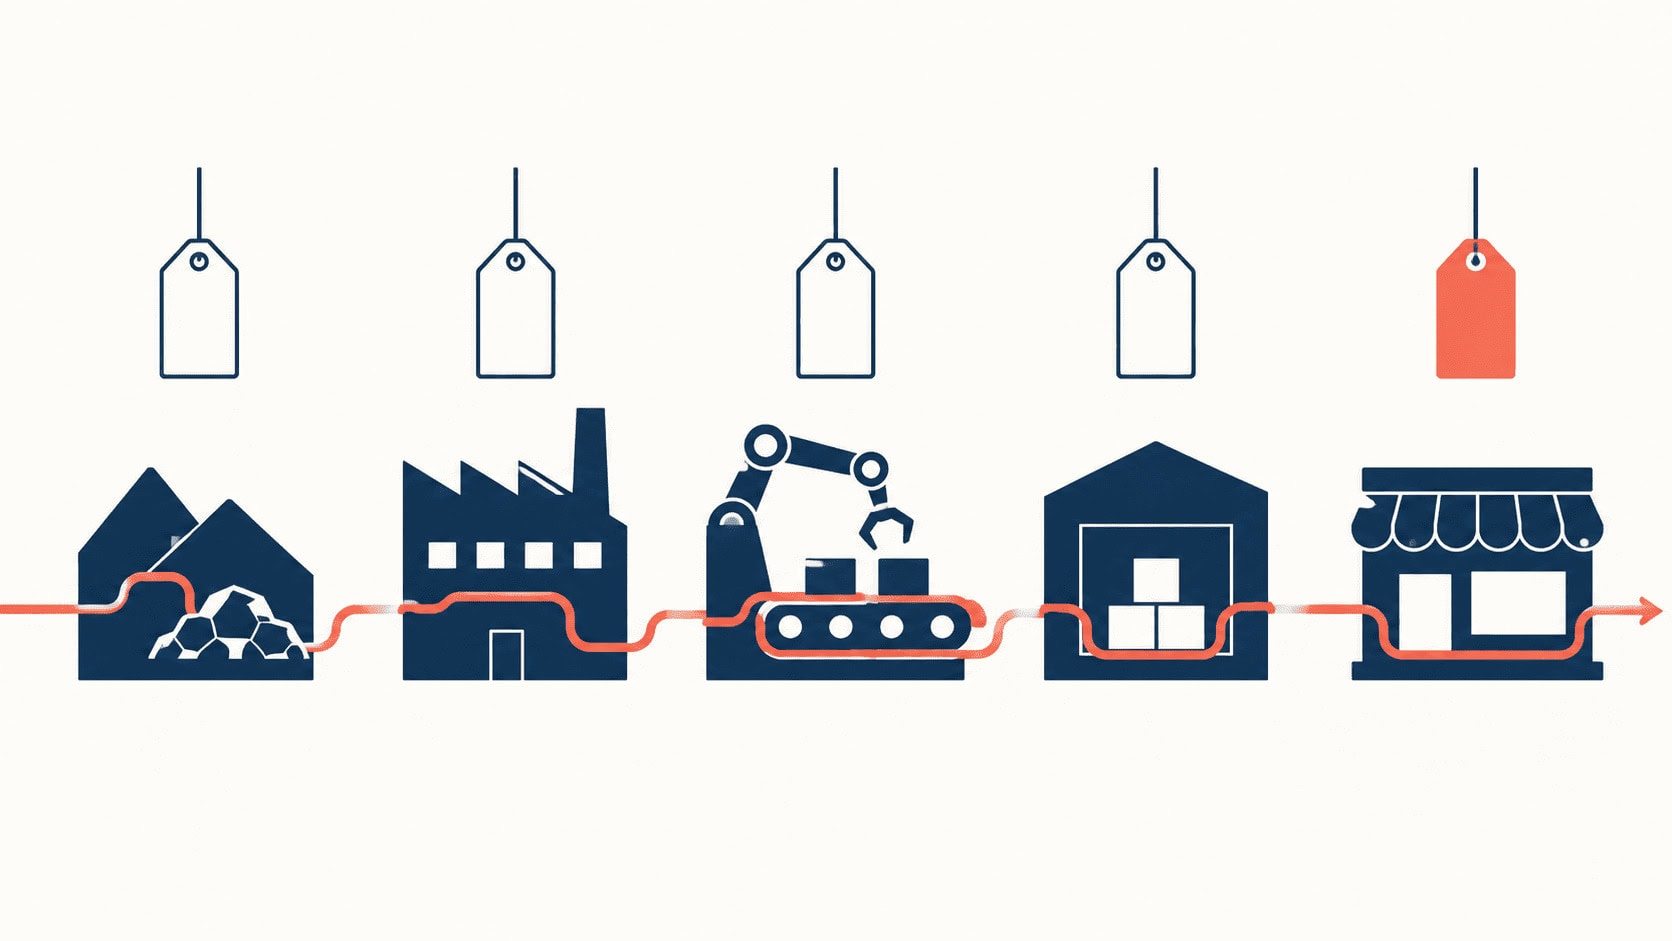
A value chain analysis breaks a company into the activities that create and capture value, split into Porter’s five primary activities (inbound logistics, operations, outbound logistics, marketing and sales, service) and four support activities (procurement, technology, human resources, firm infrastructure). The point is to find where the margin comes from. For Chick-fil-A, the answer sits in none of the nine boxes on its own. It sits in the traffic each box is arranged to move.
Chick-fil-A runs the same chain as every other fast food chain in America. It buys chicken from processors it does not own, trucks it to restaurants, cooks it, and hands it through a window. The parts list is unremarkable.
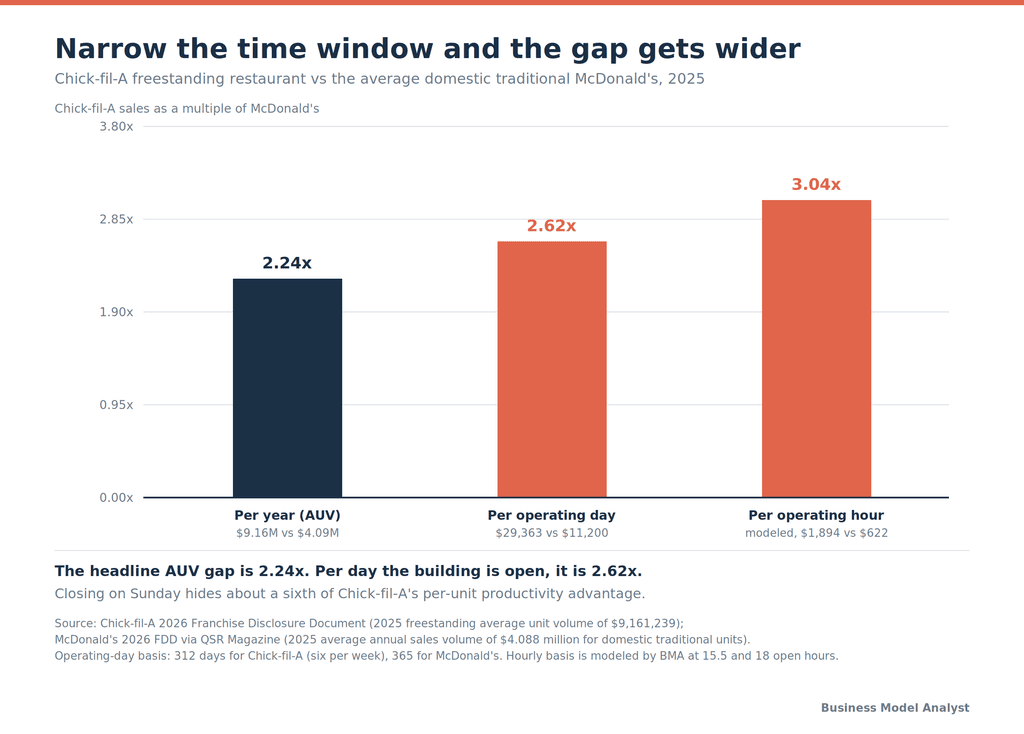
The output is not. A freestanding Chick-fil-A averaged $9,161,239 in 2025. The average domestic traditional McDonald’s did $4.088 million. Chick-fil-A closes on Sunday, so it earns that number on 312 days instead of 365.
Run the division and the picture sharpens. Chick-fil-A pulls $29,363 through a single building on each day it opens the doors. McDonald’s pulls $11,200. The annual gap of 2.24x becomes 2.62x once you count only the days the lights are on, and the six-day week hides roughly a sixth of the productivity advantage.
That ratio is what this chain was built to produce. At every node, Chick-fil-A accepts a worse number in isolation, a slower kitchen, a narrower supplier pool, more people on shift, a distribution network it paid for itself, and buys back the loss at the one node it treats as scarce. The building.
The chain at a glance
| Activity | What Chick-fil-A owns | What it gives up | What it buys back |
|---|---|---|---|
| Inbound sourcing | Nothing upstream. No farms, no hatcheries, no processing plants | Loosened its antibiotic spec in 2024 to hold volume | Supply that scales with unit growth |
| Inbound logistics | Chick-fil-A Supply, a wholly owned distribution subsidiary with 11 open centers, 342 tractor-trailers and 1,147 workers | Hundreds of millions in facility capital that rivals push onto co-ops | Delivery frequency sized to a $29,363-a-day store |
| Operations | The kitchen spec, the equipment, the building | Speed per sandwich. Filets are breaded by hand and cooked to order | Product consistency at peak volume |
| Outbound and service | Four-lane drive-thrus, Mobile Thru lanes, face-to-face tablet ordering | Long visible queues that rank last on total time | 156.97 seconds per car, the fastest in the 2025 study |
| Marketing and sales | Brand, app, loyalty tiers | Discount-led traffic | Pricing power above the category |
| Human resources | Operator selection and training | The payroll itself. Operators employ the 200,000-plus team members | Labor placed at the constraint rather than spread thin |
| Firm infrastructure | Land, buildings, equipment, private ownership | Public equity and franchisee balance sheets | Control of where every dollar of growth capital goes |
Our breakdown of the Chick-fil-A business model covers who collects the money that building produces, including the 15 percent service fee and the 50 percent share of pre-tax profit. This analysis covers what the building has to do to produce it.
Inbound sourcing: the spec bent to hold the volume
Chick-fil-A owns no part of its upstream supply. No farms, no hatcheries, no processing plants. It writes specifications and buys against them, which places it in the same position as most large restaurant chains and a different one from In-N-Out, which runs its own patty production.
The interesting event happened in March 2024. Chick-fil-A had promised in 2014 to serve chicken raised with No Antibiotics Ever, and finished that transition in 2019. Ten years after the pledge, it dropped back to No Antibiotics Important To Human Medicine, a looser USDA-recognized standard that permits ionophores and animal-only treatments. Tyson had made the same move eight months earlier.
The company gave one reason: to maintain supply of the chicken it needs. A spokesperson told reporters that the availability of chicken meeting its standards had become a concern as it looked ahead.
Read that as a value chain decision and it says something specific. Unit growth and volume per unit outran the NAE supply base, so Chick-fil-A widened the supplier pool rather than cap the growth. The spec bent to the throughput, not the other way around.
Critics disputed the premise. Darin Detwiler at Northeastern argued the supply exists and the price point does not, and the National Chicken Council estimates more than half of US chicken production already runs without antibiotics. Both readings land in the same place for our purposes. Chick-fil-A traded a marketing claim for volume it could count on.
Inbound logistics: the node nobody else wants to own
Fast food does not own its trucks. McDonald’s leaves distribution to independent operators like Martin Brower and Golden State Foods. Burger King franchisees fund Restaurant Services Inc. Wendy’s runs purchasing through QSCC. Subway has IPC. In each case the franchisor keeps its capital out and the buying power sits in a cooperative the franchisees own.
Chick-fil-A went the other way. Chick-fil-A Supply is a wholly owned subsidiary. Its first delivery went out in 2019 in Cartersville, Georgia, and its first full-scale center opened there in 2020. By early 2026 the network ran 11 distribution centers across 10 states with 342 tractor-trailers and 1,147 workers, and the company lists 15 sites open or coming soon across 12 states.
The individual buildings are not small. Winter Haven, Florida runs 244,000 square feet on a $150 million investment. Elsmere, Kentucky runs past 270,000 square feet on $100 million and takes product by rail. Lubbock, Texas is a $50 million project and the third Texas center. Each site is built to serve up to 300 restaurants.
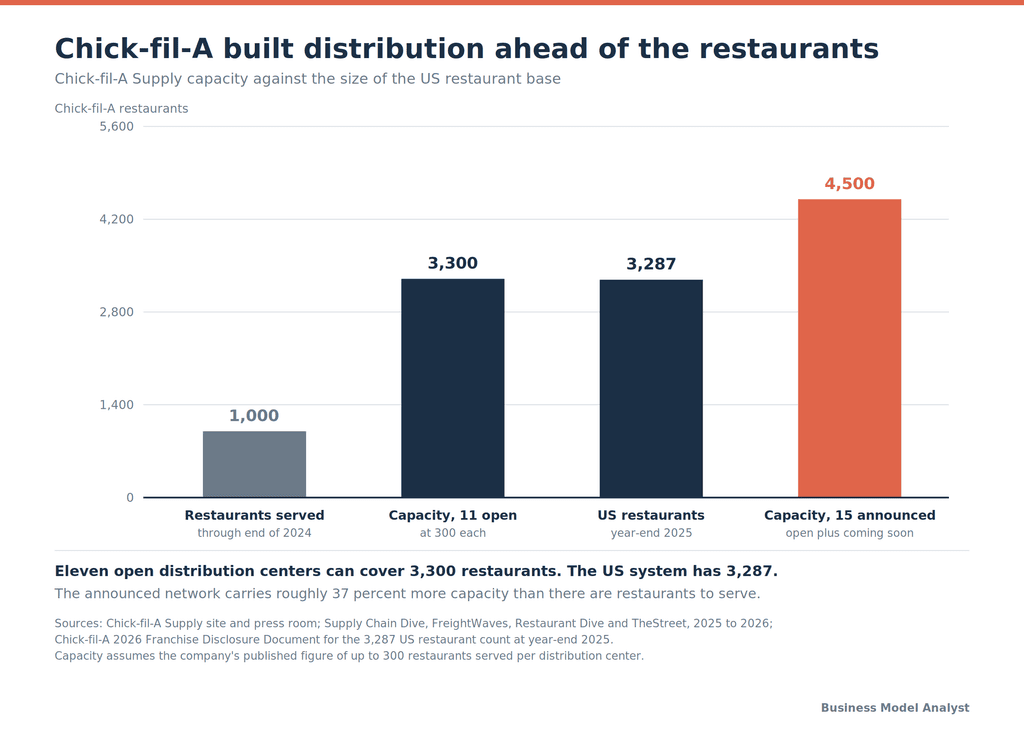
Eleven open centers at 300 restaurants each covers 3,300 restaurants. Chick-fil-A finished 2025 with 3,287 in the United States. The announced network carries about 37 percent more capacity than the company has restaurants to fill, and through the end of 2024 the network was delivering to a little over 1,000 of them.
Nobody builds that for price. A cooperative buys cheaper than a single-tenant network because it aggregates. Chick-fil-A bought something else: the ability to deliver often enough, and at the volumes required, to keep a restaurant doing $29,363 a day in stock without holding a warehouse behind the kitchen. The company’s own description of the problem it set out to solve names frequent high-volume deliveries and rapidly evolving needs.
There is a second reason, and it follows from the operator model. Cooperative purchasing exists because franchisees with capital and multiple units organize to negotiate. Chick-fil-A operators hold one restaurant each and no equity. No cooperative was going to form. Corporate filled the node because nobody else could.
Operations: the slowest kitchen in fast food
Chick-fil-A breads its filets by hand and pressure-cooks them in peanut oil to order. The company describes its approach as cooking less, more often. Every one of those choices costs seconds per sandwich against a chain running frozen patties on a conveyor grill.
The menu absorbs the cost. Chick-fil-A carries a fraction of the SKU count that McDonald’s or Taco Bell manages, and a narrow menu is a throughput instrument before it is a marketing one. Fewer items means fewer holding positions, shorter decision time at the point of order, and a kitchen that can be staffed against a predictable mix.
McDonald’s solves the same equation by simplifying the food. Our McDonald’s value chain analysis walks that chain in detail. Chick-fil-A leaves the food alone and simplifies the order instead.
Outbound and service: where the seconds get bought back
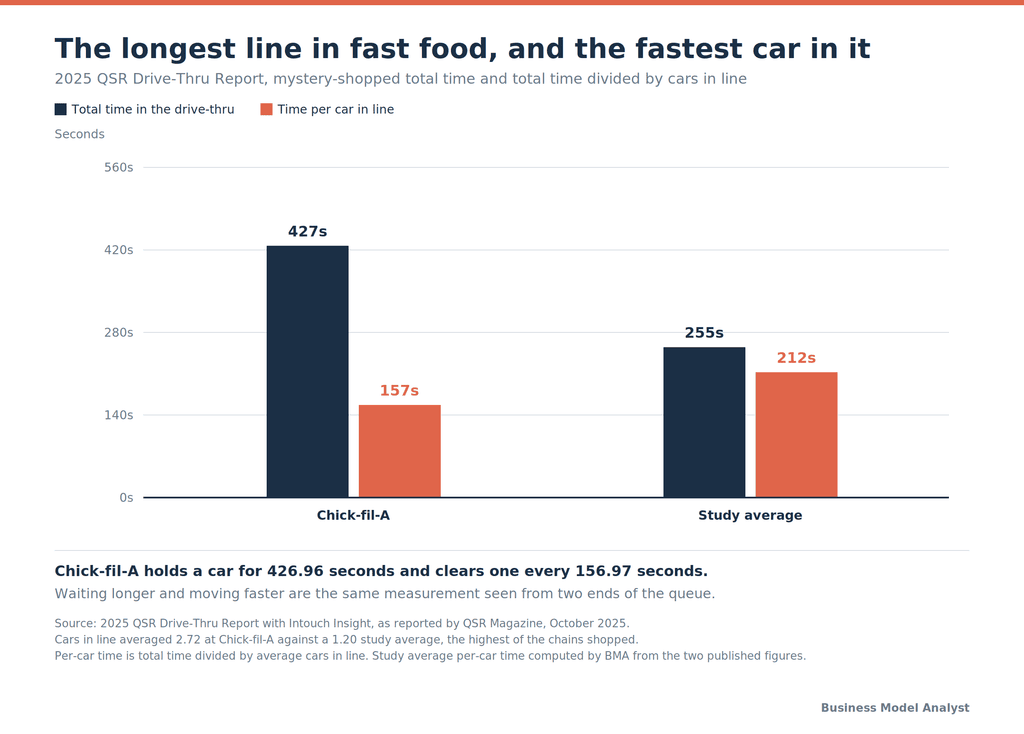
The 2025 QSR Drive-Thru Report, run with Intouch Insight, put Chick-fil-A last on total time at 426.96 seconds. Mystery shoppers found 2.72 cars ahead of them on average, the most of any chain shopped, against a study average of 1.20.
Divide one by the other and Chick-fil-A clears a car every 156.97 seconds, the fastest figure in the study, ahead of Dutch Bros at 167.55 and Raising Cane’s at 179.97. The study average works out to 212.5 seconds per car.
The longest line in fast food and the fastest car in it are the same measurement read from opposite ends. You wait longer at Chick-fil-A because more people are waiting, and you move faster once you are in.
The equipment list at this node reads like a throughput budget:
- Face-to-face ordering on tablets, with team members positioned further out in the line to take orders before the car reaches the board
- Dual lanes as standard, at a moment when 79 percent of drive-thrus the study visited had one complete lane
- Dedicated Mobile Thru lanes at more than 300 restaurants for app orders
- Canopies and weather-rated uniforms, because the order takers work outside
- Drone footage of the lot, which operators review as game film to find where cars stack up during peak
The clearest statement of intent is the Elevated Drive-Thru that opened in McDonough, Georgia in August 2024. Four lanes hold 75 cars. The kitchen sits on the second floor at twice the usual size, and a conveyor drops finished meals to team members on the ground. Chick-fil-A specified that conveyor to deliver a meal every six seconds.
Six seconds is 600 meals an hour. No restaurant averages that. A store doing $29,363 across a 15-hour day is not close to it on average, which is the point. Chick-fil-A sized the machine for the lunch peak, and the company’s own headline number for its flagship design is a unit of time per meal.
The labor node: more people, fewer payrolls
Chick-fil-A restaurants run heavy on staff. Six to eight people working a single drive-thru at peak is normal, against speaker boxes elsewhere.
The company’s own language on the payroll matters here. More than 200,000 team members work in over 3,000 restaurants, and Chick-fil-A states plainly that independent operators employ them. Corporate owns the land, the building, the equipment, and now the trucks. It does not own the labor.
That split gives the chain something a franchisor with a co-op and a landlord relationship cannot get. The variable input that absorbs peak-hour volume sits on the operator’s P&L, and the operator has one restaurant, works in it, and cannot dilute attention across a portfolio. Seventy-six percent of newly selected operators over the past two years had already worked as team members.
Roughly 65 people per restaurant against $9.16 million of annual sales works out near $140,000 of sales per team member. The reputation says Chick-fil-A over-staffs. The arithmetic says it places bodies where the queue is and gets paid for them.
The sixth day is part of the design
Truett Cathy closed on Sunday when he opened the Dwarf Grill in 1946, and the Cathy family has given the same religious reason for eighty years. Take that at face value. The operating consequence is separate from the motive, and it runs in the chain’s favor.
Sunday demand does not evaporate. Some of it moves to Saturday and Monday, which raises the peak the whole chain is engineered to clear. A closure that costs a seventh of the calendar hands back a fatter queue on the days that remain, and a queue is exactly what a four-lane drive-thru and a 600-meal-an-hour conveyor are built to eat.
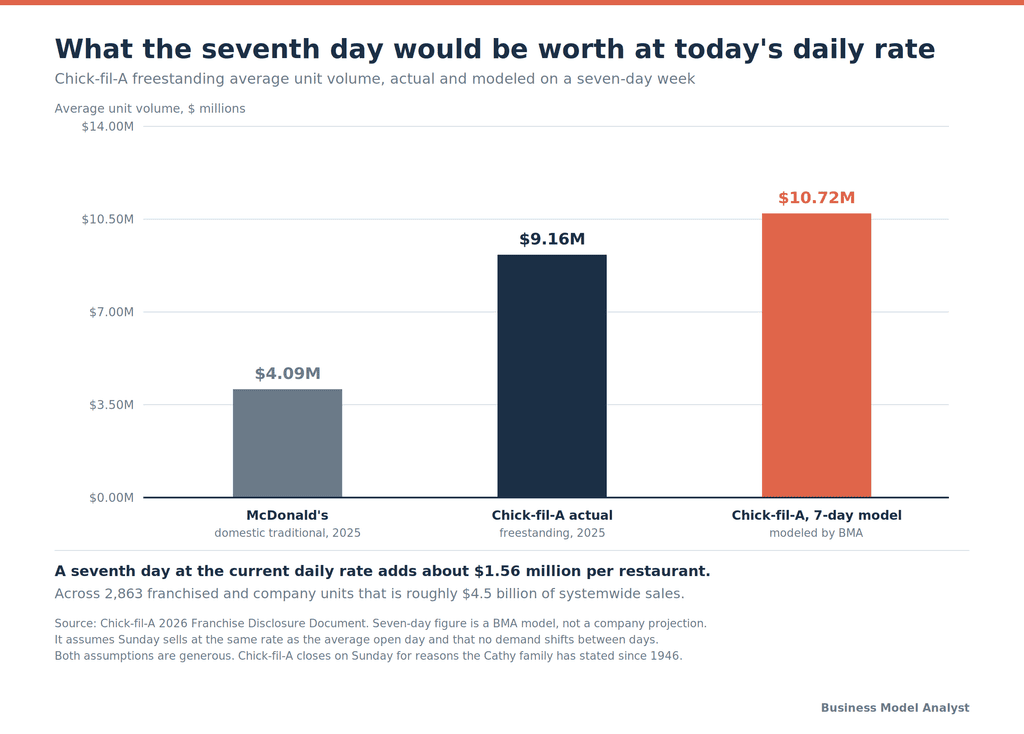
Price the day anyway. At $29,363 per open day, a seventh day would add about $1.56 million per restaurant and roughly $4.5 billion of systemwide sales across the 2,863 franchised and company units. On the 15 percent base fee alone that is close to $668 million a year of corporate revenue.
Treat that as a ceiling and not a forecast. It assumes Sunday sells like an average day and that no demand shifts, and both assumptions flatter the number. What survives the caveats is the scale of what Chick-fil-A declines, and the fact that it still out-earns the category by 2.24x on a year that is one day a week shorter.
The support activities
| Support activity | How it works |
|---|---|
| Procurement | Specification-led, no upstream ownership. The 2024 antibiotic change shows volume winning over the marketing claim |
| Technology | Ordering tablets, the app and Mobile Thru, drone traffic analysis, the conveyor. All of it points at the lane, not the kitchen |
| Human resource management | Corporate selects and trains operators. Operators hire and pay the crew. Multi-unit ownership stays rare by design |
| Firm infrastructure | Private, family-owned, no public equity and no debt program. Corporate funds land, buildings and equipment and now the distribution network too |
The case against this reading
A well-informed skeptic has three good objections.
The AUV gap is a location story, not a chain story. Chick-fil-A operates 3,287 US restaurants against McDonald’s 13,706 and concentrates in Southern suburbs with drive-thru-friendly lots. Fewer stores per market means each one absorbs demand that McDonald’s splits four ways. Some of the 2.62x is trade-area math rather than operating design, and our Chick-fil-A target market analysis covers who fills those trade areas. Fair, and it does not explain the per-car time, which measures the lane and not the lot.
Owning distribution may be a mistake priced as a moat. Eleven centers at $50 million to $150 million each is real capital in a business with no shareholders demanding it. A cooperative would buy cheaper. If unit growth slows, that fixed cost sits on a network built for 4,500 restaurants when 3,287 exist.
The queue is the ceiling as well as the moat. The freestanding average fell 1.7 percent in 2025, the first meaningful step back after a decade of double-digit growth, and 2025 systemwide growth of 5.2 percent came in below 2024’s 5.4 percent. A chain optimized for volume per building starts to look expensive the moment volume per building stops rising.
What would break this chain
Three things, in rough order of likelihood.
Volume per unit keeps sliding. Everything in this design is a fixed-cost bet that the building fills. Distribution capacity, the two-story format, the staffing model and the six-day week all price better at $9 million than at $8 million.
Density catches up with the trade area. Chick-fil-A added 178 net US units in 2025 with Texas leading at 36 openings. Every new store in a mature market splits an existing queue, and the queue is the asset.
The format does not travel. Elevated drive-thrus and four-lane lots need American suburban parcels. The United Kingdom and Singapore, where Chick-fil-A has committed $100 million and $75 million over ten years, offer neither. Our Chick-fil-A SWOT analysis takes the competitive side of that question further.
Frequently asked questions
What is Chick-fil-A’s value chain in one sentence? A conventional restaurant supply chain, owned upstream by nobody and midstream by Chick-fil-A itself, with every activity arranged to raise the number of transactions a single building completes in a day.
Does Chick-fil-A own its supply chain? Partly. It owns distribution through Chick-fil-A Supply, a wholly owned subsidiary running 11 centers with 342 tractor-trailers. It owns no farms or processing plants and buys chicken to specification from outside processors.
Why is Chick-fil-A’s drive-thru both the slowest and the fastest? Total time counts the whole visit including the wait, and Chick-fil-A averages 2.72 cars in line against a 1.20 study average. Total time divided by cars in line puts Chick-fil-A first at 156.97 seconds per car.
How much does one Chick-fil-A sell per day? A freestanding restaurant averaged $9,161,239 in 2025 across roughly 312 open days, or about $29,363 a day. The average domestic traditional McDonald’s does about $11,200 a day.
Why did Chick-fil-A stop using antibiotic-free chicken? The company moved from No Antibiotics Ever to No Antibiotics Important To Human Medicine in spring 2024 and said the change was needed to maintain supply of chicken meeting its standards. Critics argued the supply exists at a higher price.
Who employs Chick-fil-A restaurant staff? Independent owner-operators do. Chick-fil-A states that more than 200,000 team members are employed by operators rather than by Chick-fil-A, Inc., which owns the real estate and equipment. Our franchise business model explainer covers how that differs from standard franchising.
Does closing on Sunday cost Chick-fil-A money? On a straight per-day basis, a seventh day would be worth about $1.56 million per restaurant and roughly $4.5 billion systemwide. The closure also concentrates demand into six days, which raises the peak volumes the chain is designed to clear.
The Business Model Analyst Take
Porter’s chain asks where the margin is added. Chick-fil-A answers by refusing to optimize any single link. It buys a more expensive protein prepared a slower way, staffs more people per shift than the category, funded a distribution network its competitors deliberately push onto cooperatives, and shuts the doors one day in seven. Judge any node on its own and it looks like a company leaving money on the table.
Judge the chain by transactions per building per day and it becomes coherent. Chick-fil-A moved the scarce resource from the ingredient to the parcel, and every node from the supplier spec to the conveyor belt exists to fill it. The company that describes its flagship restaurant design in seconds per meal is telling you what it optimizes.
The bet has one weakness worth watching, and 2025 showed it. When a freestanding average of $9.16 million falls 1.7 percent, the whole architecture gets more expensive at once. This chain does not have a low-volume mode.