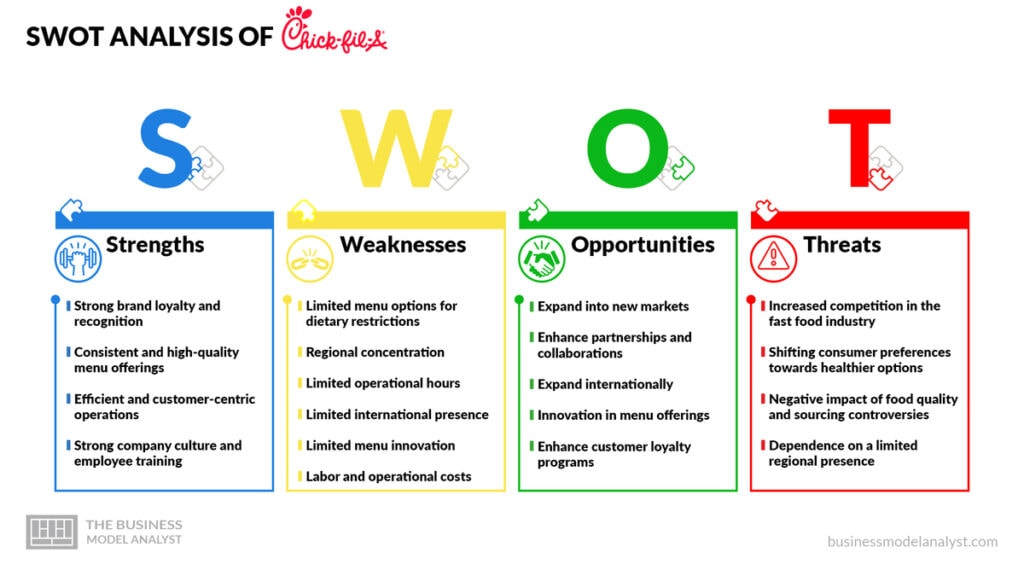

Chick-fil-A SWOT at a Glance
What it is: A strategic snapshot of Chick-fil-A’s internal strengths and weaknesses paired with the external opportunities and threats shaping its 2026 outlook.
Bottom line: Chick-fil-A remains the third-largest U.S. restaurant chain by systemwide sales ($22.7 billion in 2024, per its Franchise Disclosure Document), the ACSI customer satisfaction leader in fast food for the 11th consecutive year, and the highest-grossing per-unit player in the segment. But 2024 marked its slowest sales growth in nearly two decades (5.4%), international expansion is finally moving (UK and Singapore opened late 2025), and chicken-segment competitors like Raising Cane’s and Wingstop are closing the satisfaction and share gap fast.
Who it’s for: Strategy students, business analysts, franchisees, marketers, and investors evaluating QSR positioning in 2026.
| Quick Reference | Detail |
|---|---|
| Company | Chick-fil-A, Inc. (private, family-owned) |
| Founded | 1946, Hapeville, Georgia |
| HQ | Atlanta, Georgia |
| CEO | Andrew T. Cathy |
| 2024 systemwide sales | $22.7 billion (US) |
| 2024 total revenue | $9.06 billion (+14% YoY) |
| 2024 sales growth | 5.4% (slowest in ~19 years) |
| US locations (year-end 2024) | ~3,100 |
| International markets | Canada, Puerto Rico, UK (2025), Singapore (Dec 2025) |
| Average unit volume (stand-alone) | $7.4M (more than 2x McDonald’s) |
If you want the underlying framework first, our primer on what a SWOT analysis is and how to do one covers the methodology. For the wider business picture, the Chick-fil-A business model breakdown pairs well with this analysis.
Chick-fil-A in 2026: the context that shapes the SWOT
Chick-fil-A isn’t a normal fast food story. It’s privately held, family-controlled, closed on Sundays, charges a $10,000 franchise fee (versus McDonald’s $45,000), and still outsells almost everyone per location. According to Restaurant Business, the chain’s average-unit volume hit $7.4 million in 2024, with stand-alone restaurants pulling roughly $9 million. McDonald’s, for reference, averaged about $4 million per US unit.
What changed in 2024 and 2025 is the growth slope. After averaging 15.5% systemwide sales growth between 2020 and 2023, Chick-fil-A grew just 5.4% in 2024, its first sub-10% year since 2013. Unit count drove almost all of it. Same-store traffic is no longer doing the heavy lifting it used to.
That single shift reframes the SWOT for 2026: strengths that look ironclad on the surface are now being tested by competitors who have figured out which parts of the Chick-fil-A playbook they can copy.
Strengths
These are the internal assets keeping Chick-fil-A on top of the chicken segment despite slower growth.
| Strength | What it actually delivers | 2024-2026 evidence |
|---|---|---|
| Customer satisfaction dominance | Repeat visits, organic word-of-mouth, pricing power | ACSI score of 83, #1 fast food brand for 11 straight years |
| Per-unit productivity | Higher franchisee margins, faster payback | $7.4M average unit volume; $9M+ for stand-alone units (Technomic data) |
| Tight menu focus | Operational simplicity, training consistency, lower waste | Roughly 30 core items vs 100+ at major burger chains |
| Selective franchise model | Brand consistency, operator commitment | ~1% applicant acceptance rate; $10,000 franchise fee (Chick-fil-A keeps most ownership) |
| Drive-thru engineering | Throughput advantage, lower labor cost per order | Multi-lane setups and face-to-face order taking; new “Elevated” drive-thru-only prototype piloted 2024-25 |
| Closed Sundays as identity | Brand differentiation, employee retention | Founder-rooted policy that paradoxically lifts the other six days |
| Financial firepower | Funds tech, real estate, and global expansion without outside capital | $946M comprehensive earnings in 2024; debt-light private balance sheet |
A few of these deserve unpacking.
Customer satisfaction is the real moat. The 11-year ACSI streak isn’t a soft metric. ACSI links satisfaction directly to repeat visits and revenue, and Chick-fil-A’s 83 outpaced the QSR average of 79 in the 2025 report. McDonald’s, by contrast, sat at 70. That gap is what lets Chick-fil-A raise prices without bleeding traffic the way some peers do.
The franchise model is genuinely unusual. Most QSR chains want as many franchisees as possible. Chick-fil-A wants the right ones. Operators run one restaurant, full-time, with no absentee ownership. The result: a workforce culture that prioritizes service in a way you simply don’t see at chains where franchisees own dozens of units. For the structural detail behind this, see the Chick-fil-A organizational structure analysis.
Weaknesses
The flip side of every strength above, plus a few that don’t get talked about enough.
| Weakness | Strategic cost | Notes |
|---|---|---|
| Sunday closures | ~14% of potential weekly trading hours forfeited | Estimated $1B+ in lost annual revenue at current sales pace, though the brand effect partially offsets this |
| Heavy US concentration | Currency, regulatory, and demographic single-point exposure | As of late 2025, fewer than 30 non-US locations across Canada, UK, and Singapore |
| Narrow menu | Lower share of breakfast, beverages, late-night, and family-pack occasions | No burgers, no pizza, limited beverage innovation versus Starbucks-Wendy’s hybrid pushes |
| Premium price perception | Vulnerability in recessions and to value-focused competitors | Average check of $14.10 in 2024 (Technomic) vs ~$11.50 at McDonald’s |
| Brand-values controversies | Periodic boycott cycles, urban-market resistance | Past donations to organizations opposing LGBTQ+ rights still surface in coverage; airport and university contracts contested |
| Slow international track record | Forfeited first-mover advantage globally | KFC operates in 145+ countries; McDonald’s in 100+; Chick-fil-A is in 4 |
| Franchisee growth ceiling | The selectivity that drives quality also caps unit growth | Sub-1% acceptance rate is a feature for quality, a bug for expansion speed |
| Chicken-only supply concentration | Avian flu, feed cost shocks hit harder than at diversified menus | 2022 HPAI outbreak previously affected chicken supply chains across QSR |
The Sunday closure is the one most readers misjudge. Yes, the financial cost is real. But the brand identity it creates, and the staff retention it drives in a sector with 144% average annual turnover according to NRA data, is part of why Chick-fil-A’s unit volumes are double McDonald’s. Trying to “fix” this weakness would likely cost the brand more than it would gain.
The international weakness, however, is a legitimate strategic problem. Five international locations by 2030 against KFC’s 30,000+ global units is not a competitive race. It’s a category Chick-fil-A has effectively conceded for the better part of two decades.
Opportunities
Where Chick-fil-A could realistically extract growth in 2026 and beyond.
| Opportunity | Realistic timeline | Why it matters |
|---|---|---|
| UK and Singapore expansion | 2025 onward | First Singapore store opened December 11, 2025 at Bugis+; Leeds opened fall 2025; $175M committed over 10 years |
| Five international markets by 2030 | 2026-2030 | $1 billion investment commitment announced in 2023 |
| Digital and loyalty deepening | 2026-2027 | Chick-fil-A One has tens of millions of members; competitors are catching up on app UX and personalization |
| Drive-thru-only and small-footprint formats | Now in pilot | “Elevated” drive-thru format and four-lane prototypes reduce real estate cost and increase throughput |
| Dwarf House acquisition synergies | 2025-2027 | Chick-fil-A bought Dwarf House Group from STC Brands for ~$67M in 2024 (Franchise Times); new menu and concept testing ground |
| Beverage and snack daypart | 2026 onward | Lemonade and milkshake mix already strong; coffee and cold-brew expansion would attack the Starbucks adjacency |
| AI-driven labor and forecasting | 2026 onward | Industry-wide push; Chick-fil-A’s high AUVs mean even small efficiency gains compound fast |
| Healthier and grilled positioning | Ongoing | Grilled nuggets and salads already exist; cleaner-label push would defend against Cane’s-style minimalism backlash |
| Catering and family meal occasions | Underdeveloped | Higher ticket sizes, lower competition than core lunch |
| Supply chain investment | Active | A new $50M Lubbock, Texas distribution center signals a shift from pure expansion to operational scale |
Notice what’s missing from this list: aggressive price discounting. Chick-fil-A’s customers are not price-sensitive in the same way McDonald’s customers are, and value-meal warfare would likely destroy brand equity faster than it would defend share.
Threats
The forces that could compress Chick-fil-A’s margins, growth, or pricing power.
| Threat | Severity | Why it’s serious in 2026 |
|---|---|---|
| Chicken-segment competition | High | Raising Cane’s and Wingstop both grew faster than Chick-fil-A in 2024; both are passing $5B+ in sales with strong satisfaction scores |
| Slowing same-store growth | High | First sub-10% systemwide growth year since 2013; 2024 growth came almost entirely from new units, not traffic |
| Price fatigue | Medium-High | QSR menu prices rose 27.2% from Feb 2020 to June 2024 per BLS data; consumers visibly pulling back |
| Labor cost inflation | High | Wage floors rising in major states (California’s FAST Act set $20/hr minimum in QSR in 2024); high-touch service model is labor-intensive |
| Avian flu and poultry shocks | Medium | Chicken-only menu = single point of supply failure |
| Brand polarization | Medium | Cathy family’s history of donations still surfaces in coverage and shapes urban-market reception |
| AI-driven competitive parity | Medium | McDonald’s and Wendy’s are pouring capex into AI drive-thrus and dynamic pricing; could close the speed and accuracy gap |
| Plant-based and dietary shifts | Low-Medium | Gen Z dietary patterns include more plant-forward eating; Chick-fil-A has limited offerings here |
| Tariff and trade exposure | New in 2025-2026 | International expansion increases exposure to currency and trade policy shocks |
The biggest one to watch is competitive parity. For a decade, Chick-fil-A had a hospitality moat that no one could replicate at scale. In 2025, ACSI explicitly called out that smaller brands like Raising Cane’s and Wingstop are proving creative marketing and digital engagement can challenge legacy chains. That’s not a hypothetical threat. It’s already happening to KFC, which dropped 5% year-over-year in ACSI to 77.
Chick-fil-A vs the chicken segment leaders (2024 systemwide sales)
| Brand | 2024 US systemwide sales | YoY growth | ACSI 2025 |
|---|---|---|---|
| Chick-fil-A | $22.7B | 5.4% | 83 |
| Popeyes Louisiana Kitchen | $5.73B | Modest | 75 |
| KFC US | $4.91B | Negative | 77 |
| Bojangles | $1.89B | Mid-single digits | n/a |
| El Pollo Loco | $1.10B | Low single digits | n/a |
What the 2026 SWOT actually tells you
If you take only one read from this analysis, take this: Chick-fil-A’s strengths are still extraordinary, but the competitive context has shifted from “no one can touch them” to “the gap is finally closing.” The chain remains the most efficient, most-loved fast food brand in America. But growth in 2024 came from opening more boxes, not selling more per box, and that’s the metric that matters strategically.
The 2026 strategic priorities, if you read between the lines of the public moves, are:
- Defend the satisfaction moat against Raising Cane’s and Wingstop by investing in service consistency and digital experience.
- Make international actually material by executing on UK and Singapore beyond ribbon-cuttings, then proving a replicable playbook for the additional three markets promised by 2030.
- Diversify the daypart and ticket mix through Dwarf House experimentation, beverage push, and catering rather than discounting.
- Defuse the price ceiling by improving perceived value (portion, freshness messaging, loyalty rewards) without dropping menu prices.
For a deeper look at how Chick-fil-A makes money and structures its franchise economics, see Chick-fil-A’s business model. To benchmark against the closest large competitor, the McDonald’s SWOT analysis and Burger King SWOT analysis make useful pairings.
FAQs
Is Chick-fil-A still growing in 2026? Yes, but more slowly than at any point in the last two decades. Systemwide US sales grew 5.4% in 2024 to $22.7 billion, the first sub-10% growth year since 2013, with almost all of the gain coming from new units rather than same-store sales.
Is Chick-fil-A international yet? Effectively for the first time, yes. Chick-fil-A opened its first UK restaurant in Leeds in fall 2025 and its first Asian location in Singapore (Bugis+) on December 11, 2025. The company has committed $175 million to those two markets over 10 years and plans up to five international markets by 2030.
Who actually owns Chick-fil-A? The Cathy family. The company is privately held, with Dan Cathy as chairman and Andrew T. Cathy (Dan’s son) as CEO. There is no public stock.
Why is Chick-fil-A closed on Sundays? Founder S. Truett Cathy’s personal religious commitment. The policy has been in place since the first restaurant in 1946 and has become a brand signature. The estimated revenue cost is offset by retention, recruitment, and brand differentiation benefits.
Is the controversy about donations still relevant? Less than it was. Chick-fil-A’s foundation stopped donations to several organizations critics had flagged in 2019. The reputational tail still appears in coverage but has materially diminished as a business issue.
Where does Chick-fil-A rank against McDonald’s? Third by US systemwide sales, behind McDonald’s ($53.5B) and Starbucks ($30.4B). But Chick-fil-A’s average unit volume of $7.4M is nearly double McDonald’s $4M, meaning each individual Chick-fil-A is far more productive.
Methodology note: figures cited come from Chick-fil-A’s 2024 Franchise Disclosure Document (released April 2025), the ACSI Restaurant and Food Delivery Study 2025, Technomic Ignite data, US Bureau of Labor Statistics, and reporting by Nation’s Restaurant News, QSR Magazine, Restaurant Business, Franchise Times, and Restaurant Dive. All financial figures are USD.