
CeraVe’s target market is anyone with a skin condition and a budget, which in practice means three overlapping groups: teens and young adults aged 13 to 24 who build routines from TikTok, adults aged 25 to 55 managing eczema, acne, or a damaged skin barrier, and the dermatologists and pharmacists who tell both groups what to buy. CeraVe segments by diagnosis, not by demographics. That is why one product line serves a 14-year-old boy with breakouts and a 58-year-old woman with psoriasis, and why the brand holds a 32% share of US teen skincare mentions while still being sold in the eczema aisle.
What Is a Target Market?
A target market is the specific group of buyers a company designs its products, pricing, and messaging around. It is defined through five lenses: demographic (age, gender, income), geographic (where buyers live), psychographic (values and identity), behavioral (how they buy and how often), and technographic (which platforms and devices shape their decisions). A brand can serve a wide audience and still have a narrow target market. CeraVe is the rare case where the reverse is true: a narrow clinical origin that ended up serving a wide audience.
CeraVe at a Glance
| Item | Detail |
|---|---|
| Founded | 2005, developed with dermatologists |
| Owner | L’Oreal, part of the Dermatological Beauty division |
| Acquisition | Bought from Valeant (now Bausch Health) in 2017 for $1.3 billion, bundled with AcneFree and Ambi |
| Core technology | Three skin-identical ceramides (EOP, NP, AP) plus MVE slow-release delivery |
| Global sales | Crossed $2 billion in 2024 |
| Division sales | Dermatological Beauty reached 7.2 billion euros in 2025, up 5.5% like for like |
| Price band | Roughly $10 to $20 for core skincare; the 2024 haircare line launched entirely under $10 |
| Key markets | United States, mainland China, Europe, and emerging markets |
| Headline claim | “#1 dermatologist-recommended skincare brand in the United States” |
CeraVe is not a beauty brand that happens to be cheap. It is a therapeutic product that got adopted as a beauty brand, and the difference explains almost everything about who buys it.
The Five Segmentation Lenses
Demographic Segmentation
CeraVe’s age spread is unusually wide for a single-price-tier brand. The center of gravity sits in two humps: teens and young adults aged 13 to 24, and adults aged 30 to 55 who buy for condition management or for their kids.
Gender skew is mild by beauty standards. Piper Sandler’s spring 2025 survey found CeraVe was the top skincare brand among US teens overall and the top brand among teen boys specifically. Very few beauty brands can say that. The fragrance-free, unbranded, near-medical packaging removes the social cost of a teenage boy putting a bottle in a shopping cart, which is a distribution advantage disguised as a design choice.
Income skews toward the middle. Piper Sandler’s Fall 2025 respondents reported an average household income of $69,527. CeraVe’s price ladder was built for exactly that household: enough disposable income to buy skincare on purpose, not enough to spend $68 on a serum.
Geographic Segmentation
The United States is the profit center and the saturation risk. L’Oreal’s 2025 results describe CeraVe achieving a “gradual turnaround” in US skincare, which is corporate language for a stall that took a year to fix. Meanwhile, in mainland China and emerging markets, L’Oreal reported CeraVe growing well ahead of the market.
The geographic story for the next five years is straightforward. In the US, CeraVe defends. In China, India, Brazil, and Southeast Asia, it acquires. The buyer profile flips accordingly: in the US, CeraVe is a repeat purchase for someone who already owns four skincare products. In Jakarta or Sao Paulo, CeraVe is often the first dermatologist-endorsed product someone has ever owned.
Psychographic Segmentation
CeraVe buyers share one belief: skincare is a health decision, not a beauty decision.
That belief shows up in what they reject. They do not want packaging that signals luxury. They do not want a founder’s face on the bottle. They want an ingredient list they can cross-reference. The Cafeteria consumer survey reported in late 2025 found that one in five Gen Z women and men use drugstore staples like CeraVe and Cetaphil, while one in three women mix drugstore and prestige in the same routine. CeraVe wins the base layer of that routine, the cleanser and the moisturizer, and cedes the fun layer to prestige.
The psychographic profile also has a defensive streak. Many CeraVe buyers arrived after something went wrong: a reaction to a trendy acid, a flare-up, a dermatologist appointment. CeraVe is the brand you return to after being burned by a brand that promised more.
Behavioral Segmentation
Purchase frequency is high and replacement is automatic. Cleansers and moisturizers run out. The 16-ounce tub and the pump bottle exist to make CeraVe the default refill, and the household size is what turns a $16 product into a recurring revenue line.
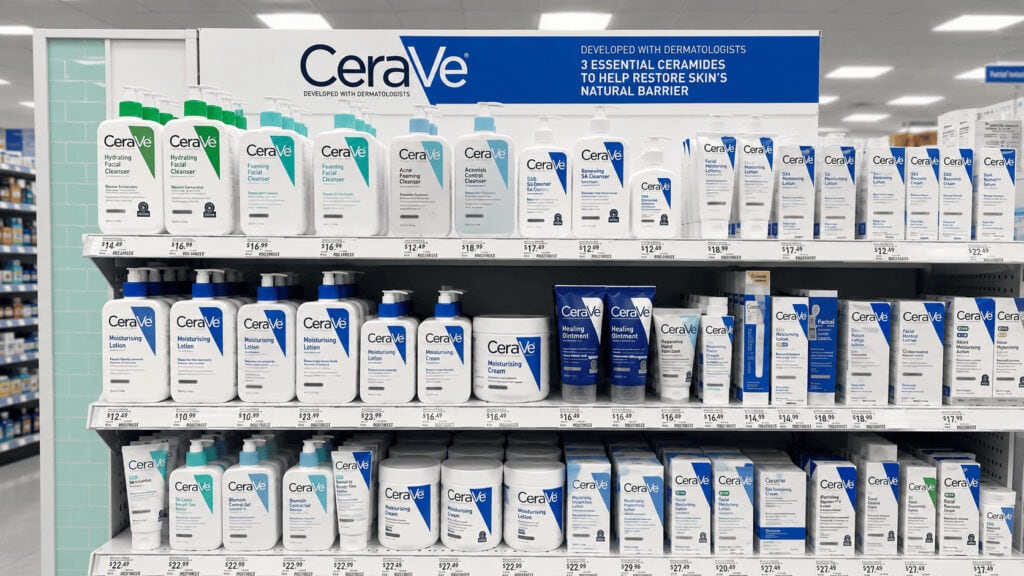
Channel behavior favors physical retail more than most people assume. Piper Sandler has repeatedly found teens prefer buying beauty in stores. CeraVe’s shelf presence in Target, Walmart, CVS, and Ulta is doing quiet work that no TikTok campaign replaces.
Technographic Segmentation
CeraVe’s growth after 2020 came from a platform it did not control. Hyram and a wave of Gen Z skincare creators on TikTok turned a dermatologist brand into a peer recommendation, and CeraVe did the smart thing by refusing to change the product to match the moment.
The Michael CeraVe campaign in 2024 was the payoff. Ogilvy seeded a fake conspiracy that actor Michael Cera had invented the brand, ran it through 450 influencers, then debunked it during the Super Bowl with a boardroom of actual dermatologists. The campaign generated 32 billion impressions, drove a 25% sales lift and the brand’s biggest moisturizer sales week ever, and took the Grand Prix in Social and Influencer at Cannes Lions.
Read the campaign structure carefully. CeraVe used a celebrity to attack celebrity skincare. That is a technographic strategy aimed at a specific buyer: the person who scrolls past Rhode and Fenty and wants to know who actually formulated the thing.
Where CeraVe Actually Wins: The Teen Data
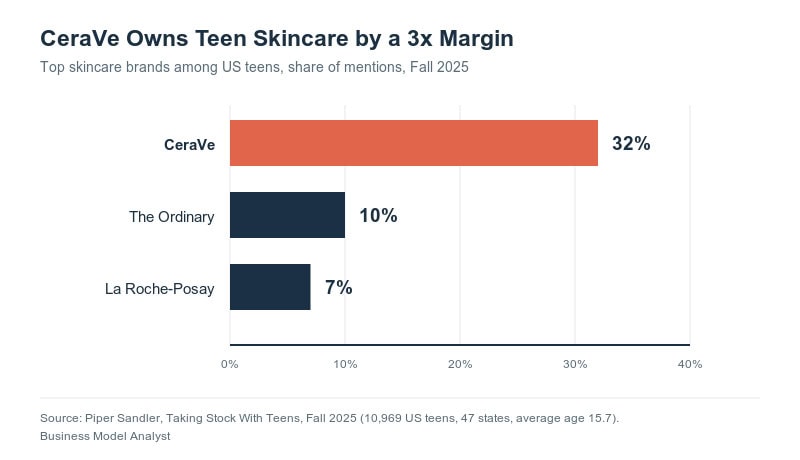
Piper Sandler’s Fall 2025 Taking Stock With Teens survey put CeraVe at 32% of US teen skincare mentions. The Ordinary took 10%. La Roche-Posay, CeraVe’s own sibling inside L’Oreal, took 7%. No other brand came close.
A 3x lead over the runner-up in the most trend-volatile consumer segment in retail is a serious asset. But look at the direction of travel.
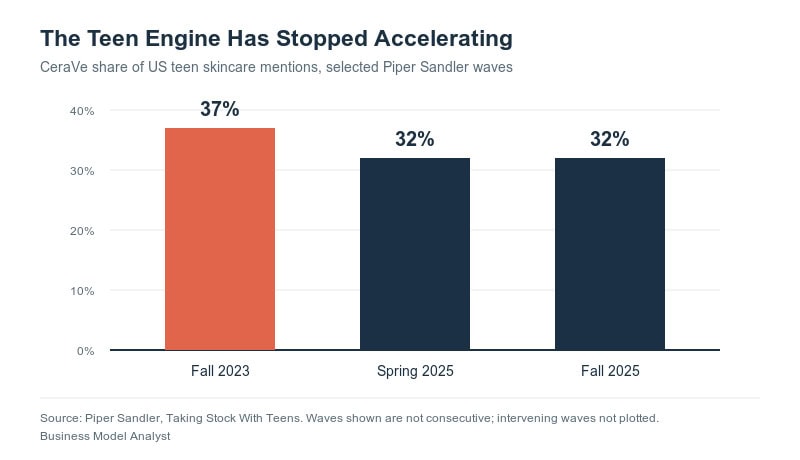
CeraVe held 37% of teen skincare mentions in Piper Sandler’s Fall 2023 wave. By Spring 2025 that had settled at 32%, and Fall 2025 came in flat at 32% again. The same Fall 2025 survey found the core teen beauty wallet contracted 2% year on year to $336.
Nobody should read a five-point drift as collapse. Read it as arrival. CeraVe has taken as much of the US teen segment as a single brand can plausibly take, and it is now defending that position rather than compounding it. Growth has to come from somewhere else.
The $10 Ceiling
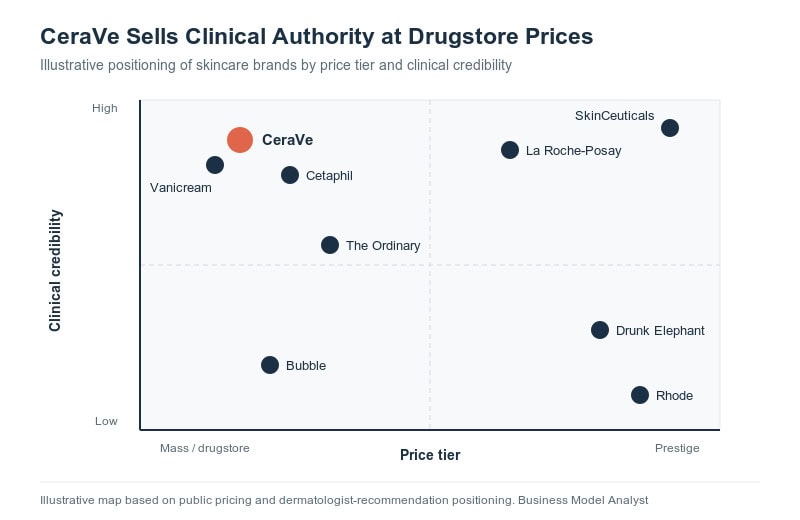
CeraVe occupies the most valuable and most dangerous square on the skincare map: high clinical credibility, low price.
The value is obvious. Nobody feels foolish buying CeraVe. The brand converts a dermatologist’s authority into a $16 purchase with no aspiration tax attached.
The danger is the ceiling. CeraVe has almost no route to premium pricing, because the moment it charges $40 for a serum it stops being CeraVe. Its 2024 haircare launch made the constraint explicit: five SKUs, all priced under $10, exclusive to Walmart. That is a volume strategy, and volume strategies are the ones dupes attack first.
Watch who is circling. Vanicream competes on the same clinical ground at a similar price. Cetaphil, owned by Galderma, has the same drugstore shelf and the same dermatologist heritage. The Ordinary, which now sits second among teens, undercuts on ingredient transparency and price at once. Private-label barrier creams from Amazon, Target, and Walmart copy the ceramide formula and sell it for less, on the same shelf, sometimes directly beneath it.
CeraVe’s moat is trust, and trust is the only asset here that a price cut cannot buy. It is also the only asset that a single formulation scandal could burn in a week.
Where the Next Buyer Comes From
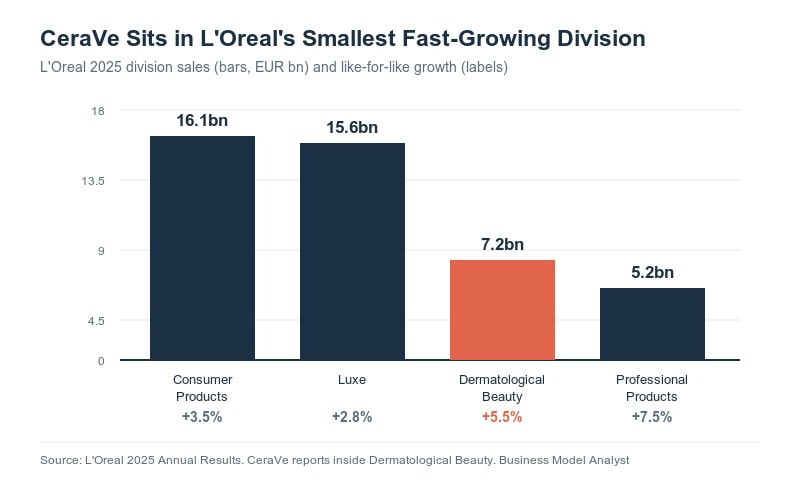
L’Oreal’s Dermatological Beauty division booked 7.2 billion euros in 2025 and grew 5.5% like for like, second only to Professional Products in growth rate and less than half the size of Consumer Products. CeraVe carries a large share of that division’s expectations, which means the pressure to find new buyers falls directly on the brand.
Three expansion segments are already in motion.
Men and teen boys. CeraVe already leads with teen boys, and it got there without a men’s line, without a men’s campaign, and without changing a single formula. The brand’s unsexed packaging did the work. L’Oreal has not built a dedicated men’s push around this, which looks like an unclaimed asset.
Haircare and the scalp buyer. The 2024 anti-dandruff launch reframed the scalp as skin. L’Oreal reported the line outpacing the market in the US in the second half of 2025 and continuing into Q1 2026. This segment brings in a buyer who never used CeraVe for the face and might now.
The emerging-market first-timer. L’Oreal reported CeraVe growing well ahead of the market in China and emerging markets through 2025 and into 2026, with sun protection making a promising start in Europe. These buyers are not switching from Cetaphil. They are entering the category, and CeraVe is capturing them at the entry point, which is where lifetime value gets decided.
How Competitors Attack Each Segment
| Segment | CeraVe’s hold | Primary attacker | Angle of attack |
|---|---|---|---|
| Teens 13 to 18 | Very strong (32% mindshare) | The Ordinary, Bubble | Price, ingredient theatre, TikTok-native branding |
| Gen Z routine builders | Strong | The Ordinary, K-beauty imports | Actives, novelty, faster trend cycles |
| Condition-led adults | Very strong | Cetaphil, Vanicream, Eucerin | Same clinical claim, longer heritage, allergy positioning |
| Parents and baby care | Strong | Aveeno, Aquaphor | Pediatrician channel, brand familiarity |
| Prestige-curious buyers | Weak by design | La Roche-Posay, SkinCeuticals | Higher perceived efficacy, same corporate parent |
| Emerging-market entrants | Growing | Local derm-cosmetic brands | Price, local formulation, regional distribution |
Two entries deserve a second look. La Roche-Posay and SkinCeuticals both sit inside L’Oreal, so CeraVe’s premium ceiling is not an accident of the market. It is portfolio design. L’Oreal wants CeraVe to stay cheap, because the trade-up path leads to brands with better margins.
What Entrepreneurs Can Take From This
Segment by problem, not by person. CeraVe never had to pick between a teenage boy and a menopausal woman, because eczema does not care about either. Condition-based segmentation gives you a bigger addressable market than demographic segmentation and a longer product life. Contrast this with identity-led brands like Nike and Lululemon, which must keep spending to stay culturally current because their segmentation rests on who the buyer wants to be rather than what the buyer needs fixed.
Borrow authority you cannot buy. CeraVe’s growth engine for fifteen years was dermatologists handing out samples. The TikTok wave amplified an endorsement that already existed. Influence built on top of professional credibility survives platform changes; influence built on a creator’s popularity does not.
Boring packaging is a strategy. The plain white bottle removed shame from the purchase and made the product usable across genders and ages. Aesthetic restraint widened the market. Compare this with how Sephora’s business model depends on discovery, theatre, and prestige adjacency to justify its price points, or how Sephora’s marketing strategy leans on loyalty gamification. Different problem, opposite solution.
Know what your price is protecting. CeraVe’s cheapness is its trust signal. Raising prices would not just cost volume, it would cost credibility. Ask which of your constraints are actually load-bearing before you try to remove them.
FAQ
Who is CeraVe’s target audience? Teens and adults with skin conditions across a wide age range, roughly 13 to 55, with household incomes near the US median. The brand skews younger in the US, where it leads teen skincare, and skews toward first-time skincare buyers in emerging markets.
Is CeraVe aimed at men or women? Both, and the gender split is unusually even for skincare. Piper Sandler found CeraVe was the number one skincare brand among US teen boys as well as teens overall in spring 2025. Fragrance-free, unadorned packaging removed the barrier that keeps many men out of the category.
What age group buys CeraVe most? Teens and young adults aged 13 to 24 drive mindshare and social visibility. Adults aged 30 to 55 drive repeat volume through condition management and household purchases.
Who owns CeraVe? L’Oreal, which acquired the brand from Valeant in 2017 as part of a $1.3 billion deal that also included AcneFree and Ambi. CeraVe sits inside L’Oreal’s Dermatological Beauty division alongside La Roche-Posay, SkinCeuticals, and Vichy. L’Oreal’s mass-market brands, including Maybelline, sit in a separate division with a different competitive job.
Who are CeraVe’s main competitors? Cetaphil (Galderma), Eucerin (Beiersdorf), Vanicream, Aveeno (Kenvue), The Ordinary, and a growing wall of retailer private-label ceramide creams. Inside L’Oreal, La Roche-Posay competes for the same clinical buyer at a higher price.
Why is CeraVe so popular with Gen Z? Ingredient transparency, dermatologist endorsement, and a price that fits a teenage budget. TikTok creators, most visibly Hyram in 2020, converted a clinical brand into a peer recommendation. The 2024 Michael CeraVe Super Bowl campaign then made that status explicit by mocking celebrity skincare on the biggest stage in US advertising.
The Business Model Analyst Take
CeraVe built the widest target market in mass skincare by refusing to have a target market at all. Segmenting by skin condition instead of by shopper identity let one product line serve a teenage boy, a new mother, and a 60-year-old with rosacea without a single line of tailored messaging. It is the most efficient consumer positioning of the last decade, and L’Oreal paid $1.3 billion for a brand that has since passed $2 billion in annual sales.
The problem sitting in the 2025 numbers is that this positioning has run out of room in its most valuable market. CeraVe holds 32% of US teen skincare mentions, down from 37% two years earlier, in a teen beauty wallet that shrank 2%. L’Oreal called the year a turnaround, which means the US skincare business needed one. Nothing about the brand is broken. It has simply finished the easy part.
The next chapter is harder and less glamorous. It runs through Walmart shampoo aisles at $9 a bottle, through sunscreen in Europe, and through first-time skincare buyers in Jakarta and Sao Paulo who have never heard of Hyram. Those buyers are cheaper to reach and worth less each, and CeraVe cannot raise its price to compensate because the price is the brand. Consider the strategic bind: L’Oreal owns La Roche-Posay and SkinCeuticals precisely so CeraVe never has to trade up, which means CeraVe’s job is volume, forever.
Watch two numbers over the next eighteen months. If CeraVe’s teen mindshare drops below 30%, the trust moat has started leaking to The Ordinary and the dupes. If Dermatological Beauty keeps compounding above 5% while CeraVe’s US skincare sits flat, the growth is coming from La Roche-Posay and SkinCeuticals, and CeraVe has quietly become L’Oreal’s volume brand rather than its growth brand. Those are different businesses, and only one of them is worth what L’Oreal is currently paying to defend.