
Caterpillar, Cummins and Eaton are having their best year in a decade selling power equipment to AI data centers. Almost none of the money is going into new factories, and that is the point.
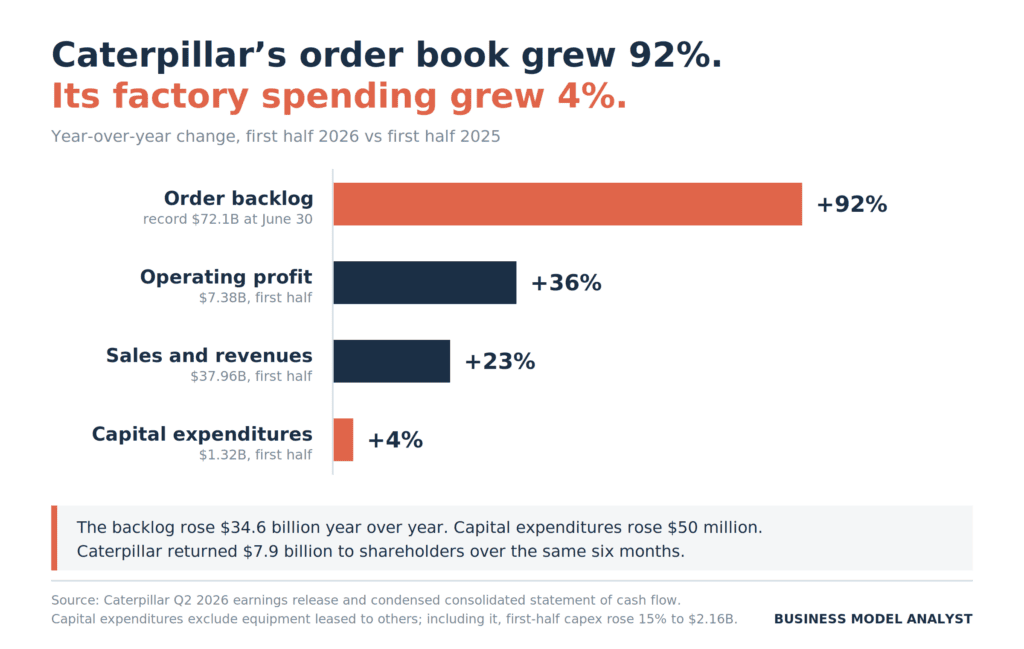
Caterpillar closed the second quarter of 2026 with a record $72.1 billion order backlog, up 92% from a year earlier. Over the same six months it raised capital expenditures by 4% and handed $7.9 billion to shareholders. The equipment makers feeding the AI buildout are converting the boom into price and backlog rather than into plant, because scarcity is what is producing the margin.
Joe Creed runs a company that cannot make generators fast enough. Data center developers keep asking for more units than Caterpillar can ship, and its backlog of generator orders now stretches to 2030. A chief executive facing that would be expected to pour money into factories. Caterpillar’s first-half capital expenditures came to $1.32 billion, up $50 million on last year. Its share repurchases came to $6.52 billion, up $2.03 billion. The company spent forty times more incremental cash buying its own stock than expanding its own capacity.
What Happened
The Wall Street Journal reported on August 15 that US manufacturing is running at its highest level since 2022, driven by data centers and a handful of AI-adjacent industries. Caterpillar, Cummins, Eaton and Ford all appear as examples of industrial companies reshaping themselves around the demand.
The numbers behind the story are extraordinary. Caterpillar posted its first quarter above $20 billion in sales, at $20.543 billion, up 24%. Operating profit rose 50% to $4.295 billion. Power generation sales, most of them tied to data centers, climbed 29% to $3.098 billion, and the Power & Energy segment delivered $2.027 billion of profit at a 24.6% margin, making it the most profitable segment in the Caterpillar business model. Price increases alone added $595 million to operating profit.
Cummins reported record second-quarter revenue of $9.46 billion, with Power Systems up 19% to $2.3 billion on data center backup demand, and raised its full-year revenue growth guidance to a range of 10% to 13%. Eaton grew sales 21% to $8.53 billion with data centers as the lead driver, and reported electrical backlog up as much as 103% year over year.
Now the other side of the ledger. Caterpillar’s first-half capital expenditures excluding equipment leased to others were $1.315 billion against $1.265 billion a year earlier. Cummins spent $249 million on capex in the quarter, up from $231 million, and guided the full year to $1.35 billion to $1.45 billion. Eaton spent $253 million on capital expenditure in a quarter when it closed the $9.55 billion Boyd Thermal acquisition and the $1.53 billion Ultra PCS deal.
Eaton bought roughly forty-four dollars of existing companies for every dollar it put into new plant. Buying a competitor moves ownership of capacity. It does not add a single unit of switchgear to the industry.
The Backstory
Caterpillar has done the other version of this, and it went badly.
In the first half of 2012 the company told investors that manufacturing costs had risen $409 million, in part because of capacity expansion programs. It had bought Bucyrus International the year before for close to $9 billion to serve a mining supercycle that looked permanent. That year turned out to be the peak. By 2015, sales had fallen to $47.0 billion, which Caterpillar itself described as 29% below the 2012 high. First-half 2016 revenue came in at $19.8 billion against $25.0 billion the year before.
The cleanup took years. Caterpillar closed or announced the closure or consolidation of more than 20 facilities covering 8 million square feet of manufacturing space, and cut its workforce by more than 31,000 people from mid-2012. Doug Oberhelman spent his final years as chief executive explaining that mining, oil and gas, construction and rail carry a long history of severe cyclicality, and that the company had to survive the downturns to enjoy the upturns.
Cyclicality has sat at the top of Caterpillar’s weakness column ever since, and every senior operator at the company today lived through it. So did their counterparts at Cummins, whose engine business tracks freight and construction cycles, and at Eaton, which sells into utilities and commercial construction. The generation of industrial managers now running the AI power boom learned capital discipline the expensive way.
The Plan
Read what these three companies are doing rather than what the headlines say they are doing.
Caterpillar is spending $725 million to expand generator production in Indiana, converted an existing Kansas plant to build turbine engines, and restarted production of 10-megawatt generators it last made in 2022. Two of those three moves reactivate assets it already owns. Restarting a mothballed line is cheap, fast, and reversible, which is exactly the profile a cyclical manufacturer wants. Caterpillar’s own investor presentation sold the story as disciplined capacity expansion executed with speed and capital efficiency.
Cummins is investing $450 million to lift generator output, following a $200 million expansion completed last year, and expects data center sales to reach $9 billion by 2030. Jennifer Rumsey told analysts that “our growth in 2026 will continue to be constrained by capacity.” In the same quarter, Cummins raised its dividend 10% for the seventeenth consecutive year and returned $1.02 billion to shareholders in the first half against $438 million of capital expenditure. Jenny Bush, who runs the power systems business, told the Journal that Cummins has been trying to “utilize as much of what we already have before we build anything new.”
Eaton chose acquisitions. It has spent about $13 billion buying companies since 2025, lifting data centers and distributed IT from 14% of sales at the end of 2023 to 21% last year. That route bought revenue and market position without committing Eaton to greenfield capacity that would sit idle if orders stop.
Ford is the clearest case. Its new Ford Energy subsidiary plans to spend $2 billion redirecting battery capacity it already built for electric vehicles toward grid storage for data centers. Ford is not building for AI. It is finding a tenant for a factory the EV slump left half empty.
The Business Model Angle
Under-building is the strategy, and the arithmetic explains why.
Caterpillar’s Power & Energy segment profit rose $473 million in the quarter. Of that, $212 million came from price and $457 million from volume, offset by higher manufacturing costs. Price carries no fixed cost behind it. Volume delivered through a new plant carries depreciation, headcount, utilities and property tax that stay on the P&L after the order book empties. A manufacturer facing demand it cannot meet has two ways to convert that demand into profit: build more units, or charge more for the units it already makes. The second option has no exit cost.
Building enough capacity to satisfy the order book would destroy the pricing power generating the record results. Every megawatt of genset capacity added by Caterpillar, Cummins and GE Vernova brings the industry closer to the point where hyperscalers can negotiate. The same scarcity is what makes a hundred-hour iron-air battery look competitive against a gas peaker nobody can actually buy, and it is why the entire Western turbine order book is booked out past 2028. The rational move for an oligopoly facing a demand shock it believes is temporary is to serve the queue slowly and price the wait.
Look at the working capital and you can see who is funding the expansion. Customer advances on Caterpillar’s balance sheet rose from $3.314 billion at the end of 2025 to $4.777 billion at June 30, an increase of 44% in six months. Buyers are prepaying to hold their place in line. Caterpillar is financing its growth with its customers’ cash while sending its own cash to its shareholders.
That is the shape of the trade. The manufacturers take the margin now, keep the fixed-cost base light, and push the risk of a demand reversal onto the party that signed the purchase order.
The Risk
The discipline protects Caterpillar. It does not protect the people reading this.
Start with what the backlog actually is. Caterpillar says 59% of the $72.1 billion ships within twelve months, which leaves roughly $29 billion sitting beyond mid-2027. Orders that far out are commitments, not revenue, and equipment orders get cancelled when capital budgets tighten. The AI power trade already split into sellers and storytellers on precisely this question of when the revenue arrives.
Price is the second exposure. A meaningful share of the profit surge came from pricing rather than units, helped by 50% tariffs on imported steel and aluminum that handed domestic producers unusual leverage. Pricing power built on a trade measure reverses when the trade measure does. Caterpillar still expects roughly $2.2 billion of tariff costs this year and booked $392 million of IEEPA recoveries in the quarter, so the tariff regime cuts in both directions on its own P&L.
Concentration is the third. A generator business selling into a dozen hyperscaler balance sheets looks diversified only until two of them pause.
Eaton carries a different risk from the same boom. Buying capacity instead of building it loaded the balance sheet. Net interest expense tripled to $201 million, long-term debt and its current portion reached $18.5 billion, and GAAP earnings per share fell 16% to $2.11 while sales rose 21%. Adjusted numbers hit records; reported profit went the other way.
The honest counterargument deserves space. Cummins has committed to roughly 20 gigawatts of incremental capacity through 2030 and told investors its capital plan supports it, so calling this an investment strike overstates the case. Caterpillar’s capex including equipment leased to others rose 15% to $2.16 billion in the half, and it spent $802 million on investments and acquisitions against $21 million a year earlier. Reactivated capacity produces real units without showing up as much capital spending, which means dollar capex understates the volume response. And if AI power demand runs for a decade, the disciplined manufacturer hands share to whoever built: GE Vernova, Mitsubishi, Generac, or a Chinese supplier that does not share the memory of 2012.
Quick Questions
Is Caterpillar’s generator business really more profitable than its construction business? Yes, on both measures this quarter. Power & Energy delivered $2.027 billion of segment profit at a 24.6% margin, against $1.947 billion and 23.3% for Construction Industries.
How big is the gap between demand and investment? Caterpillar’s backlog grew $34.6 billion year over year. Its first-half capital expenditures grew $50 million.
Why not build more if customers are begging for units? Because the fixed cost stays after the boom ends. Caterpillar expanded into the 2012 mining peak and spent the following four years closing 20-plus plants and cutting more than 31,000 jobs.
Who is paying for the capacity that does get added? Customers, partly. Prepayments on Caterpillar’s balance sheet rose 44% in six months while capital expenditures rose 4%.
Does this slow down the AI buildout? It raises the price and lengthens the queue. Equipment lead times set the schedule for data centers, and the suppliers have little incentive to shorten them. That equipment cost lands on top of the power bill the buildout is already repricing.
The Business Model Analyst Take
Harvard’s Willy Shih gave the Journal the right analogy and the wrong victim. He compared the current buildout to the late 1990s fiber boom, when carriers laid cable that sat dark for twenty years, and warned that companies adding too much capacity end up in a boom-and-bust cycle.
The carriers did die. Global Crossing and WorldCom went bankrupt. The part most people forget is what happened to their supplier. Corning held about a third of the optical fiber market and watched revenue climb from $3.8 billion in 1997 to $7 billion in 2000, with management forecasting $10 billion for 2002. Chief executive John Loose said in 2001 that “demand for optical fiber worldwide remains robust” and kept investing. Actual 2002 revenue came in near $4 billion. Corning wrote off nearly all of the $5 billion of goodwill from its acquisition spree and reported a $5.5 billion loss. James Houghton came back as chief executive, shut more than a dozen plants and cut the workforce roughly in half to 22,500. The fiber expansion at Concord, North Carolina, went dark in October 2002 and produced a $420 million impairment charge two years later. Corning shares went from above $100 to around $2.
Three-quarters of Corning’s fiber sales came from a handful of customers, several of which went bankrupt. Substitute hyperscalers for carriers and the customer profile is identical.
Caterpillar, Cummins and Eaton have read that ending. Their behavior is the tell that matters more than any executive comment about incredible demand. When the people selling the shovels price like the gold rush ends and invest like it ends, the sensible move is to weight what they do over what they say.
The lesson generalizes past this cycle. When a demand shock arrives, the question worth asking is not how much of it you can capture. It is how much of your capture requires an asset you cannot sell in the downturn. Caterpillar answered that question in 2015, and it is answering it again now with a $72 billion order book and a factory budget that barely moved.