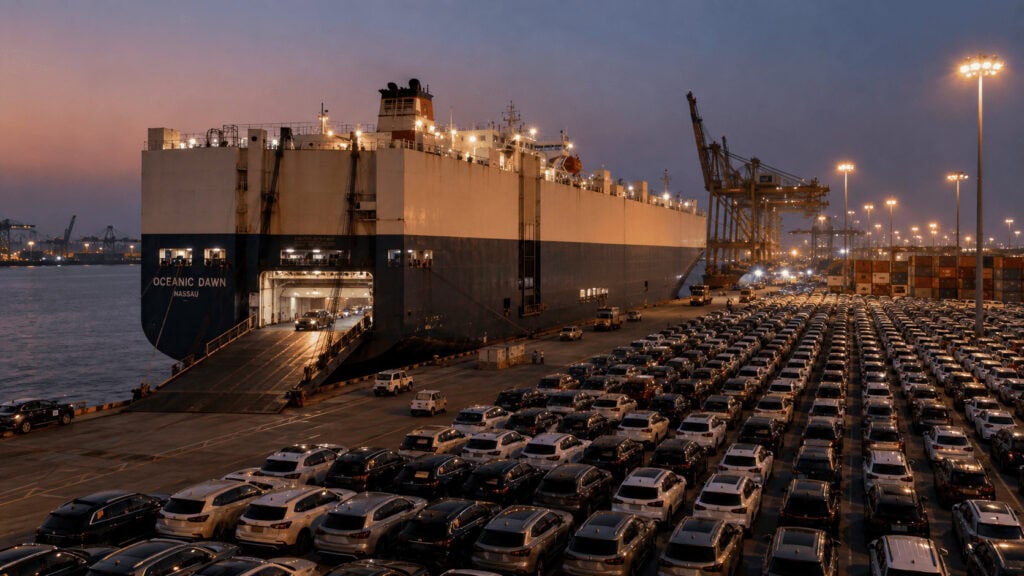

Charter rates for car carriers are up 65% this year and the specialized fleet is booked out for years ahead. Wallenius Wilhelmsen, the largest operator in the business, reported a second-quarter net profit of $138 million against $268 million a year earlier. Scarcity and pricing power are separate things, and the gap between them gets settled by whoever holds title to the steel.
Chinese vehicle exports have outrun specialized shipping capacity so far that a large car carrier chartered for $70,000 a day in June, up from $42,500 at the end of last year. The operators hauling those cars are not the ones collecting the difference. Wallenius Wilhelmsen ran at full fleet utilisation out of Asia in the second quarter of 2026 and still watched net profit fall 49% year on year. The scarcity premium is landing on whoever owns the hull, and the carmakers who created the shortage are buying their own ships to stop paying it.
Ask a shipping executive in 2024 what charter rates would look like by 2026 and you would have heard the same forecast most of them gave their boards: down. Yards were delivering the largest wave of car carriers anyone had ordered. The fleet grew about 40%. Rates went up anyway, and the biggest operator in the business made half the money it made a year ago.
What Happened
The Wall Street Journal reported on August 13 that China’s factories are building export cars faster than the world can float them. Specialized car carriers, the multi-deck vessels the trade calls PCTCs, are booked years out. Charter rates have climbed 65% this year. Some Chinese carmakers have given up waiting and are strapping vehicles inside ordinary shipping containers bound for Europe, Australia and Latin America, a method that costs more per unit and damages more cars.
The volume behind this is not subtle. China shipped just under 600,000 cars and vans in 2019, according to Mobility Global, which now forecasts as many as 10 million vehicles this year. Höegh Autoliners logged Chinese exports up 57% year on year in the first quarter of 2026. Veson Nautical put Chinese light vehicle exports up 63% year on year for January through May. Andreas Enger, who runs Höegh, describes a country that went from irrelevant to the world’s largest vehicle exporter inside five years.
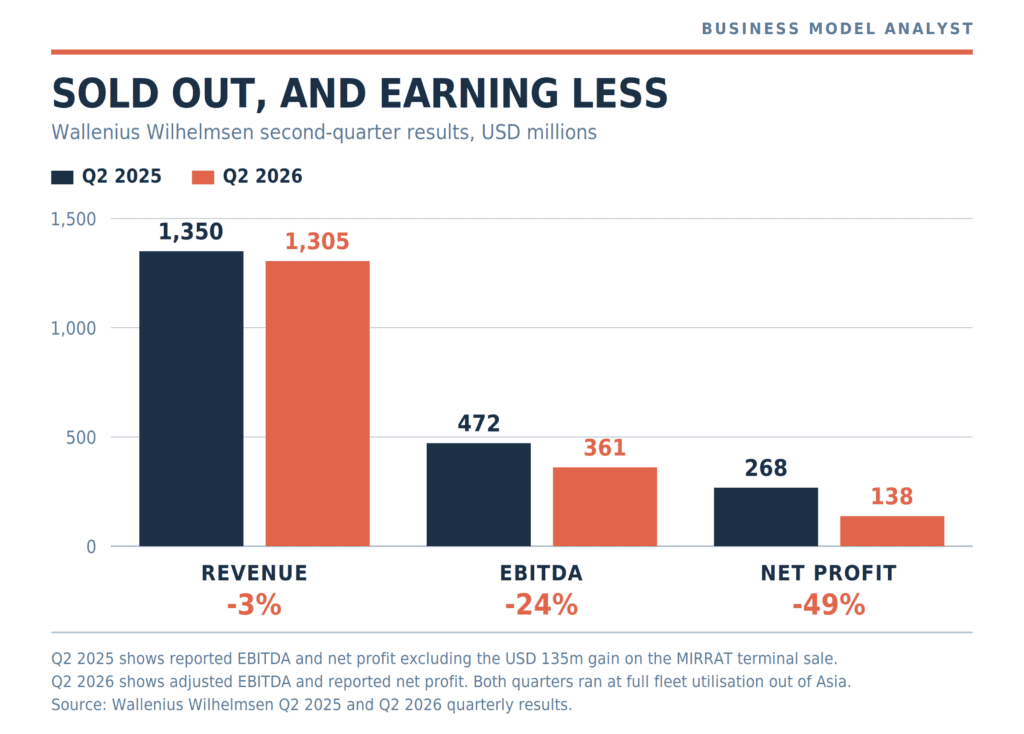
Then look at what the carriers earned from it. Wallenius Wilhelmsen posted second-quarter revenue of $1,305 million, adjusted EBITDA of $361 million and net profit of $138 million on August 11. A year earlier the same quarter produced revenue of $1,350 million, EBITDA of $472 million and net profit of $268 million once you strip out the one-off gain from selling the MIRRAT terminal in Melbourne. Revenue barely moved. Profit halved.
CEO Lasse Kristoffersen told investors the company is effectively sold out and has to choose which customers get space out of Asia. He also raised the 2026 dividend to $258 million for the first half, equal to 82% of net profit.
The Backstory
Owners spent 2022 through 2025 ordering billions of dollars of car carriers into a boom. Daily charter rates for a large vessel touched $115,000 in late 2023 and early 2024. Wallenius Wilhelmsen’s own 2025 guidance projected the global fleet growing about 13% that year and 7% in 2026, from 4.6 million car equivalent units to 5.3 million, against roughly 1% annual growth in deep sea light vehicle demand. On those numbers the market should be drowning in ships by now.
Two forces broke the forecast. Chinese cars travel much farther than the Japanese and Korean cars that used to define the trade, and Houthi attacks pushed Asia-to-Europe services around the Cape of Good Hope. Veson Nautical estimates the diversion stretches those voyages by about 25% and keeps CEU-mile demand growing around 7.3% a year through 2027. Ships are counted in car equivalent units. Customers consume them in car equivalent unit miles. A fleet that grew a fifth in capacity delivered less usable service.
The operators responded to the 2024 rate peak by selling their exposure to it. Höegh raised its contract share from 73% in 2024 to 81% in 2025 and 84% by the fourth quarter, a strategy Enger called going long on cargo. The company conceded at the time that locking in multi-year cargo diluted its rates. It also flagged rising short-term charter-in exposure on the cost side. Those two decisions, taken together, describe a company that fixed its selling price and floated its buying price about twelve months before the buying price took off.
The Plan
Everyone with money in this trade is now trying to stop renting.
Owners are ordering again. Veson counted 87,200 CEU of confirmed newbuild orders in the second quarter of 2026, up 275% on the quarter and 652% on the year. Wallenius Wilhelmsen took delivery of Arctic Tern in July, the first of fourteen Shaper-class vessels.
The carmakers went further and bought a fleet. BYD launched its first dedicated carrier in 2024 and finished an eight-ship programme with annual capacity above one million vehicles. SAIC’s logistics arm Anji runs the largest self-managed vehicle shipping operation in China and has been building its international deep-sea fleet toward 22 vessels. Geely sails its own ships to Europe. In June, BYD’s Zhengzhou unloaded roughly 5,000 electric cars at Melbourne without a merchant carrier touching the cargo.
Container lines took the third route. A.P. Moller-Maersk and Mediterranean Shipping Co. now sell vehicle space to automakers directly, according to DP World’s Christoph Seitz, who noted that Chinese manufacturers accepted cars in boxes without hesitation while Western brands resisted. Kristoffersen told investors that as many as four million vehicles leave China each year in containers or other alternatives to purpose-built carriers.
The Business Model Angle
Stack those numbers and the merchant car-carrier fleet’s real addressable market gets smaller than the headline. Take the 10 million export forecast as the top of the range. Subtract up to four million units moving in boxes. Subtract BYD’s million-plus units of owned capacity, plus whatever Anji and Geely self-carry. Both of the big figures are upper bounds, so treat the arithmetic as a sketch rather than a forecast, but the direction holds: roughly half of China’s export flow has already left the merchant charter market or never entered it.
That reframes what the shortage is worth. A rent survives only while the payer has no alternative, and the three alternatives here are all funded, operating and expanding.
Now follow the money down the stack. Three layers touch a Chinese car crossing an ocean.
The cargo owner pays the freight and has the most options. BYD’s response to a $70,000-a-day charter market was to stop participating in it.
The operator sits in the middle, owns the customer relationships and the port network, and carries the worst position in a spike. Its revenue sits inside multi-year contracts signed before the squeeze. Its costs, charter-in capacity and bunker fuel, reprice now. Kristoffersen said in May that a tightening charter market was pressuring capacity cost, and the second-quarter numbers show what that pressure does to a P&L: revenue down 3%, EBITDA down 24%, net profit down 49%.
The tonnage owner sits at the bottom, has no customers, no terminals and no service promises, and collects the entire scarcity premium. Veson puts the one-year time charter for a standard PCTC at an average $52,200 a day in the second quarter, up 14.1% in three months, with midsize vessels up 29.2%. A five-year-old standard PCTC is worth about $82 million. The asset appreciated while the operator’s earnings fell.
The founder version of this is short. In a shortage, the money goes to the party that owns the constrained resource and kept its price floating. Selling long-dated contracts feels like risk management right until the cost side reprices without you. Höegh’s 84% contract cover looked disciplined in 2025 and looks like a sold option in 2026.
The Risk
Argue the other side properly, because the operators have one.
Contract cover cuts both ways, and the downside protection arrives in 2028. Wallenius Wilhelmsen maintained full-year adjusted EBITDA guidance of about $1.6 billion, paid out 82% of first-half profit, and its Logistics division delivered its best quarter since before Covid. Bunker adjustment clauses recover fuel costs with a lag rather than never. Most of the profit decline traces to oil prices after the Middle East conflict, not to a structural loss of pricing power. An operator with terminals and inland networks sells something a shipowner cannot.
The case against the newbuild wave is stronger. Veson forecasts demand growth around 2.3% a year through 2029 against fleet supply growth of 3.3%, with rate pressure starting in late 2027. A return to Suez routing would release the 25% of voyage length the Cape diversion added, and Veson models supply outpacing CEU-mile demand by about 6% in 2028. More than 120 vessels are already old enough to scrap. Ships ordered at today’s rates deliver into that.
Two more clocks are running. US Trade Representative port fees on foreign-built vehicle carriers, set at $46 per net ton and worth roughly $1.15 million per US entry for a 6,500 CEU ship, are suspended only until November 9, 2026. They apply to all non-US-built car carriers regardless of any Chinese link, which means they hit the Japan, Korea and Europe to US routes where these operators have no China pricing power to offset them.
And the demand driver itself is a policy failure Beijing wants to fix. Chinese car sales at home fell more than 20% in the first half of 2026 per the IEA. Tu Le of Sino Auto Insights calls exports a “pressure release valve” for that. Domestic recovery, or the localisation plants BYD is building in Hungary, Brazil and Pakistan, removes the sea leg for exactly the units that pay best.
Quick Questions
Why did charter rates rise when the fleet grew 40%? Distance. Chinese exports sail farther than the Japanese and Korean cargoes they displaced, and Cape of Good Hope routing adds about 25% to Asia-Europe voyages. Capacity is sold in car equivalent units and consumed in car equivalent unit miles.
Who is making money on the shortage? Shipowners chartering out tonnage. One-year charter rates for a standard PCTC averaged $52,200 a day in the second quarter, up 14.1% in three months, and five-year-old vessel values held near $82 million.
Why is shipping cars in containers spreading if it costs more? Because the cheaper method is unavailable. Ceva Logistics’ Eric Dessupoiu says automakers prefer ro-ro on cost and damage risk and use boxes when nothing else is bookable. The container fleet is heading into oversupply, so the substitute gets cheaper as the specialist gets dearer.
Does BYD owning ships matter to the carriers? It removes over a million units a year of potential charter demand, and it is permanent. Vertical integration by your largest growth customer is not a cyclical loss.
When does the market turn? Veson points at late 2027 for rate pressure and 2028 for the inflection, assuming Suez routing returns. The USTR port fee resumes on November 10, 2026 unless the suspension gets extended.
The Business Model Analyst Take
The Journal’s framing, too few ships for too many cars, is accurate and incomplete. A capacity shortage is a financial event only for the party holding the scarce asset with an unhedged price. In this trade that party is a shipowner in Oslo or Athens with no customers, no terminals and no service obligations. The operators everyone calls the winners spent 2025 converting a spot business into a contracted one, then bought back capacity at spot prices to serve those contracts. Their revenue held. Their profit halved.
Read the newbuild orders with that in mind. Owners placed 87,200 CEU of orders last quarter into a market whose tightness rests on a war-driven detour around Africa and on a Chinese domestic slump Beijing has declared a problem to solve. A PCTC ordered in 2026 works until roughly 2051. The scarcity funding it has a plausible expiry inside three years, and the customer with the deepest pockets already opted out by building eight ships of its own.
For anyone running a business with a supplier bottleneck, the useful test comes in two parts. Which layer owns the constraint, and which layer floated its price? Answer both and you know where the margin will sit before the invoices arrive.
Reporting from Paul Berger, The Wall Street Journal, August 13, 2026. Financial data from Wallenius Wilhelmsen and Höegh Autoliners quarterly results, market data from Veson Nautical’s Q3 2026 shipping outlook and Clarksons, export data from Mobility Global, CAAM and the IEA.