
The economics of owning your own insurer, and the two numbers that decide whether it works
A captive insurance company is usually sold as a way to stop overpaying for insurance. That framing survives because nobody checks it against the composite data, and the composite data says something different. Rated US captives do beat the commercial market, by 7.6 combined ratio points on AM Best’s five-year average through 2025. But they do not beat it on claims. On claims they are slightly worse. Every point of advantage, and then some, comes from the distribution chain they removed.
That distinction is not academic. It determines the premium volume at which a captive makes sense, which lines belong in one, and why formations kept rising through 2025 and 2026 while commercial rates fell for seven straight quarters. It also explains why the IRS spent a decade building a test around captive loss ratios and lost half of it in a Texas courtroom in April 2026.
A captive insurance company is a licensed insurer owned by the businesses it insures. Instead of paying premium to a third-party carrier and losing any underwriting profit that premium generates, the parent pays premium to a subsidiary it controls, and keeps whatever is left after claims and expenses.
It is a real regulated insurance company, not an accounting entry, and it runs on the same insurance float economics that make underwriting profit worth owning in the first place. It needs a domicile license, minimum capital, an actuarial opinion, an audit, and a board. A pure or single-parent captive insures one corporate family. A group captive is owned by several unrelated businesses. A cell or protected cell rents ring-fenced capacity inside somebody else’s licensed platform.
Not the same thing as a captive agent. In distribution, “captive” means an agent who sells one carrier’s products, as State Farm’s exclusive agents do. A captive insurance company is a risk-bearing entity. The word is doing two unrelated jobs.
The one-paragraph version
You form a captive when your premium is large enough that the fixed cost of running an insurance company is cheaper than the percentage the commercial market charges you for distribution and overhead. That is an arithmetic question, not a market-timing question. The answer changes with your size, not with the cycle. Everything else people say about captives, the tax treatment, the control, the access to reinsurance, is either downstream of that arithmetic or is a reason the arithmetic sometimes fails.
At a glance
| Commercial policy | Single-parent captive | |
|---|---|---|
| Who keeps underwriting profit | The carrier | You |
| Cost shape | Percentage of premium | Mostly fixed dollars, plus fronting |
| Capital tied up | None | Minimum capital plus collateral |
| Speed to exit | One renewal cycle | Years of run-off on the tail |
| Coverage terms | The carrier’s form | Whatever the domicile approves |
| Who bears a bad year | The carrier | Your balance sheet |
| Typical annual running cost | Embedded in premium | Roughly $80,000 to $120,000, plus fronting |
The advantage is commission, not underwriting
AM Best rates more than 200 alternative risk transfer entities and publishes a Captive Insurance Composite alongside a Commercial Casualty Composite. Its August 2026 market segment report gives the five-year averages through year-end 2025. Almost every article about captives quotes the headline from that report, which is that captives run an 89.1 combined ratio against 96.7 for commercial casualty carriers. Almost nobody takes the number apart.
Here is what is inside it.
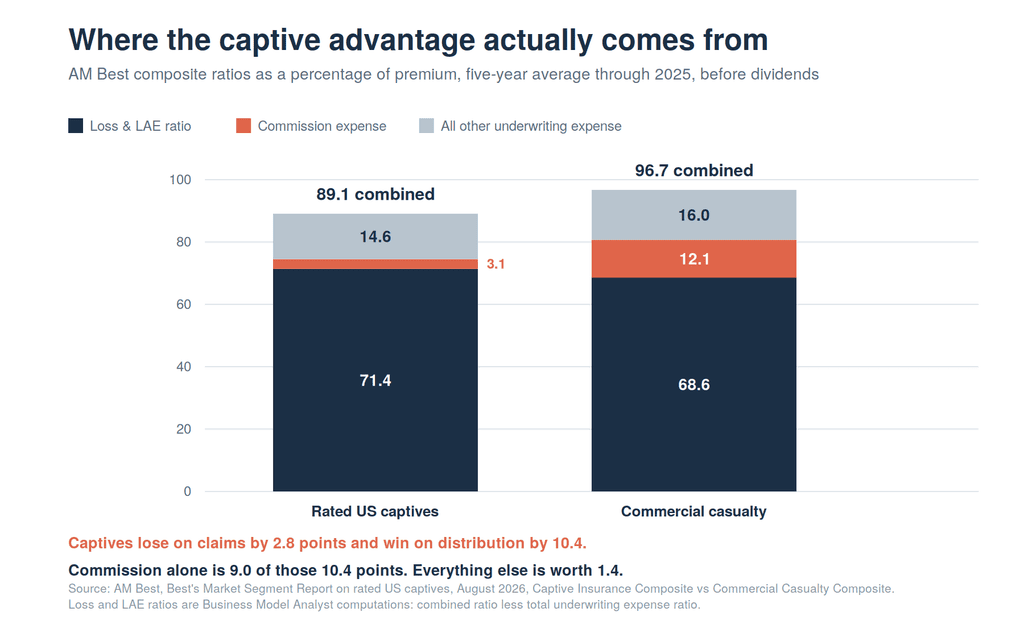
AM Best reports total underwriting expense of 17.7 for the captive composite against 28.1 for commercial casualty, and breaks out commission expense at 3.1 points against 12.1. Subtract expense from combined and you get the loss and LAE ratio, which is 71.4 for captives and 68.6 for the commercial market.
So the rated captive composite pays out 2.8 points more of every premium dollar in claims and claims handling than the commercial carriers it replaced. It wins by 10.4 points on expenses. And 9.0 of those 10.4 points are commission. On everything that is not commission, the captive is 1.4 points better, which is close to noise.
The industry’s own story about captives is that they perform because the owner understands the risk, controls the claim, and invests in safety. The composite says the owner is a marginally worse underwriter of his own risk and a dramatically cheaper distributor of it. Captives are a disintermediation trade wearing an underwriting costume.
Two caveats worth carrying. AM Best rates a self-selected slice of the captive world, skewed toward larger and better capitalized vehicles, not the roughly 6,000 licensed captives worldwide. And the higher LAE is structural rather than sloppy: a captive has no in-house claims department, so it buys third-party administration at retail while a national carrier runs it at scale. That pattern has held in AM Best’s data for well over a decade.
Which means a fronting carrier can eat the whole trade
If the advantage is nine points of commission, then anything that costs you nine points of premium cancels it.
Most captives cannot issue their own policies everywhere they need to. Certificates of insurance, lease requirements, loan covenants, and statutory lines like workers’ compensation all demand paper from an admitted, rated carrier. So the captive rents that paper. A fronting carrier issues the policy and reinsures the risk back to the captive, and charges for the privilege. Published ranges put the fee at roughly 6 to 10 percent of premium, and higher for harder programs.
Set that against the 9.0-point commission advantage:
| Fronting fee | Share of the 9.0-point commission advantage consumed |
|---|---|
| 6% | 67% |
| 8% | 89% |
| 10% | 111% |
At the top of the published range, the front costs more than the broker did. You have not disintermediated anything. You have swapped a commission you understood for a fronting fee you negotiate once a year with one of a small number of carriers willing to write the business.
This is why the same captive structure works beautifully for a company that can write directly and fails for a company that cannot. The question is not whether you like your broker. It is whether the coverage you want requires admitted paper.
The break-even is computable, and the $1M rule of thumb is not a rule
Advisers repeat a threshold: you need about $1 million of annual premium before a single-parent captive makes sense. It is stated as folklore. It is actually a solvable equation, and solving it shows what the threshold depends on.
The commercial market charges expenses as a percentage. Take AM Best’s 28.1. The captive charges them mostly as fixed dollars: captive management, actuarial opinion, audit, tax filing, domicile fees, directors. Published adviser ranges put that stack at roughly $80,000 to $120,000 a year for a straightforward single-parent captive. On top of the fixed stack sit the two proportional costs a captive cannot escape, the fronting fee and premium tax of roughly 0.4 to 2 percent.
Break-even premium is where the fixed stack equals what the commercial market’s percentage would have cost, net of the captive’s own percentage costs:
Premium = fixed cost / (0.281 − fronting % − premium tax %)

With a $100,000 stack and no fronting, the math works from about $361,000 of premium. At an 8 percent front it moves to $508,000. At 15 percent it reaches $787,000. Raise the fixed stack to $150,000 and a 12 percent front puts break-even at $955,000, which is where the folklore number comes from.
So the $1 million rule of thumb is not a rule. It is the answer for one particular combination of a heavy cost stack and an expensive front. Halve either and the threshold halves with it.
The other direction matters too. Run the same model at the $2.9 million ceiling for a small insurer electing section 831(b), with an 8 percent front, and the gross expense saving is about $571,000 against a $100,000 stack. The surplus is real and it scales, because the numerator is fixed and the denominator is not.
What the model deliberately leaves out is the money you never see again. Fronting carriers typically demand collateral of 125 to 150 percent of the projected loss fund. At a loss ratio in the neighborhood of the rated composite’s 71.4 percent, that is roughly 89 to 107 percent of one full year’s written premium, posted as a letter of credit, rolling rather than amortizing, and growing as the tail builds. A letter of credit consumes bank capacity dollar for dollar. A captive does not only convert an expense into an asset. It converts an insurance premium into a claim on your borrowing base, which is a cost your CFO feels and your risk manager usually does not model. Anyone who has run a covenant package against an SBA 7(a) acquisition loan will recognize the problem: committed credit capacity is finite, and insurance collateral competes for it.
Formations rose while prices fell, which breaks the standard story
The received wisdom is that captives are a hard-market phenomenon. Rates spike, buyers retreat into self-funding, rates fall, captives wind down. Marsh’s own commentary acknowledges that sustained soft conditions have historically slowed formations.
That is not what happened.
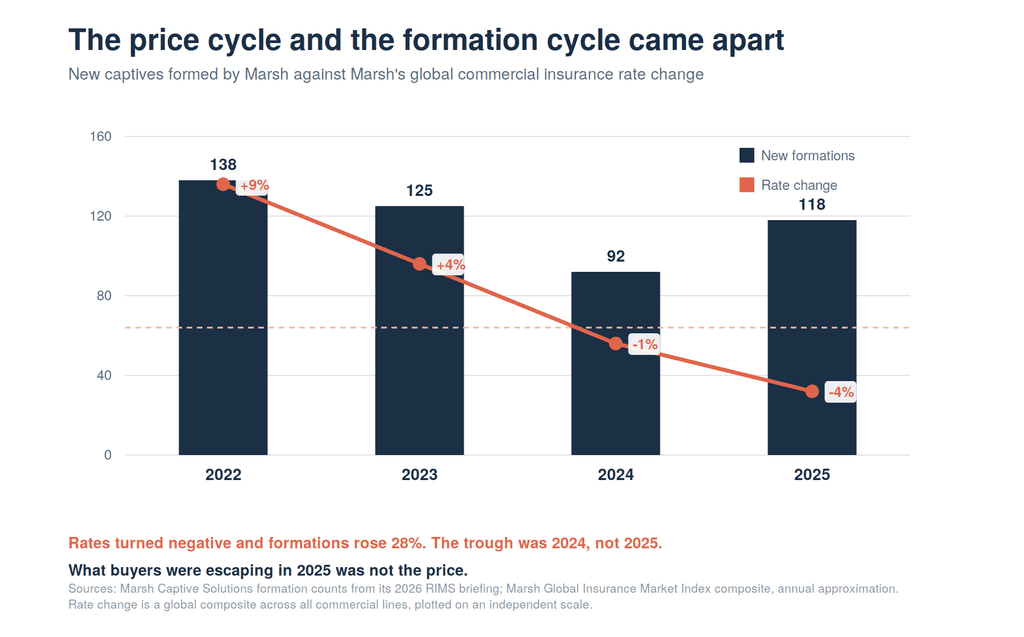
Marsh formed 138 new risk retention entities in 2022, 125 in 2023, 92 in 2024, and 118 in 2025, a 28 percent rebound in the year commercial rates fell about 4 percent. Marsh-managed captive premium reached $79.1 billion in 2025, up from $77 billion, and Fortune 500 captive premium volume rose 9 percent. The trough in formations was 2024, when rates were still positive. The recovery came after they turned negative.
Marsh’s Global Insurance Market Index has now fallen for seven consecutive quarters, hitting minus 5 percent in the first quarter of 2026 and minus 6 percent in the second, with property down 12 percent. If price were the driver, formations should be collapsing.
The explanation sits in the composition of the softening. Casualty is not soft. Marsh puts casualty up 2 percent in the same quarter property fell 12, and US casualty and commercial auto have been running up 5 to 12 percent while everything else falls. Brokers reported commercial auto up 11 percent in the first half of 2026 against commercial property down 4. In the Council of Insurance Agents and Brokers survey for the second quarter of 2026, umbrella posted its 35th consecutive quarterly increase and 40 percent of respondents saw umbrella capacity decrease, in the same quarter 75 percent saw property capacity increase.
And where price did fall, the form contracted with it. Carriers are closing exposure through exclusions rather than repricing it, a pattern visible across the standard liability forms, where new generative AI and PFAS exclusions took effect on 1 January 2026. That mechanism, carriers narrowing the form instead of repricing the risk, is the subject of our separate commercial general liability explainer.
Put those together and the picture is not a soft market. It is a bifurcated one. The half you can buy got cheaper. The half you cannot buy got harder to buy. A captive is bought against the second half, and a gap in the form does not close when the price of the rest goes down.
That is the real answer to “should I form a captive in a soft market.” The premium saving was never the point. Cheap reinsurance during a soft cycle is, if anything, the good time to build surplus before the next hard one.
What a captive actually writes
The lines that end up in captives are the ones the commercial market prices badly or will not write at all:
- Deductible and self-insured retention layers. The most common starting point. The captive formalizes risk you were already carrying and lets you fund it with a deductible premium instead of an unbudgeted claim.
- Casualty layers priced off social inflation. Excess and umbrella, where attachment points keep rising and capacity keeps shrinking.
- Property catastrophe deductibles, particularly wind and quake retentions that have grown faster than anyone’s budget.
- Cyber, where Marsh-managed captives wrote more than $170 million of premium against $30 million five years earlier.
- Medical stop-loss and employee benefits, the fastest-growing corner of the market and the main reason mid-market group captives exist.
- Genuinely uninsurable exposures: reputational risk, supply chain interruption without physical damage, trade credit in odd geographies, warranty and service contract obligations.
The pattern is consistent. Captives get the risk the market prices with a large uncertainty load, because that load is the captive’s margin. They should not get high-frequency, well-understood risk that the commercial market prices efficiently, because there is no uncertainty load to capture and the captive would simply be paying its own claims plus a fixed cost stack.
Structures, and what each one is for
| Structure | Owned by | Best for | Trade-off |
|---|---|---|---|
| Pure / single-parent | One corporate family | $500K+ of premium, real risk appetite | Full fixed cost stack, full capital |
| Group captive | Several unrelated firms | Mid-market firms too small to go alone | Shared risk with strangers, exit fees |
| Cell / protected cell | You rent a cell in a sponsor’s licensed entity | Testing the model, smaller programs | Lower cost and speed, less control |
| Risk retention group | Members in one industry | Liability lines across many states | Liability only, no property |
| Agency captive | An insurance agency | Agencies wanting underwriting profit | Conflict management with carriers |
Marsh reports single-parent captives at roughly 75 percent of the risk retention vehicles it manages, with cells growing fastest. Cells are where most first-timers should start: adviser material puts operating costs at up to half those of a standalone captive, and the cost stack is exactly what the break-even model is sensitive to.
The tax picture, and why it just changed
This is the part of the subject most likely to be out of date on the page you are reading somewhere else.
Premium paid to a captive is deductible under section 162 only if the arrangement is genuinely insurance for federal tax purposes: risk shifting, risk distribution, insurable risk, and insurance in the commonly accepted sense. Money set aside for your own future losses without those elements is not a deductible premium, it is a reserve, and reserves are not deductible. That has been settled law since long before any of the current fight.
Separately, a small insurer with net written premium at or below an inflation-indexed cap, $2.9 million for 2026, can elect under section 831(b) to be taxed only on investment income, excluding underwriting profit from tax. These are the “micro-captives.” They have been on the IRS Dirty Dozen list for most of a decade, and the Tax Court has ruled for the government in essentially every micro-captive case tried on the merits, from Avrahami in 2017 through Royalty Management in 2024.
In January 2025 Treasury finalized regulations (TD 10029, 90 FR 3534) creating a mandatory disclosure regime built on two tests. A listed transaction required a related-party financing arrangement and a modified loss ratio below 30 percent over ten years. A transaction of interest required financing or a loss ratio below 60 percent.
Then it went to court, three times, with three different results.
- E.D. Tennessee, March 2026: upheld the whole rule (CIC Services v. IRS). Now on appeal to the Sixth Circuit.
- S.D. Texas, 15 April 2026: vacated the listed transaction rule (Drake Plastics Ltd. Co. & SRA 831(b) Admin v. IRS, Judge Rosenthal), while upholding the transaction of interest rule. The vacatur was stayed to 1 May 2026 to avoid confusion over Tax Day.
- N.D. Texas, June 2026: upheld the transaction of interest rule in the Ryan litigation, treating the listed transaction question as moot because Texas had already vacated it.
So the sentence that appears on most captive pages published in the last eighteen months, that micro-captives are listed transactions carrying penalties up to $200,000, has not been accurate since 1 May 2026. What survives is the transaction of interest designation and its 60 percent loss ratio trigger. Practitioners are split on whether the vacatur reaches beyond the Drake Plastics parties, and some are advising clients to keep filing Form 8886 anyway. Both sides have appealed, and the Fifth and Sixth Circuits now have the question.
The reason the IRS lost the harder half is worth stating precisely, because it is a business-model point rather than a legal one. The court’s test was whether transactions meeting the criteria are presumptively, meaning more than half the time, not really insurance. The IRS could not show it on the record. Which is exactly what the composite data would predict.
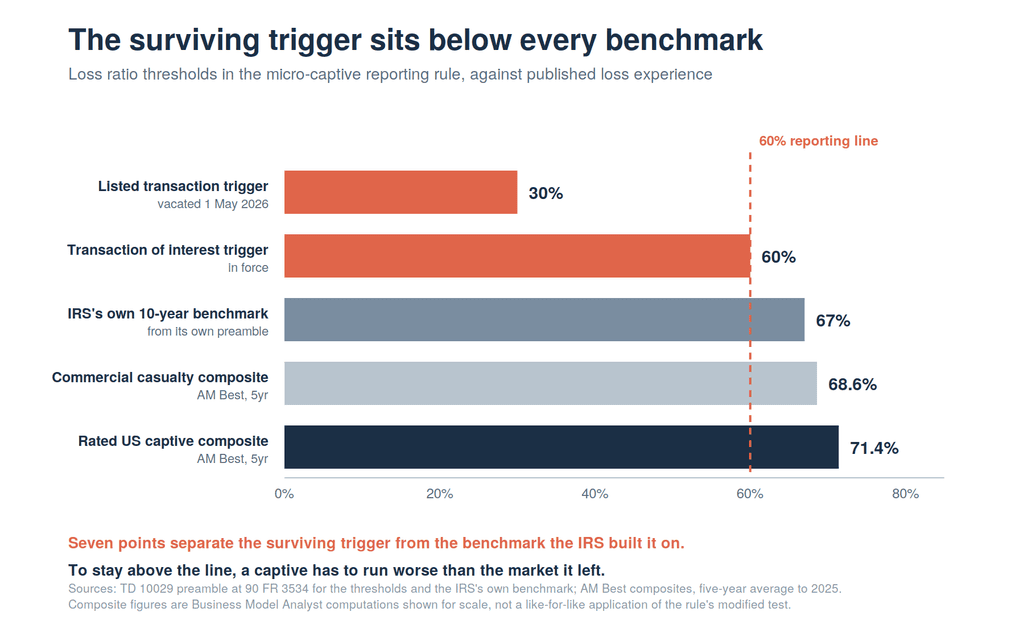
Read the IRS’s own preamble. It computed a modified ten-year loss ratio benchmark from NAIC data, stripping out the high-frequency consumer lines captives do not write, and arrived at approximately 67 percent. It then set the transaction of interest trigger at 60. Seven points of tolerance separate a typical commercial insurer from a reporting obligation, in a business where a single large claim inside a $2.9 million book swings the ratio by double digits, and where the low-frequency, high-severity coverage the IRS itself concedes is legitimate is precisely the coverage that produces long stretches with no claims.
The IRS did not pick 30 percent from theory either. It took the R.V.I. Guaranty case, averaged the five ten-year windows the Tax Court had listed, got 32 percent, and rounded down. Judge Rosenthal’s opinion notes that a lower threshold might have been needed to support a finding of presumptive avoidance, which is a striking remedy for a rule accused of catching legitimate captives.
None of this makes an aggressive captive safe. Disclosure rules and merits doctrines are different weapons. Economic substance, sham transaction analysis, section 482 and ordinary deductibility all remain available, and the Tax Court’s record on the merits is close to unblemished. What changed is the reporting overlay, not the standard.
The practical rule for anyone actually running one has not changed at all: price premiums to an actuarial opinion rather than to the statutory ceiling, cover risks you can point to, pay claims when they arise, keep the money liquid, and do not lend it back to the businesses that deducted it. Every reported loss in Tax Court failed at least three of those.
The exit nobody prices
Formation gets pitched. Dissolution does not.
Vermont, the largest domicile in the world, licensed 51 new captives in 2025 and dissolved 26, ending the year at 707 licenses against 683. Gross formations made the press release. Dissolutions equal to roughly half the gross number did not. Annual attrition ran near 3.8 percent of the licensed base.
Exit is slow because insurance liabilities are slow. You stop writing, but the tail keeps developing, the collateral stays posted until the fronting carrier releases it, the domicile keeps requiring audits and actuarial opinions on a shrinking book, and the fixed cost stack that was cheap against $2 million of premium is expensive against zero. A captive is a multi-year position taken against a counterparty that reprices annually. That asymmetry is the single most underdiscussed feature of the whole structure.
Which is also the honest counterargument to the case above, and it deserves its own weight. The Self-Insurance Institute of America’s captive survey found 83 percent of owners had not considered leaving, and AM Best puts five-year savings for its rated captive population at $8.2 billion, split evenly between surplus growth and dividends. Owners who get past the break-even generally stay past it. The failure mode is not regret. It is starting too small.
What it adds up to
A captive is not a way to buy insurance more cheaply. It is a way to stop buying distribution, and to keep the underwriting profit on risk that the commercial market prices with a large uncertainty load. The composite data says the first part is worth about nine points of premium and the second part is worth whatever your loss experience turns out to be, which may well be worse than the carrier’s.
That makes it a scale decision with a computable threshold, sensitive mostly to your fixed cost stack and to whether you need somebody else’s paper. Above the threshold it compounds, because the cost is fixed and the benefit is not. Below it, you have bought an insurance company and a letter of credit in exchange for nothing.
And it is not a market-timing decision, which is why the 2025 and 2026 data looks so odd to people who expected the soft market to end the captive boom. Rates falling 6 percent while umbrella capacity contracts and exclusions widen is not a reason to go back to the commercial market. It is a description of what the commercial market is now willing to sell.
FAQ
How much premium do I need before a captive makes sense? Between roughly $360,000 and $1 million, depending almost entirely on two variables: your annual fixed cost stack, and whether you need a fronting carrier. With no fronting and a lean $80,000 stack, break-even lands near $289,000. With a $150,000 stack and a 12 percent front, it is closer to $955,000. Run your own numbers rather than accepting the folklore threshold.
Is a captive a tax shelter? No, and treating it as one is how owners end up in Tax Court. The deduction follows from the arrangement being genuine insurance, not the other way round. A captive formed for a tax reason, priced to a statutory ceiling, and never asked to pay a claim will lose. A captive formed for a risk-financing reason that also produces a favorable tax outcome is ordinary corporate structuring.
Are micro-captives still listed transactions? Not since 1 May 2026, when a Southern District of Texas vacatur of the listed transaction regulation took effect. The transaction of interest designation and its 60 percent loss ratio trigger survive and were upheld by three courts. Both questions are on appeal in the Fifth and Sixth Circuits, so treat this as a live position rather than a settled one and take current advice.
What is a fronting carrier and do I need one? An admitted, rated insurer that issues the policy and cedes the risk to your captive, so you can hand a counterparty a certificate from a carrier they recognize. You need one wherever somebody else controls the requirement: statutory lines, lease and loan covenants, contract compliance. It typically costs 6 to 10 percent of premium plus collateral of 125 to 150 percent of the projected loss fund.
Should I form a captive in a soft market? Possibly, and the 2025 and 2026 formation data suggests plenty of companies are. Cheaper reinsurance lowers the cost of building surplus early, and the coverage gaps that motivate most captives are widening even as headline rates fall. The wrong reason to form one is a projected premium saving on a line the commercial market prices efficiently.
Can a small business use one without forming its own? Yes, and most should start there. A cell inside a sponsor’s protected cell company gives you ring-fenced capacity at materially lower operating cost, and a group captive lets mid-market firms pool risk and buy stop-loss with scale none of them has alone. Both cut the fixed stack, which is the variable the break-even model is most sensitive to.
What is the biggest cost people miss? Collateral. At the loss ratios the rated captive composite runs, a fronting carrier’s 125 to 150 percent requirement works out to roughly 89 to 107 percent of a full year’s written premium, posted as a letter of credit that rolls rather than amortizes. It consumes bank capacity dollar for dollar, and it does not appear anywhere in a typical feasibility study’s expense comparison.
The Business Model Analyst Take
Strip the marketing away and a captive is a distribution arbitrage with an insurance license attached. AM Best’s own composites say the owner is a slightly worse underwriter of his own risk and a far cheaper distributor of it, and that nine of the ten points of expense advantage is commission. Everything that follows, the premium threshold, the fronting problem, the collateral drag, the slow exit, is downstream of that one fact.
Which is why the interesting question is never whether captives work. It is whether the nine points survive contact with your specific program. If you need admitted paper on every line, a front will take most of them and you should think hard. If you can write directly, or write above a retention where nobody demands a certificate, the arbitrage is intact and it compounds with every dollar of premium you add.
The tax fight is genuinely unsettled and worth watching, but it is a sideshow to the arithmetic. A captive that clears its break-even and pays real claims on real risks was never the target. A captive built backward from a deduction was always going to lose, in 2017 and in 2026 alike, whichever way the Fifth Circuit rules.