
Who is Canva’s target market? Canva targets three groups at once: a free global majority of roughly 234 million people it deliberately does not monetize, about 31 million paying individuals and small teams who supply most of the revenue, and a growing set of business buyers with 25 or more seats who account for around 12.5% of it. The unifying customer is not the designer. It is the person who has to produce something visual and has no design department to do it for them.
Every competitor page on this topic gives the same answer, and it has been the same answer since 2015: Canva targets non-designers. That was true when the company was a template library. In 2026 it is a description of a habit, not a market.
Canva ended 2025 with about 265 million monthly active users, roughly 31 million paying subscribers, and $4 billion in annualized recurring revenue on $3.5 billion of reported 2025 revenue. It has been profitable for eight consecutive years and was valued near $42 billion in an employee share sale. Those numbers describe a company with an unusual problem for a design platform: it has almost everyone, and it charges almost none of them.
That gap is the target market story. Canva is not a company that failed to convert 234 million people. It is a company that decided most of its audience is worth more unconverted.
Three target markets pulling in different directions
The single-segment framing hides the tension. Canva runs three commercially distinct audiences under one product surface.
| Segment | Rough size | What Canva sells them | Revenue role |
|---|---|---|---|
| Free global majority | About 234M monthly users | Free tier, education, nonprofits, Affinity, Cavalry | Distribution and defence, not revenue |
| Paying individuals and small teams | About 31M subscribers | Pro and Business subscriptions | The engine, roughly 87.5% of ARR |
| Business buyers, 25 or more seats | Undisclosed account count | Brand governance, admin, Enterprise controls | About $500M ARR, the valuation narrative |
Each segment wants something the others do not. The free majority wants access with no credit card. The paying individual wants speed and a template that already looks finished. The enterprise buyer wants control, approval workflow, and the ability to stop the first two groups from putting the logo on a bad flyer.
Holding all three inside one product is the actual strategic feat, and it is also the pressure point.
Segment one: the free majority, priced at zero on purpose
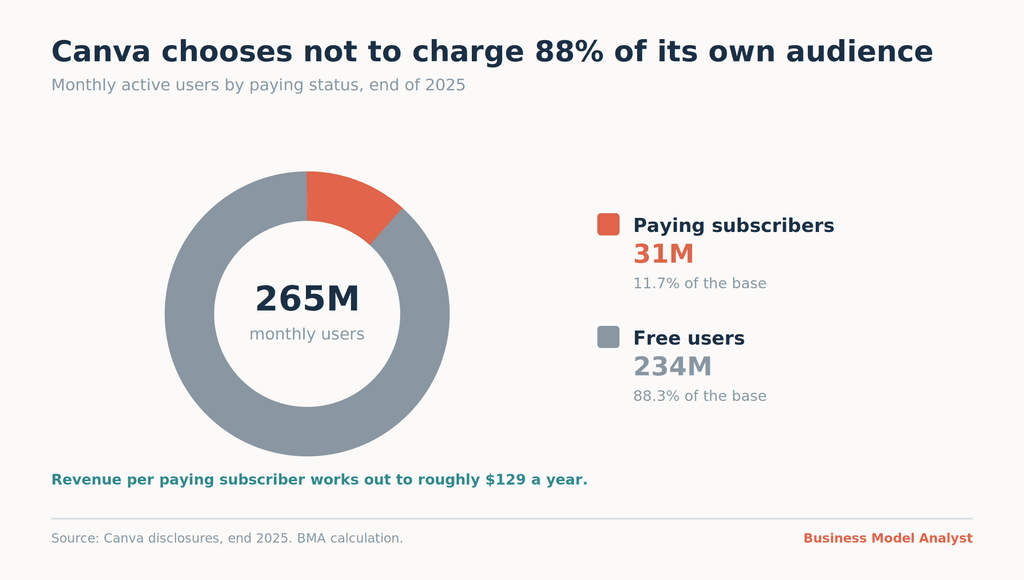
Around 11.7% of Canva’s monthly users pay for anything. For a freemium consumer product that is a strong conversion rate, well above the low single digits typical of the category. But run it the other way and the picture changes: 234 million people use a $42 billion company’s product every month and contribute nothing directly.
Canva keeps expanding that group on purpose.
Canva for Education is free for verified schools, backed by partnerships with national education ministries. Canva for Nonprofits gives registered organizations paid-tier access at no cost. In October 2025 Canva made the Affinity professional design suite, which it bought in 2024 as paid software, free forever. More than five million creatives had picked it up by April 2026. At Canva Create 2026 the company made Cavalry, a professional motion design tool, free to anyone with a Canva account, and launched Learn Grid, a curriculum-mapped teaching platform, free for every school.
Canva also shipped Canva Offline at the same event, explicitly framed around users for whom reliable internet is a luxury rather than a given. That is not a feature aimed at a marketing director in Chicago. It is aimed at the part of the base that already dominates the traffic.
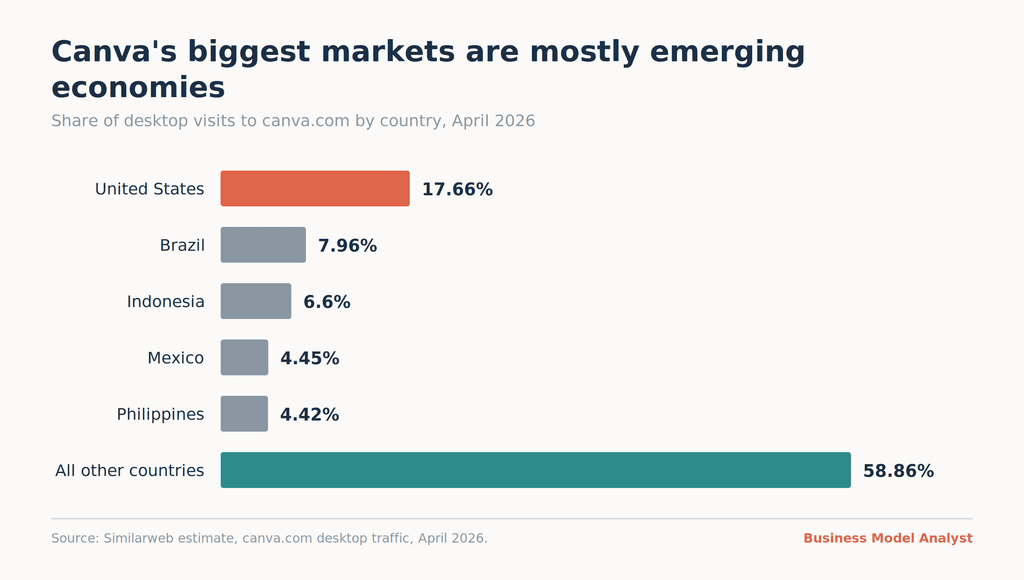
Four of Canva’s five largest markets are emerging economies. Brazil, Indonesia, Mexico, and the Philippines together send more desktop traffic to canva.com than the United States does. Canva prices regionally, so a Pro subscription costs materially less in Jakarta or São Paulo than in New York.
This is the geography and revenue mismatch that no target market page mentions: the user base skews heavily to the Global South while the revenue, by the company’s own description, still comes mostly from North America. Canva’s free tier is not generosity. It is a land grab priced to local purchasing power, with the return deferred until those markets’ small businesses mature enough to pay.
Segment two: the paying individual, who is worth about $129 a year
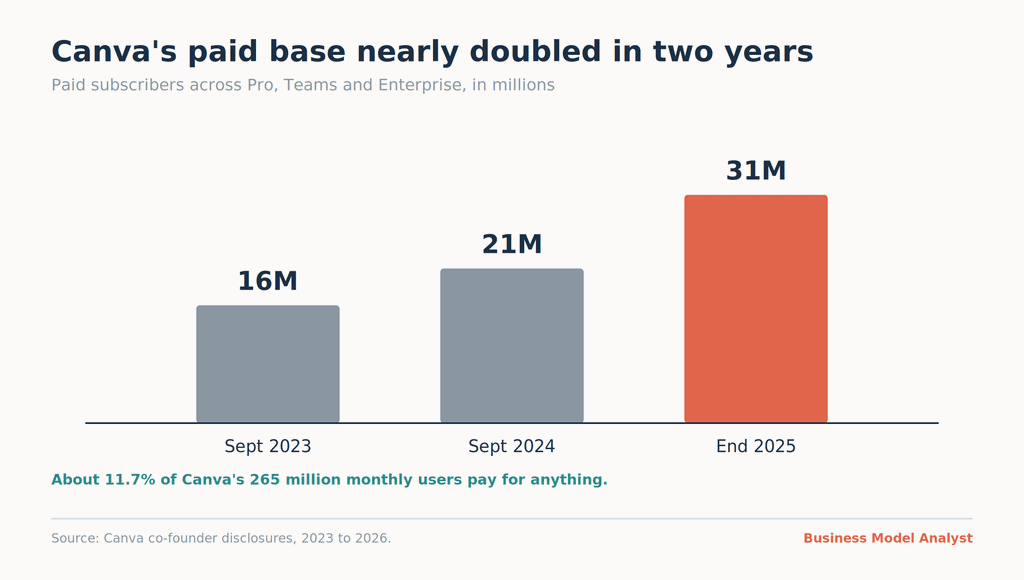
Paid subscribers went from 16 million in September 2023 to 21 million a year later to roughly 31 million by the end of 2025. That is close to a doubling in two years, and it happened while the total user base grew more slowly, which means conversion improved rather than just scaled.
Now the number that reframes everything. Divide $4 billion of ARR by 31 million paying subscribers and you get roughly $129 per paying customer per year.
That is a consumer subscription price, not enterprise software. It sits in the same band as a streaming service or a fitness app. Canva is routinely discussed as an Adobe competitor and an enterprise contender, but its average paying customer generates about eleven dollars a month. The business works because of the denominator, not the price.
This is the clearest statement of who Canva actually targets. Not the buyer with a procurement process. The freelancer, the solo marketer, the shop owner, the church communications volunteer, the teacher who upgraded on their own card. Canva’s own community language names exactly these people, and the September 2024 shift of Teams from a flat annual price to per seat was the first real attempt to charge groups more without breaking that individual price point.
The vulnerability is the flip side of the strength. A $129 relationship has no switching cost worth defending. When AI assistants started generating passable visuals inside chat windows, Canva’s response was to put itself inside those workflows rather than fight them, shipping integrations that let people create with Canva from inside other AI tools. That is the correct move for a company whose moat is habit and template library, not contracts.
Segment three: the business buyer, who is 12.5% of the story
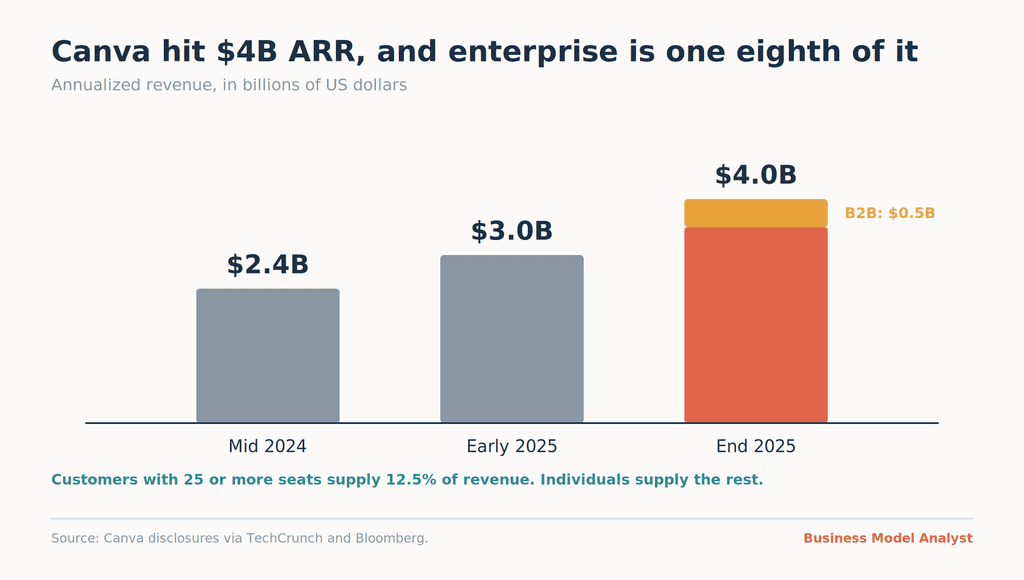
Canva launched its enterprise push in May 2024 and the B2B segment, defined as customers with more than 25 seats, roughly doubled to about $500 million in ARR by the end of 2025. Doubling is genuinely impressive. It is also doubling from a small base into a total that reached $4 billion.
So the honest read is this: Canva is a consumer and prosumer subscription business with a fast-growing enterprise attachment, not an enterprise software company. Twelve and a half percent is not nothing, and at the current growth rate it compounds quickly. But anyone modelling Canva as an Adobe substitute in the enterprise is pricing a segment that currently supplies one eighth of revenue.
Watch out for the Fortune 500 statistic that circulates on every stats page, usually cited somewhere between 90% and 95%. That figure measures whether anyone at a large company has ever made an account. It is a distribution metric dressed up as a sales metric. Canva’s real enterprise question is how many of those logos have a signed contract with seat governance attached, and the $500 million figure is the answer to that question.
The genuine enterprise obstacle is not features. It is governance. Independent analysis coming out of Canva Create 2026 flagged intellectual property control as the gating issue for enterprise adoption of Canva AI 2.0, since generative output that reproduces protected brand elements is a legal problem for the buyer, not for the tool. A platform that can generate, distribute, and optimise content end to end is only an asset to an organization that has approval workflow to match. Most do not.
The professional designer is a moat, not a customer
Here is the part that most target market analysis gets wrong.
Canva bought Affinity in 2024, initially promising to preserve its pricing, then made it free in October 2025. It made Cavalry free in 2026. It added Affinity integrations with Capture One and DaVinci Resolve and an AI connector that automates production tasks. On the surface this looks like Canva finally targeting professional designers.
It is not. Professional creatives are not the revenue target. They are the reason Adobe cannot use its entry-level tier to defend the middle.
Adobe’s historical funnel worked because a student or junior designer learned the professional tool, then carried it into a job and expensed it. Canva removing the price from a credible professional alternative attacks that funnel at the point of habit formation, not the point of sale. The money still comes from the marketing coordinator sitting next to that designer, on a $129 subscription, using templates the designer approved.
Giving away the professional tier is a defensive move financed by the prosumer tier. That is a target market strategy defined by who a company refuses to charge, which is rare enough to be worth naming.
What an IPO does to this structure
Canva’s largest venture backer reportedly told its limited partners the company is ready for a second-half 2026 listing, while other reporting has pointed to 2027. No S-1 has been filed.
Whenever it happens, public markets will apply pressure in exactly the direction that damages this target market design. Free education users, free nonprofits, free Affinity, free Cavalry, and regional pricing in high-growth low-ARPU markets are all long-horizon investments that show up as cost and dilution in the near term. A public Canva will be asked, every quarter, why it does not charge the 88%.
The counterargument a skeptic should also hear: Canva has been profitable for eight years while doing all of this, which suggests the free tier is cheap to serve and the growth is not being bought. If that holds, the structure survives scrutiny. If AI inference costs make the free tier expensive, it does not.
Frequently asked questions
Who is Canva’s ideal customer? A non-designer with a recurring visual output obligation and no design team. In practice that means solo marketers, small business owners, teachers, content creators, and internal communications staff. Canva’s paid product is priced and packaged for individuals and small teams, not for procurement departments.
What age group uses Canva most? Third-party traffic estimates put the largest visitor cohort at 25 to 34 years old, with the audience skewing female at roughly 60% to 40%. That profile is consistent with a user base concentrated in marketing, education, and small business roles.
Is Canva aimed at businesses or individuals? Both, but the revenue split is lopsided. Customers with 25 or more seats supplied around $500 million of about $4 billion in annualized revenue at the end of 2025, which puts individuals and small teams at roughly seven eighths of the business.
Does Canva compete with Adobe for the same customers? Only at the edges. Adobe monetizes creative professionals and enterprise creative departments. Canva monetizes people adjacent to those departments who need output rather than craft. Canva’s free professional tools are aimed at Adobe’s acquisition funnel rather than its installed base.
Why does Canva give so much away for free? Free access is the acquisition channel and the competitive defence. It builds habit in markets where paid conversion is years away, keeps a professional alternative permanently available at zero cost, and produces a base large enough that an 11.7% conversion rate still yields 31 million subscribers.
The Business Model Analyst Take
The common description of Canva’s target market, non-designers who want easy design, is accurate and almost useless. It describes 265 million people and explains none of the company’s decisions.
The useful version is that Canva runs a deliberate two-speed market. It monetizes a narrow band of individuals and small teams at roughly $129 a year, and it uses every dollar of that margin to keep the rest of the world on a free tier that competitors cannot profitably match. The free majority is not a conversion failure waiting to be fixed. It is the product’s distribution system, its competitive moat, and its option on emerging markets that cannot pay Western prices yet.
The risk is that this design has never been tested in public markets, and it depends on two things staying true: that serving free users remains cheap in an AI cost environment where it may not, and that the $129 relationship holds when the same output becomes available inside general-purpose AI assistants for nothing.
Canva’s answer so far has been to move faster than the question. Free professional software, free classroom tools, offline access, and distribution inside rival AI products are all the same play, which is to make the free tier so complete that no one has a reason to go looking. It is an expensive way to defend a market. It is also, on the evidence of eight profitable years, apparently affordable.