
A Maine fishing camp full of veteran money managers spent a weekend doubting the AI trade. None of them sold. The explanation sits in their fee structure, not their forecast.
The Wall Street Journal spent a weekend at Camp Kotok, an invitation-only fishing retreat in Grand Lake Stream, Maine, where roughly the same group of economists and money managers has gathered each August for about twenty-five years. The reporting found unanimous private anxiety about artificial intelligence spending and near-unanimous long positioning. That combination is not a mood. Bank of America measured the identical gap the same week across 180 institutional managers running $525 billion, and the gap has a mechanical cause: an active manager who trims artificial intelligence today is placing the single largest active bet available to him, financed out of his own fee revenue. Julian Robertson made that bet in 1999 and lost his firm for it three weeks before he was proved right.
Peter Boockvar, chief investment officer at OnePoint BFG Wealth Partners, gave the Journal the line that carries the whole story. “There’s a party going on. People don’t want to leave early.”
What Happened
Hannah Erin Lang reported from Leen’s Lodge on August 22. The event runs under the Chatham House rule, so attendees can describe the topics but not attribute them, and the named quotes came from on-the-record exchanges. David Kotok, chairman and chief investment officer of Cumberland Advisors, started the gathering after September 11 as a fishing trip for survivors and built it into an annual fixture that draws chief economists, Federal Reserve alumni and fund managers.
The 2026 edition ran on one subject. A tech investor named Barry Norton presented on scientific advances in artificial intelligence and got asked whether the trillions of dollars now committed will ever earn a return. He told the room he does not know and that Wall Street does not know either, and said the question worries him. Adam Phillips of EP Wealth Advisors told the Journal that last summer’s version of this conversation carried nowhere near the same anxiety, and described the shared ignorance as unsettling.
The campers debated whether Leopold Aschenbrenner’s collapse was a warning. His fund, Situational Awareness, launched in July 2024 and reached roughly $45 billion. Reported leverage ran as high as 400% against a book that was long the artificial intelligence supply chain and short software firms the technology might displace. Public filings at the end of the first quarter showed positions in Nebius, Bloom Energy, Sandisk, CoreWeave, SharonAI and IREN. When the memory and semiconductor complex sold off through July, margin calls forced him to liquidate the entire public book to Ken Griffin’s Citadel. Assets fell to about $10 billion. Some campers privately wondered whether it was the cockroach Jamie Dimon warns about, the first visible problem that signals more behind it.
Nobody at the camp acted on the fear. Attendees told the Journal they had moved from overweight large-cap technology to neutral and looked at other sectors of the index. Not one of them is short.
The Backstory
The July drawdown that broke Aschenbrenner was violent without being a crash. The Philadelphia Semiconductor Index gave up more than a trillion dollars of market value in days. Micron dropped 13% in one session. Intel fell 21% over seven trading days. South Korea’s Kospi lost close to 10% intraday and tripped circuit breakers while Samsung and SK hynix each slid into double digits. Samsung had reported preliminary second-quarter operating profit of 89.4 trillion won, up more than eighteen-fold on the year, and the stock fell 7% on the print.
Earnings were not the problem. Position size was. A rotation out of one crowded trade, with no accompanying deterioration in fundamentals, removed 35 billion dollars of a hedge fund’s assets and most of its reputation inside a month.
Around the same window the bond market absorbed its own version of the story, which we traced through the Treasury curve last week: the front end has not moved since June, so the selloff in the long bond carries no Federal Reserve component at all. Treasury sold thirty-year paper at 5.216% on August 13, the most expensive thirty-year auction since 2001. On August 18 gross federal debt crossed $40 trillion for the first time, five months after it crossed $39 trillion. Camp Kotok has a precedent for this: fifteen years ago the campers were sitting down to lobster when Standard and Poor’s downgraded United States Treasury debt, and they spent that night predicting the fiscal position would get worse.
The Plan
Trace what the professionals did rather than what they said, and the picture is unambiguous.
Bank of America fielded its Global Fund Manager Survey between August 7 and 13, days before the campers reached Maine. Of 180 panellists managing $525 billion, 32% named an artificial intelligence bubble as the biggest tail risk in markets, the top answer for a second month. A separate question found 38% expecting hyperscaler capital spending on artificial intelligence to be the most likely source of a systemic credit event.
The same 180 people held cash at 3.5% of assets under management. That is the sixth-lowest reading in the survey’s history going back to 1998, and it trips Bank of America’s own contrarian sell signal, which fires at or below 4.0%. Global equity allocation stood at a net 56% overweight, the highest since November 2021 and the fourteenth consecutive month of overweight positioning. A net 37% expected double-digit global earnings growth over the coming year, the most bullish reading since August 2021. And 71% said no hyperscaler will cut capital spending in 2026, up from 61% in July.
Managers who identify hyperscaler capital expenditure as the likeliest trigger of a credit event are also betting, at a rate of nearly three to one, that the spending continues. Both positions can be held at once. Holding both is the entire subject.
The Business Model Angle
Asset managers are paid a percentage of assets under management. Assets stay when relative performance holds up against a benchmark and leave when it does not. The benchmark is the constraint that decides everything downstream, and the benchmark has changed shape.
The ten largest companies in the S&P 500 accounted for roughly 38% of index market capitalisation in July 2026 on FactSet data, about ten percentage points above where the dot-com leaders topped out. The Magnificent Seven alone run near a third. Forty cents of every passive dollar lands in ten companies whose valuations rest on the same capital expenditure cycle.
Under that arithmetic, a manager who takes artificial intelligence exposure below index weight is not reducing risk. He is running a concentrated short against 38% of his benchmark, funded by the fee stream that pays his staff. The cost of being early shows up in S&P Dow Jones Indices’ 2025 scorecard: 79% of active large-cap United States equity funds trailed the S&P 500 last year, against 65% in 2024, the fourth-worst year for stock pickers in the scorecard’s twenty-five-year run. S&P’s own explanation was that relentless outperformance by the largest companies swamped the dispersion that normally gives active managers something to work with. Owning anything other than the top of the index cost money in 2025, and the people who own the money noticed.
Boockvar told the Journal his peers remember the managers who called the top too early and got wiped out. He is describing Julian Robertson, and the record deserves more attention than it gets.
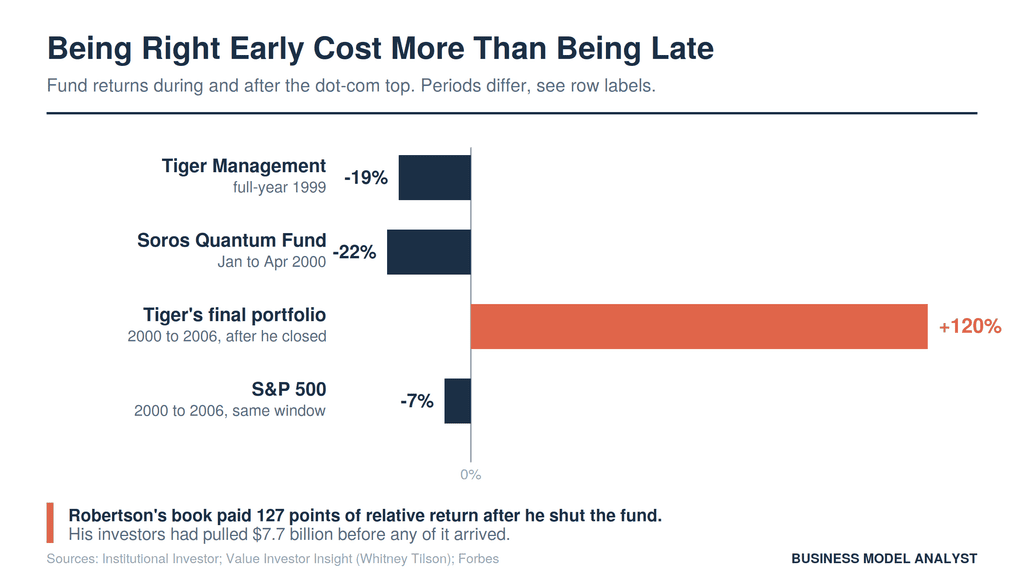
Robertson started Tiger Management in May 1980 with $8.8 million and compounded at 31.7% after fees against 12.7% for the S&P 500. By 1998 he ran $22 billion. He decided the internet mania was untethered from any defensible reality, refused to own it, and lost 4% in 1998 and 19% in 1999 while the technology complex ran. His investors pulled about $7.7 billion. On March 30, 2000 he closed the funds and returned $6.5 billion to whoever was left, twenty days after the Nasdaq Composite peaked. Whitney Tilson’s Value Investor Insight later tracked the portfolio Robertson had been holding when he shut down: it returned 120% between 2000 and 2006 while the S&P 500 lost 7%. He was right, the thesis paid 127 percentage points of relative return, and his clients had already redeemed out of the position before any of it arrived.
Look at the other road, because Camp Kotok is currently on it. Stanley Druckenmiller reached the same conclusion as Robertson and sold Quantum Fund’s entire technology book in January 2000 on the view that valuations had stopped making sense. Through March he watched the rally continue, capitulated, and put roughly $6 billion back into the same names. He has since described the timing as buying an hour before the top. By his own accounting that trade cost the fund about $3 billion. On April 28 he and George Soros told reporters Quantum was down 22% for the year, and Druckenmiller resigned.
Robertson held his doubt and lost the firm. Druckenmiller acted on his doubt, reversed under performance pressure, and lost the seat. What the camp is doing now, keeping the doubt in one hand and the buy order in the other, is not the safe middle path between those two outcomes. It is Druckenmiller’s March.
The structural fault is a duration mismatch, and this cluster has now found the same one twice. In the compute-financing platforms, thirty-year annuity liabilities fund chips their vendor replaces every two years, an exposure we traced through Nvidia’s residual-value arrangements. In asset management, a five-year thesis is funded by a redemption right the client can exercise next quarter. Both structures work while nobody asks for the money back. Robertson’s $7.7 billion of redemptions was the gap closing.
The Risk
Concentration is the exposure here, not valuation.
The bull case on fundamentals is real. JPMorgan put the Magnificent Seven’s aggregate profit margin at 23.5% in the June quarter against 8.5% for the other 493 companies in the index. Robertson was short a sector with no earnings. Today’s mega-caps generate cash at a scale that has no 1999 analogue, which is why we have argued the bubble framing asks the wrong question and the useful question is where the margin pools as it moves down the stack.
The danger sits somewhere else. When a professional class holds a position for reasons that are partly unrelated to the underlying asset, the exit is one door. Aschenbrenner is the working demonstration. A $45 billion fund lost most of itself in a rotation, in a market that did not crash, because the trade it held was the trade everyone else held. Bank of America’s crowding measure captures the mechanism: long global semiconductors was named the most crowded trade by a record 82% of managers in July and 53% in August. That fall is the unwind, and it happened without any change in the earnings picture.
Three counterarguments deserve room. First, the survey is a contrarian indicator and has been early before, so low cash may say more about conviction in growth than about coercion. Second, the campers did trim, moving from overweight to neutral, which is a real portfolio decision rather than paralysis. Third, career risk explains too much. It fits any behaviour after the outcome is known, and if artificial intelligence pays off across 2027 the same positioning gets relabelled as sound judgment. Treat it as a description of the incentive, not a prediction of the price.
Quick Questions
Are fund managers actually bearish on artificial intelligence? No. They rank it as the biggest tail risk and the most likely source of a credit event while holding the lowest cash levels since February and the highest equity allocation since November 2021.
Why does index concentration change the calculation? With the ten largest companies at roughly 38% of the S&P 500, underweighting them is a large active position rather than a defensive one. A manager who is wrong for two years about that loses clients before the thesis resolves.
Did anything actually break in July? Situational Awareness fell from roughly $45 billion to about $10 billion and sold its whole public equity book to Citadel, without a broad market crash. Semiconductor stocks shed more than a trillion dollars of value across days.
What did Camp Kotok attendees change? They moved technology from overweight to neutral and looked at other index sectors. None of them went short.
Is this the same as 2000? The earnings are not. The Magnificent Seven produced a 23.5% aggregate profit margin last quarter against 8.5% for the rest of the index. The positioning dynamics rhyme; the cash flows do not.
The Business Model Analyst Take
Camp Kotok is not a market signal. It is a positioning signal, and the two behave differently when they break.
If you run a business whose plan assumes artificial intelligence capital expenditure keeps flowing, price in the difference. A share of that flow is conviction about compute demand, and it will hold through a bad quarter. Another share is a professional class that cannot underweight 38% of its own benchmark without risking its franchise, and that share unwinds at the speed of a redemption notice rather than the speed of a business cycle. Aschenbrenner measured how fast that is: weeks, with earnings still beating.
The instruction that follows is narrow. Stop reading fund-manager sentiment as a forecast of demand. Read it as a measure of how many holders would leave if leaving stopped being expensive. On the August numbers, 38% of the professionals surveyed named their own largest exposure as the most likely source of the next credit event and bought more of it, because their compensation is measured against an index that already owns it. That is not a view about artificial intelligence. It is a view about who signs their next contract.
Norton gave the room the honest version of where this lands. Everybody jumps into a technological revolution, and when the music stops, somebody is left holding the bag. The useful addition is that the bag-holder is rarely chosen by conviction. He is chosen by whoever has the shortest redemption window.