
The Whopper upgrade costs $4,000 per store per year. The turnaround it gets credit for sits on top of a $1.5 billion bet that Restaurant Brands International is trying to unwind.
Burger King’s US comparable sales rose 8.5% in the quarter ended June 30, beating the burger category by more than nine points and lapping McDonald’s, which managed 0.8% with guest counts falling. Tom Curtis, president of Burger King US and Canada, credits the revamped Whopper. That revamp changed the bun, the mayo, the produce and the wrapper, and cost each restaurant about $4,000 a year. Across roughly 7,000 US restaurants, the whole thing runs about $28 million annually, a quarter of one percent of Burger King’s system sales.
The expensive part of this turnaround shows up in a segment almost nobody mentioned. Restaurant Brands International owns about a thousand Burger King restaurants outright, bought in a $1 billion deal in 2024, and parks them in a reporting segment called Restaurant Holdings. In Q2 those restaurants ran a 9.0% comp, better than the system, and turned $506 million of sales into $17 million of adjusted operating income. That is a 3.4% margin. The franchisor segment, collecting royalties and rent on the same brand, turned $397 million into $137 million. That is 34.5%.
The 8.5% is not a victory lap. It is the sales pitch.
What Happened
RBI reported Q2 2026 revenue of $2.52 billion, up 4.5%, and adjusted diluted EPS of $1.07 against a $1.03 consensus. System-wide sales reached $12.7 billion. Consolidated comparable sales accelerated to 3.8% from 2.4%.
Burger King carried it. US comps rose 8.5%, up from 1.5% a year earlier and roughly double what analysts expected. Burger King International added 5.4%. Reuters reported the US number leaned on the “2 for $5” and “3 for $7” value deals as much as on the burger itself.
The rest of the portfolio dragged. Tim Hortons Canada, which still generates around 40% of adjusted operating income, grew 0.1% and missed consensus. Popeyes US fell 5.1%. Firehouse Subs comps came in at 0.7% in the US, with system growth coming from opening restaurants rather than selling more in the existing ones. CEO Josh Kobza told investors that Popeyes marketing had underperformed and should turn positive in the second half.
Shares fell 1% to 2% on the day.
| Segment | Comparable sales | Q2 revenue | Adjusted operating income |
|---|---|---|---|
| Tim Hortons | 0.1% | $1.14B | $287M, up 3.2% |
| Burger King (franchisor) | 8.6% | $397M | $137M, up 13.2% |
| Popeyes | (5.1)% | $199M | $63M, down 5.4% |
| Firehouse Subs | 0.4% | $62M | $17M, up 11.4% |
| International | 5.5% | $274M | $194M, up 13.2% |
| Restaurant Holdings | 9.0% | $506M | $17M, up 3.0% |
One number deserves a second look. Organic adjusted operating income grew 6.7% in the quarter against a full-year target of 8%. The best Burger King quarter in years produced below-target profit growth for its parent.
The Backstory
Burger King spent the 2010s becoming an asset-light royalty machine. By 2013 the new owners had franchised out almost the entire system. Royalties and rent came in, operating risk went out, and the balance sheet stayed clean. The trouble with that structure shows up when the restaurants themselves start to rot. A franchisor cannot remodel a building it does not own, and franchisees running thin cash flows will not either.
By September 2022, Burger King’s US average unit volumes trailed McDonald’s badly and the physical estate looked its age. RBI announced Reclaim the Flame, a $400 million commitment split between advertising and digital, called Fuel the Flame, and remodels, kitchen equipment and technology, called Royal Reset. RBI later raised the total to up to $700 million through year-end 2028, with $550 million of it earmarked for Royal Reset.
Money alone did not solve it. The largest franchisee, Carrols Restaurant Group, ran 1,022 Burger King restaurants across 23 states and about 14% of the US system. Carrols was remodeling roughly 45 restaurants a year. At that rate the estate would never catch up.
So in January 2024 RBI bought Carrols for about $1 billion and closed in May, funding it by upsizing a term loan from $5.2 billion to $5.9 billion. RBI committed a further $500 million, drawn from Carrols’ own operating cash flow, to remodel more than 600 of the acquired restaurants. Remodels jumped from 45 a year to a planned 120.
Then came the part that explains the current quarter. RBI said from day one it would sell the restaurants back.
The Plan
Buy the operator. Fix the restaurants. Fix the comp. Sell the restaurants to smaller local franchisees at a price the new comp supports. Book royalties and rent forever.
RBI states the intention plainly in its filings. It created the Restaurant Holdings segment to house the Carrols restaurants, along with Popeyes China and Firehouse Subs Brazil, and describes the goal as refranchising the vast majority of them and sunsetting the segment. Burger King plans to keep a couple of hundred restaurants for training and testing. Everything else goes.
The timetable keeps accelerating. The original plan gave RBI five to seven years. Kobza told investors in February 2025 that refranchising had already begun, two years ahead of schedule, and would speed up through 2026. RBI announced the sunset of the segment in February 2026.
Nobody sells a restaurant well into a declining comp. A buyer prices a franchise off its cash flow, and a franchise with negative traffic prices badly. An 8.5% comp changes the conversation with every prospective operator in every market where RBI is holding inventory. Curtis told the Wall Street Journal the brand has “runway ahead for years to come.” He is talking to customers. He is also talking to buyers.
The Business Model Angle
Two companies operate the same Burger King restaurants, and RBI is both of them.
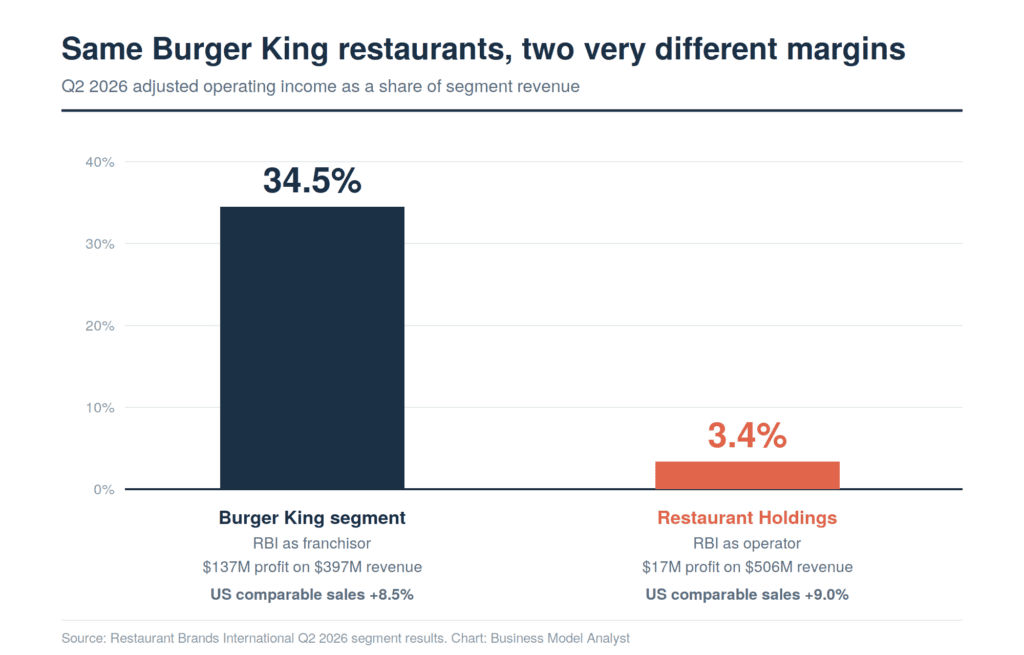
The franchisor books royalties, rent, advertising contributions and technology fees, and it books them on restaurants RBI owns just as it does on restaurants a franchisee owns. Q1 2026 shows the machinery in full because RBI footnotes the intersegment amounts. Restaurant Holdings paid the Burger King segment $28 million in royalties and property expense plus $21 million in advertising and technology fees. That is $49 million in a single quarter, 10.9% of the segment’s $448 million in sales.
Restaurant Holdings posted a $1 million operating loss that quarter. Strip out the $49 million it owed to itself and the same restaurants would have shown $48 million of operating income, a 10.7% margin. The entire operating profit of RBI’s Burger King restaurants, and a little more, went to Burger King.
Read it from the other side. Of the $178 million in franchise and property revenue the Burger King segment collected in Q1, $27 million came from RBI’s own restaurants. That is 15% of the line and 23% of the segment’s $115 million in operating income. RBI eliminates all of it on consolidation, so it never touches reported profit. It shapes how the business looks.
The accounting choice runs deeper. RBI defines organic growth, the metric behind the 8% target and the entire long-term algorithm, to exclude the Restaurant Holdings segment. Royalties from Carrols restaurants flow into the organic number through the franchisor segment. The labor, food and occupancy costs of running those restaurants sit in the segment the metric leaves out.
This is what asset-light means as an accounting posture rather than an operating reality. RBI carries the operating risk on a thousand restaurants right now. Investors are shown a franchisor. Both statements are true, and the gap between them closes only when the refranchising finishes.
McDonald’s runs the mirror image. Its US system is about 95% franchised, it earns roughly 82 cents at the franchisor line against 12 cents as an operator, and its franchisees absorb a check-led squeeze while corporate revenue barely notices. Bloomin’ Brands sits at the opposite pole, owning most of its Outbacks and capturing every dollar of a mix shift. RBI has put itself in the middle on purpose, and only for a while.
The Risk
Start with the remodel money, because it is not moving.
RBI had funded $194 million of the $550 million Royal Reset commitment as of June 30. It funded $152 million by June 2025, $176 million by December, $189 million by March and $194 million by June. That is $5 million deployed in the quarter Burger King posted an 8.5% comp, and $42 million over the full trailing year. With $356 million left and ten quarters to the end of 2028, RBI needs roughly $36 million a quarter, seven times the current pace. At the trailing-twelve-month rate, the commitment finishes around 2034.
Either the physical program is running years behind, or the comp is coming from somewhere other than the buildings. Both readings hurt the official story, which is that Burger King won by investing in the fundamentals.
The unit count says something similar. Burger King’s US and Canada system fell to 7,001 restaurants from 7,062 a year earlier, net restaurant growth of negative 0.9%. Closing weak restaurants pushes their customers to nearby survivors, and comparable sales measure survivors. Some portion of that 8.5% is arithmetic.
The value deals cut the same way. A 2 for $5 bundle buys traffic by lowering the average check, which is fine for a franchisor collecting a percentage of a bigger top line and painful for whoever pays the food and labor cost of the extra transactions. For a thousand restaurants, RBI is that operator. Restaurant Holdings ran a 9.0% comp and grew operating income 3.0%.
Then the guidance. RBI reaffirmed full-year Restaurant Holdings operating income of $10 million to $20 million. The segment lost $1 million in Q1 and earned $17 million in Q2, so the first half already sits at $16 million. RBI is guiding to roughly nothing from those restaurants over the back half of the year, which is what refranchising and start-up costs in China and Brazil produce.
And the portfolio is lopsided. Tim Hortons at 0.1% and Popeyes at negative 5.1% mean Burger King has to keep running near 8% for RBI to hit an 8% profit target. Q2 organic growth of 6.7% came in below it. Leverage sits at 4.1 times with $500 million to $520 million of adjusted interest expense budgeted for the year. The stock fell on an earnings beat because the market read the segment table.
Quick Questions
Did the new Whopper actually cause the 8.5% comp? It contributed. Burger King rolled the upgraded bun, mayo, produce and clamshell box to more than 7,000 US restaurants in February 2026, the first change in about a decade, and Reuters attributed part of the quarter to the 2 for $5 and 3 for $7 value deals. A soft prior-year base of 1.5% and a shrinking unit count also helped. Attributing eight and a half points of comp to a $4,000-a-store input change requires ignoring the other three drivers.
Why does RBI own Burger King restaurants if it is a franchisor? Because its largest franchisee could not remodel fast enough. RBI bought Carrols in 2024, took the restaurants onto its own balance sheet, is spending $500 million of the acquired cash flow to modernize more than 600 of them, and intends to sell nearly all of them to smaller local operators. RBI calls the endpoint sunsetting the Restaurant Holdings segment.
What is the Whopper Guarantee? A service policy Burger King launched in July 2026 after collecting thousands of customer complaints about accuracy and quality. Restaurants remake an unsatisfactory Whopper on the spot and issue a free future Whopper by QR code inside the box. It converts a service failure into a scheduled return visit, and the redemption cost lands on the restaurant P&L.
Is Burger King taking share from McDonald’s? Some. Curtis says he believes so, and the arithmetic supports it: Burger King US beat the burger category by more than nine points, and McDonald’s posted 0.8% with negative guest counts. The category itself is flat to shrinking, so this is share transfer inside a stalled market rather than growth in demand.
What should investors watch next? The pace of refranchising and the price RBI gets per restaurant. That is where the 8.5% comp either converts into cash or does not.
The Business Model Analyst Take
Kobza framed the quarter as proof of what happens “when you invest in the fundamentals and execute well.” The fundamentals he means cost $4,000 per restaurant per year. The investment that made the quarter possible cost $1.5 billion and sits in a segment RBI wants to delete.
Reclaim the Flame is a private equity playbook running inside a public franchisor. Acquire a distressed operator at roughly half a turn of sales. Fund the capital expenditure with the target’s own cash flow. Repair the operating metrics. Exit to smaller buyers at a multiple of the repaired cash flow. Keep the royalty stream. The only unusual feature is that the sponsor and the brand are the same company, which lets RBI charge itself rent and royalties on the way through and report the franchisor half as the real business.
The playbook works if the comp holds after the discounting stops and after RBI sells. It has one soft spot. Selling a restaurant at a price justified by an 8.5% comp built partly on 2 for $5 bundles transfers the hardest problem to the buyer, who inherits both the modern building and the customer trained to wait for a deal. Burger King spent the 2010s in exactly that relationship with its franchisees and needed $1.5 billion to buy its way out.
For anyone studying franchise economics, the lesson is about who holds the risk and when. Franchising does not remove operating risk from the system. It relocates the risk to people with less capital and less patience, and the franchisor discovers the arrangement’s limits at the moment the restaurants need money that nobody in the chain has. RBI took the risk back on purpose, has been carrying it for two years, and is now trying to hand it off at a better price than it paid. The 8.5% is what makes that trade possible. Watch the refranchising number, not the comp.