
Since June 30 the 2-year Treasury yield has risen 5 basis points and the 30-year has risen 37. Policy expectations have not moved. What moved is the price of lending money for a long time, and AI is now the largest new source of long-dated corporate paper in the market.
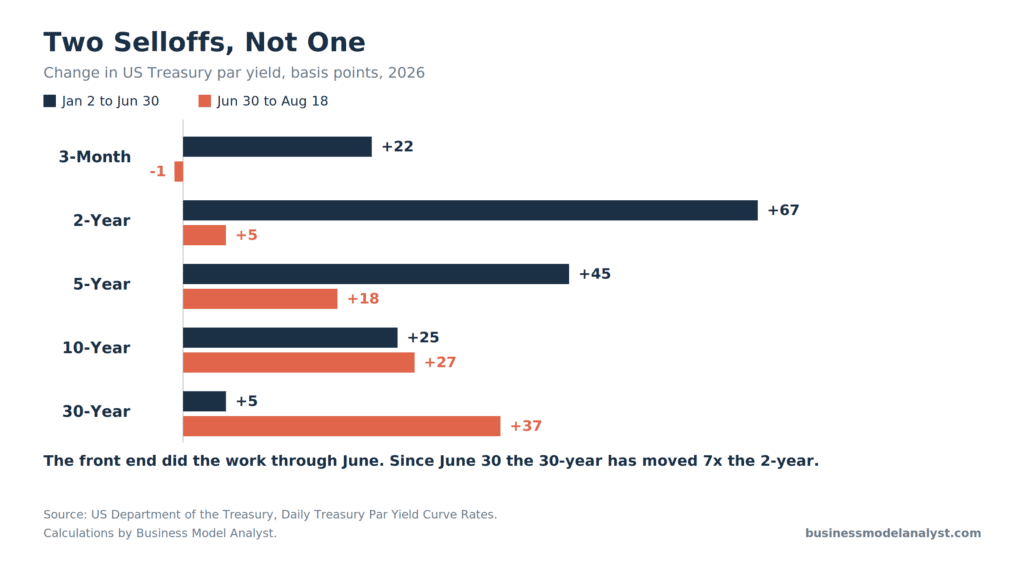
The US Treasury’s own daily yield curve splits 2026 into two selloffs that look nothing alike. Through June 30, the 2-year rose 67 basis points while the 30-year rose 5. Since June 30, the 2-year has risen 5 and the 30-year has risen 37. The front end has gone quiet and the long end has taken over, which means traders are no longer arguing about the Federal Reserve. They are arguing about what compensation a lender deserves for parting with money until 2056. That argument sets the discount rate underneath every company on earth, and the hyperscalers financing the AI buildout have become one of the loudest voices in it.
Emma Tucker’s 10-Point newsletter on Wednesday told subscribers that investors see “echoes of 2007” in the bond market. The comparison is fair on levels. The 30-year Treasury closed at 5.31% on August 17 and touched roughly 5.34% intraday the next day, the highest since 2007, when the peak was 5.44%. But the levels are the least interesting part. Pull the curve apart by maturity and the story that comes out is about who is buying time, who is selling it, and who pays when the price changes.
What Happened
Long-dated government debt sold off across four continents in the same week. The US 30-year hit its highest yield in nearly two decades. French and German 10-year yields reached levels last seen in 2008 and 2011. Japan’s 10-year, which traded at zero within living memory, approached 3% for the first time in three decades. The French 30-year has added close to 50 basis points since the end of June.
The auctions confirmed it. On August 13 the Treasury sold $25 billion of new 30-year bonds at 5.216%, the highest yield at a 30-year auction since 2001. The 10-year auction the day before drew the highest financing cost since 2007. Both cleared in a week when the inflation data improved: a subdued producer price reading, and a July employment report showing US employers cutting jobs rather than adding them.
That combination is the tell. Softer growth and softer inflation should pull yields down if the market is trading Fed policy. Yields rose anyway. The Federal Reserve has held the funds rate at 3.50% to 3.75% through five straight meetings this year, and at the July meeting a handful of members voted to raise rather than cut. Traders have already priced that stalemate, which is why the front end has stopped moving. The 3-month bill yield is one basis point lower than it was on June 30.
The Backstory
Split 2026 at the end of June and the two halves invert.
In the first half, the market repriced the Fed. Inflation stayed above target, the war with Iran pushed oil above $85 a barrel, up roughly 50% since January, and the cuts that traders had penciled in for 2026 came out of the curve one by one. The 2-year absorbed almost all of that: up 67 basis points from January 2 to June 30. The 30-year moved 5. The gap between the two collapsed from 139 basis points to 77, the classic signature of a policy repricing.
Since June 30, the numbers swap places. The 2-year has added 5 basis points, the 30-year has added 37, and the 2s30s gap has widened back to 109. The long end has moved slightly more than seven times the front end over seven weeks. The New York Fed’s ACM model puts the 10-year term premium at 0.80% on August 13, against a June monthly reading of 0.513%. On a daily-versus-monthly basis that comparison is rough, but the direction is unambiguous: roughly the entire 27-basis-point rise in the 10-year since June 30 is compensation for duration, not a changed view of policy.
Something started charging more for time in July. The supply side offers a candidate.
The Plan
Amazon, Alphabet, Meta, Microsoft and Oracle borrowed an average of $28 billion a year between 2020 and 2024, according to BofA Securities. In 2025 they issued $121 billion. Reuters, working from LSEG data, put four of them at roughly $194 billion by July 7 of this year, up 79% on the whole of 2025. Goldman Sachs expects the five to reach about $250 billion in 2026 and $400 billion in 2027. BofA has estimated the big six US banks average around $157 billion a year. Five technology companies now issue more corporate debt than the American banking system.
They are borrowing because the arithmetic leaves no alternative. Microsoft, Meta, Amazon and Alphabet have guided investors to roughly $700 billion of combined capital expenditure in 2026, about double 2025. UBS calculates that hyperscaler capex will consume close to 100% of operating cash flow this year, against a ten-year average of 40%. Alphabet raised its own 2026 guidance three times, landing at $195 billion to $205 billion, and went to the equity market for $80 billion on June 1 rather than lean further on debt.
The paper they sell is long. Data centers, substations and power contracts amortize over decades, so the bonds match, which is how a supply story becomes a duration story. Wall Street desks put AI-related investment-grade supply near $300 billion for 2026 and roughly $360 billion once converted into 10-year duration equivalents. Nvidia sold $25 billion of bonds this year, its first issue in five. SpaceX sold $25 billion days after its record IPO. Barclays forecasts $945 billion of net US corporate supply in 2026, up 30.2% from $726 billion.
BofA economists told clients on Friday that the borrowing is “potentially crowding out long-end Treasury demand,” and estimated that corporate issuance plus heavier mortgage-backed supply added about 0.3 percentage points to 10-year yields this year. Nomura’s Jonathan Cohn has warned that the volume of duration being forced into the long end should worry the Treasury itself, and raised the possibility that the government trims its own long-bond auctions to stay out of the way.
The Business Model Angle
Strip out the macro vocabulary and one number is doing the damage. Every business model has a cost of capital, and the long end of the government curve sets its floor.
The transfer runs in one direction, and it is regressive. Microsoft carries a AAA rating, Alphabet AA+, Meta and Amazon AA-. Post-issuance leverage across the group sits around 0.4 to 0.7 times, against roughly 3 times for the average investment-grade borrower. When these companies flood the market with duration, their own penalty is small: the median spread on their 2-to-4-year paper widened from 30 basis points in 2025 to 40 this year, per LSEG. Ten basis points. Meanwhile the risk-free rate they price against rose 42 basis points on the 30-year over the same year, and 37 since June 30.
So the strongest credits in the index create a supply shock, absorb ten basis points of it, and hand the rest to whoever else needs long money. A mid-market manufacturer refinancing a term loan pays it. A REIT rolling debt pays it. A homebuyer pays it: the Freddie Mac 30-year fixed averaged 6.15% on January 1, bottomed at 5.98% in February, and printed 6.67% on August 13. On a $400,000 loan that is $136 more each month than in January, about $49,000 across the life of the mortgage. Nobody sends that household an invoice. It arrives as “the market.”
Valuation takes the same hit and shows it faster. Take a business modeled with a 9.0% discount rate and 2.5% terminal growth. Its terminal multiple is 15.4 times. Move the discount rate up by the 37 basis points the 30-year has added since June 30 and the multiple falls to 14.6, cutting terminal value 5.4%. Use the full 42-basis-point move for 2026 and the cut is 6.1%. No revenue miss, no margin compression, no competitive threat. Arithmetic.
There is a second pass that has drawn less attention. The buyers being asked to absorb hundreds of billions of long-dated hyperscaler bonds are pension funds and life insurers, and those same balance sheets are already funding the AI buildout privately. Barclays puts private credit at roughly 10% of US life insurer assets and above 15% at private-equity-affiliated insurers such as Athene and Global Atlantic, both of which sit inside the compute-financing platforms Nvidia announced in August. One pool of retirement liabilities is being asked to finance the same data centers twice, once through the public bond market and once through private credit, at two different points in the capital stack. Concentration risk of that shape does not show up in either market’s supply statistics.
The Risk
The attribution is the weak point, and pretending otherwise would be dishonest.
The United States is running a deficit near 6% of output, close to $2 trillion, unprecedented outside a crisis. Bloomberg’s reporting on the AI-issuance theory concedes that fiscal supply, a resilient economy and the inflation shock from the Iran war remain the primary forces behind the long-end selloff. Japanese yields are climbing for reasons that have nothing to do with Nvidia, and rate synchronization drags US yields along. Foreign official demand for Treasuries has stayed subdued. Any of those alone could produce a 37-basis-point move in the 30-year over seven weeks.
The crowding-out mechanism itself is contested. Corporate and government bonds are not perfect substitutes, buyers are not a fixed pool, and the market has absorbed record supply this year at spreads that plenty of managers call attractive entry points rather than distress. The strongest version of the skeptical case: hyperscalers are the highest-quality issuers in the index, demand for their paper has been robust, and treating a AAA borrower as a source of systemic stress confuses supply with credit risk.
Two things survive the objection. First, the decomposition holds regardless of cause. Whatever is driving the long end since June 30, it is not the Fed, because the front end has not moved. Second, the business consequence is identical either way. A CFO refinancing in September does not get a cheaper coupon because the extra duration came from the Treasury rather than from Meta. Attribution matters for policy. It does not matter for the payment.
The reverse risk deserves a mention too. If AI capex disappoints and the issuance calendar thins, the duration pressure eases and long yields fall, which would reprice the same business models upward. Barclays’ Anshul Pradhan has framed the constructive case as requiring a fiscal surprise, slower AI-related issuance, a change in Treasury’s issuance mix, and a run of soft data. He noted that his desk has “been arguing against fading the long end sell-off.” That is four conditions, and none of them has arrived.
Quick Questions
Is this a Federal Reserve story? Not since June. The 2-year yield has moved 5 basis points since June 30 and the 3-month bill has moved minus 1. Traders settled their view on policy in the first half of 2026, when the 2-year added 67 basis points and the 30-year added 5.
How much of the long-end move comes from AI borrowing? Nobody can separate it cleanly. BofA estimates that corporate issuance plus mortgage-backed supply added roughly 0.3 percentage points to the 10-year this year, without isolating AI within that. Deficits, inflation and Japanese yields carry most of the rest.
Why does long-dated issuance matter more than the dollar amount? Bond investors clear duration risk, not face value. A 40-year data-center bond consumes far more of a portfolio’s duration budget than a 3-year note of the same size, so where the paper sits on the curve matters as much as how much of it there is.
What does a 40-basis-point move actually cost a business? On a discounted cash flow with 2.5% terminal growth, raising the discount rate 42 basis points cuts terminal value about 6%. On a $400,000 mortgage, the move from January’s rate to August’s adds $136 a month.
Are hyperscaler bonds risky? Their credit ratings say no. Microsoft is AAA, Alphabet AA+, Meta and Amazon AA-, with leverage near 0.5 times against an investment-grade average around 3. Oracle is the exception at BBB, two notches above junk, and its credit default swap cost has more than tripled since September 2025.
The Business Model Analyst Take
The AI buildout spent three years as an equity story. Investors argued about capex ratios, depreciation schedules and whether Alphabet’s backlog justified its spending. That argument stayed inside the technology sector, and companies outside it could watch without paying.
Financing it through the bond market changed the audience. When five firms issue more paper than the US banking system, and issue it at the long end because their assets are long, they enter the same order book as every sovereign and every corporate borrower on the planet. The Treasury curve shows the handoff: policy repricing through June, duration repricing since. The 30-year moved seven times the 2-year in seven weeks, in a stretch when inflation cooled and employers cut jobs.
Whether AI issuance caused most of that move or merely a slice of it, the direction of the transfer is clear. The borrowers with the strongest balance sheets pay 10 basis points of extra spread. The borrowers who never issued a bond pay the rest, through mortgage rates, refinancing costs and a discount rate that trims their terminal value without touching their income statement. Nvidia’s compute-financing platforms and Meta’s Hyperion structure were built to move AI’s capital costs off the sponsors’ balance sheets. The long end of the Treasury curve is where a good deal of it landed.
If you run a business that competes for capital, the practical move is to stop treating AI as someone else’s capex cycle. Price your next refinancing off the 30-year rather than the fed funds path. Reconsider projects whose returns clear a 9% hurdle but not a 9.5% one. Watch Treasury’s quarterly refunding announcements as closely as the FOMC calendar, because the mix of long-dated issuance now tells you more about your cost of capital than the dot plot does. The Fed sets the price of money for the next two years. Something else is setting it for the next thirty.