
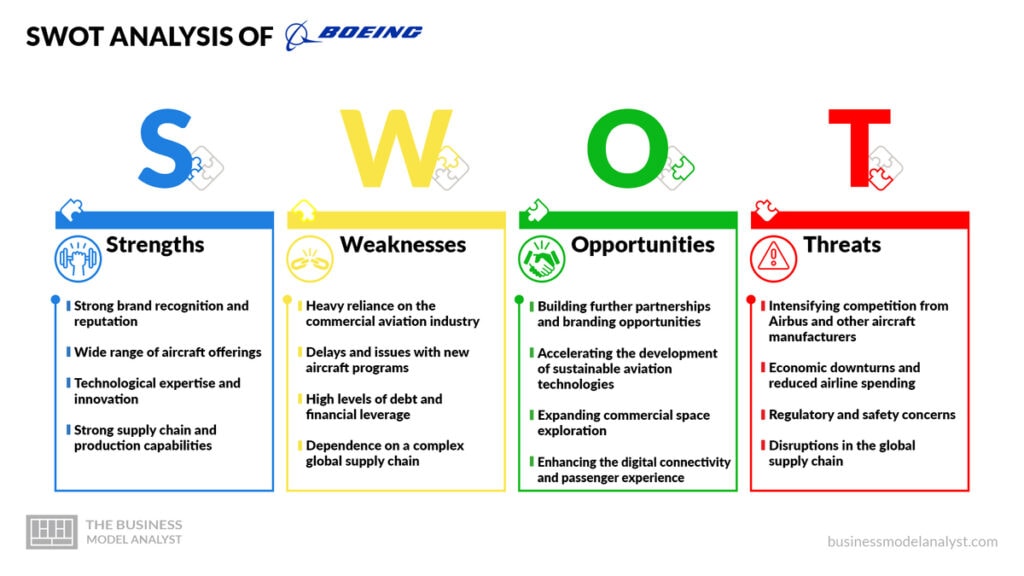

Boeing spent most of the last six years as a cautionary tale. In 2025, for the first time since 2018, it turned an annual profit. That single fact reframes every strength and weakness in this analysis: Boeing is no longer a company in freefall, but it is not yet a company that has fully recovered either. It sits in the awkward middle, rebuilding scale faster than it is rebuilding durable profitability.
This Boeing SWOT analysis breaks down where the company actually stands in 2026, using verified financials and delivery data rather than the reputation it carried into the crisis. Whether you are weighing the stock, studying a duopoly under stress, or benchmarking a turnaround, the goal here is the same: separate the real recovery from the accounting gains that flatter it.
What is a SWOT analysis? A SWOT analysis is a strategic framework that maps a company’s internal Strengths and Weaknesses against its external Opportunities and Threats. Strengths and weaknesses are things the company controls, such as its balance sheet, product portfolio, and manufacturing quality. Opportunities and threats come from outside, such as market demand, regulation, and competition. For Boeing, the framework is especially useful because its internal quality problems and its external market position have been pulling in opposite directions.
Boeing at a Glance
| Attribute | Detail |
|---|---|
| Founded | 1916, Seattle, Washington |
| Headquarters | Arlington, Virginia |
| CEO | Kelly Ortberg (since August 2024) |
| Employees | ~172,000 |
| Business segments | Commercial Airplanes; Defense, Space & Security; Global Services |
| FY2025 revenue | $89.5 billion (up 34% year over year) |
| FY2025 net income | $2.24 billion (first annual profit since 2018) |
| Total backlog | $682 billion (record high) |
| Main rival | Airbus |
For a deeper look at how the company earns and spends, see our Boeing business model breakdown.
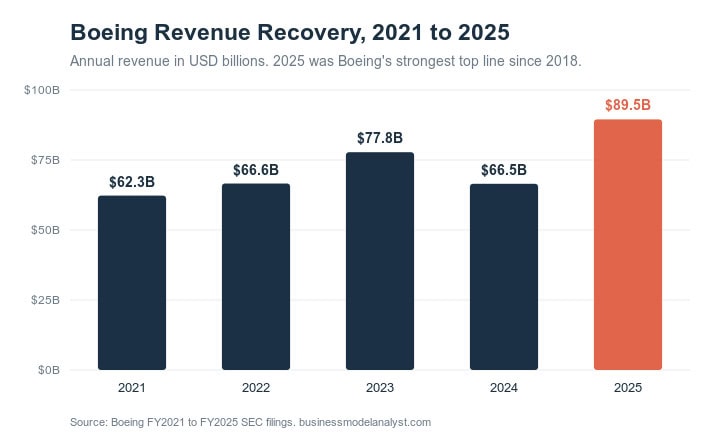
The revenue line tells the recovery story cleanly. The profit line is where you have to read the footnotes. Boeing’s $2.24 billion 2025 net profit was heavily lifted by a $9.6 billion gain from selling most of its Digital Aviation Solutions business to Thoma Bravo. Strip that out, and the operating picture is still repairing. Keep that tension in mind through the rest of this analysis.
Boeing Strengths
Boeing’s strengths are structural and hard to replicate. In a global commercial aircraft market that is effectively a duopoly, being one of only two players who can build large jets at scale is a moat that regulation and capital requirements protect. The turnaround under Ortberg has added a second layer: operational credibility that had been badly damaged is being slowly rebuilt.
| Strength | Why it matters |
|---|---|
| Duopoly position | Boeing and Airbus split the large commercial jet market with almost no viable third entrant, giving Boeing durable pricing power and scale |
| Record backlog | $682 billion in orders, including more than 5,900 commercial airplanes, locks in years of demand |
| Order momentum | Boeing booked ~1,173 net orders in 2025, beating Airbus for the first time since 2018 |
| Defense franchise | A ~$85 billion defense backlog plus the F-47 next-generation fighter win diversifies away from commercial cycles |
| Vertical reintegration | The December 2025 Spirit AeroSystems reacquisition pulls fuselage production back in house for quality control |
| Regulatory trust returning | The FAA lifted the 737 MAX production cap and cleared Boeing to raise output through 2026 |
The order book is the single strongest signal that Boeing’s problem was never demand. Airlines kept buying through the crisis. In 2025, Boeing pulled in roughly 1,173 net orders against Airbus’s 889, ending a seven-year stretch of Airbus order dominance. The 737 MAX drove that surge, accounting for 591 orders on its own. Alaska Airlines alone placed its largest-ever order in December for 105 of the stretched 737-10 variant.
The production recovery is the other pillar. After the January 2024 Alaska Airlines door-plug blowout, the FAA capped 737 MAX output at 38 jets a month. That cap defined Boeing’s constrained cash flow for nearly two years, because airlines pay the bulk of an aircraft’s price on delivery. The cap is now gone.
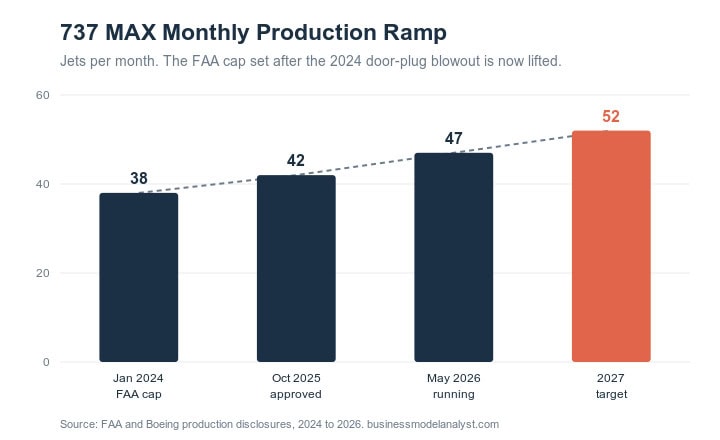
By May 2026, Boeing had passed the FAA’s capstone review to run the line at 47 jets a month, with a fourth assembly line opening at Everett, Washington, on July 6, 2026, to push toward 52. Ortberg’s framing has been disciplined: “Quality is the rate.” He has repeatedly said Boeing will not build faster than its suppliers can build cleanly, which is exactly the message the market needed after years of the opposite. Our coverage of the new Everett 737 MAX line digs into why Boeing is photocopying its Renton system rather than reinventing it.
The Spirit AeroSystems reacquisition, closed in December 2025 for $4.7 billion in equity, is a strategic strength disguised as an expense. Spirit built the very 737 fuselages at the center of Boeing’s quality failures. Bringing it back in house trades short-term integration cost and debt for long-term control over the part of the supply chain that has hurt Boeing most.
Boeing Weaknesses
The weaknesses are where the “recovery” label gets tested. Boeing’s balance sheet, its cash generation, and its commercial margins all still carry the scars of the crisis years, and none of them heal on the same timeline as the order book.
| Weakness | The problem |
|---|---|
| Commercial still loss-making | Boeing Commercial Airplanes posted a ~$7.1 billion operating loss in 2025 despite record deliveries |
| Negative free cash flow | Free cash flow was still ~($1.9 billion) in 2025, even as operating cash flow turned positive |
| High, sticky debt | Debt sat at ~$54.1 billion at the end of 2025, essentially flat versus 2024, with ~$15.5 billion due within three years |
| Profit quality | The 2025 net profit leaned on a $9.6 billion one-time asset-sale gain, not core operations |
| Backlog conversion lag | Only ~13% of the record backlog is expected to convert to revenue through 2026 |
| Concentrated program risk | The 737 MAX drove 447 of 600 deliveries in 2025, so any MAX stumble hits the whole company |
Here is the uncomfortable core: Boeing delivered more airplanes in 2025 than in any year since 2018 and its commercial division still lost about $7.1 billion. Volume is recovering ahead of profitability because Boeing is working through inventory, absorbing Spirit integration costs, and paying for years of production inefficiency. A record top line that still produces a segment loss is the clearest evidence that the turnaround is real but incomplete.
The debt load compounds the pressure. At roughly $54.1 billion, Boeing’s debt barely moved in 2025, and it leaves the company with far less flexibility than it had before the crisis. Every dollar of ramp-up spending, Spirit integration, and defense charge competes with debt service. This is why the backlog, impressive as it is, does not translate into near-term relief: Boeing itself expects only about 13% of that $682 billion to become revenue by the end of 2026.
There is also a concentration problem hiding inside the recovery. The 737 MAX is carrying Boeing. It drove the order surge and the delivery rebound, which means Boeing’s fortunes are tied more tightly than ever to a single aircraft family that has already caused two fatal crashes and a two-year production cap. Diversification of the delivery base remains thin.
Boeing Opportunities
Boeing’s opportunities are less about finding new markets and more about executing on demand it already has, plus leaning harder into the defense and services segments that are less exposed to commercial aviation’s boom-bust cycle.
| Opportunity | The upside |
|---|---|
| Production ramp to 52+ | Every incremental jet per month converts existing backlog into cash; the target is 52 MAX monthly in 2027 |
| 777X entry into service | First 777-9 delivery is anticipated in 2026, refreshing the widebody lineup against the A350 |
| 737 MAX 10 certification | FAA certification of the largest MAX variant would unlock a large deferred order book |
| Defense and space expansion | The F-47 fighter program and a ~$85 billion defense backlog offer counter-cyclical growth |
| Services and aftermarket | Global Services carries high margins and recurring revenue, strengthened by Spirit’s aftermarket assets |
| Widebody demand recovery | Long-haul travel recovery is lifting 787 and 777 orders after years of narrowbody dominance |
The cleanest opportunity is simply the ramp itself. Boeing does not need to invent demand; it needs to build what it has already sold. Moving from 47 to 52 MAX jets a month, plus lifting 787 output from eight to ten monthly, is a direct line from backlog to cash flow. If Ortberg’s disciplined approach holds and suppliers keep pace, this is the mechanism that finally makes Commercial Airplanes profitable again.
The widebody refresh matters more than it gets credit for. The 777X has been delayed for years, but first delivery of the 777-9 is now expected in 2026, and certification of the 737 MAX 10 would release orders that airlines have been holding. Both are latent demand waiting on regulatory sign-off rather than market creation.
Defense is the quiet diversifier. Winning the F-47 next-generation fighter, the sixth-generation successor to the F-22, gives Boeing a decades-long program anchor that does not move with airline capital cycles. For a company burned by commercial concentration, a larger defense mix is a strategic hedge, even though defense has its own fixed-price execution risks. Our top aerospace companies rundown shows how the defense majors stack up.
Boeing Threats
The threats are external and largely outside Boeing’s control, which is what makes them dangerous. A company mid-turnaround has less cushion to absorb a shock, and Boeing’s cushion is thin.
| Threat | The risk |
|---|---|
| Airbus delivery lead | Airbus delivered 793 aircraft in 2025 versus Boeing’s 600, and holds a larger backlog |
| Safety and regulatory scrutiny | Any new quality incident could trigger fresh FAA caps and reset the recovery |
| Supply chain fragility | The ramp depends on suppliers matching pace; a single bottleneck stalls the whole line |
| Emerging competition | China’s COMAC is building domestic scale that could erode Boeing’s long-term China demand |
| Geopolitics and tariffs | Trade tension, especially with China, can freeze orders and disrupt the global supply chain |
| Fixed-price defense losses | Several defense programs continue to book charges under fixed-price contracts |
The competitive threat is real but nuanced. Airbus won 2025 on deliveries by a wide margin, 793 to 600, and enters 2026 with a backlog near 8,700 aircraft. Boeing won on orders. That split defines the current state of the duopoly: Airbus is converting demand into aircraft faster, while Boeing is winning future demand it has not yet proven it can build at rate.

The safety threat is the one that could unwind everything. Boeing’s entire recovery rests on regained regulatory trust. The FAA lifted the production cap because Boeing demonstrated improvement, and a single serious quality failure could reverse that in a week. This is why Ortberg’s “quality is the rate” discipline is not just messaging; it is risk management for a company that cannot afford another 2024.
Longer term, the competitive map is widening. China’s COMAC is slowly building a domestic narrowbody alternative, and while it is years from challenging the duopoly globally, it threatens the China market that has historically been a major Boeing growth engine. Combined with recurring US-China trade friction, Boeing’s largest long-term growth market is also its most politically exposed. For the full competitive picture, see our Boeing competitors analysis, and for the macro forces at play, the Boeing PESTLE analysis.

Boeing SWOT Analysis Summary
| Helpful | Harmful | |
|---|---|---|
| Internal | Strengths: Duopoly position, record $682B backlog, order leadership over Airbus, F-47 defense win, Spirit vertical reintegration, restored FAA trust | Weaknesses: ~$7.1B commercial operating loss, negative free cash flow, ~$54B debt, profit reliant on one-time gains, MAX concentration |
| External | Opportunities: Production ramp to 52+/month, 777X entry, MAX 10 certification, defense and services growth, widebody recovery | Threats: Airbus delivery lead, safety and regulatory risk, supply chain fragility, COMAC and geopolitics, fixed-price defense charges |
The Business Model Analyst Take
Boeing in 2026 is a genuine turnaround that is being oversold by its own headline numbers. The recovery is real: order leadership over Airbus for the first time in seven years, a record backlog, a lifted production cap, and a CEO who says the right things about quality and appears to mean them. Those are not cosmetic wins. They are the foundation of a durable comeback.
But the profit that grabbed the headlines was manufactured largely by an asset sale, and the division that actually builds airplanes still lost billions. That gap between the reported profit and the operating reality is the whole story. Boeing has proven it can win demand and rebuild trust. It has not yet proven it can build aircraft at rate, at quality, and at a margin that stands on its own.
The single number to watch is not revenue or backlog. It is Boeing Commercial Airplanes operating margin. When that turns durably positive without an accounting assist, the turnaround is complete. Until then, Boeing is a recovering company with a strong hand and a thin cushion, and the market that made it, safety and regulatory trust, remains the same market that can break it. The order book gives Boeing time. Execution decides whether it uses it.


