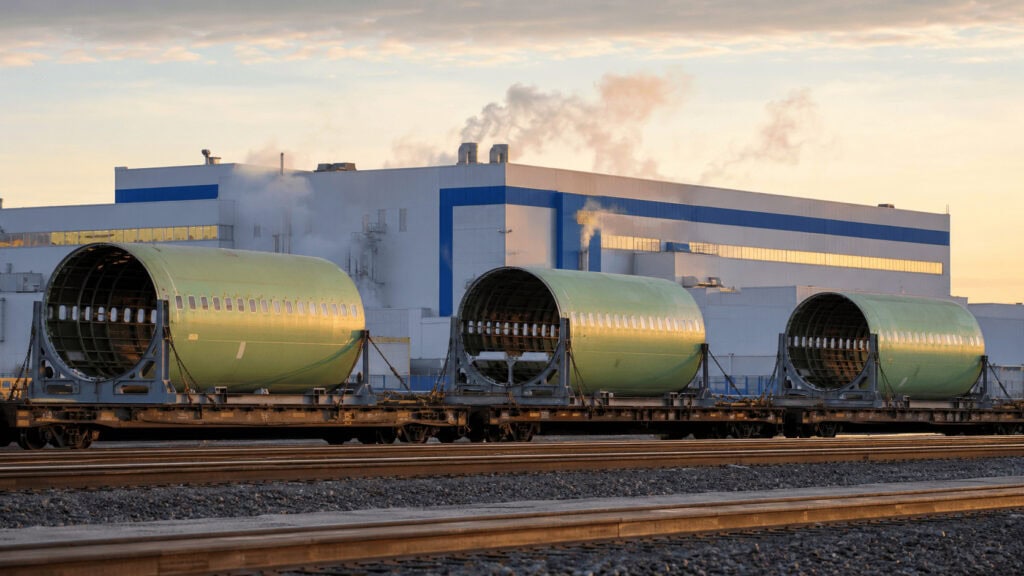

The fuselage supplier arrived with negative net assets and $1.5 billion of below-market contracts. Boeing helped write the terms that made them below market, starting in 2005.
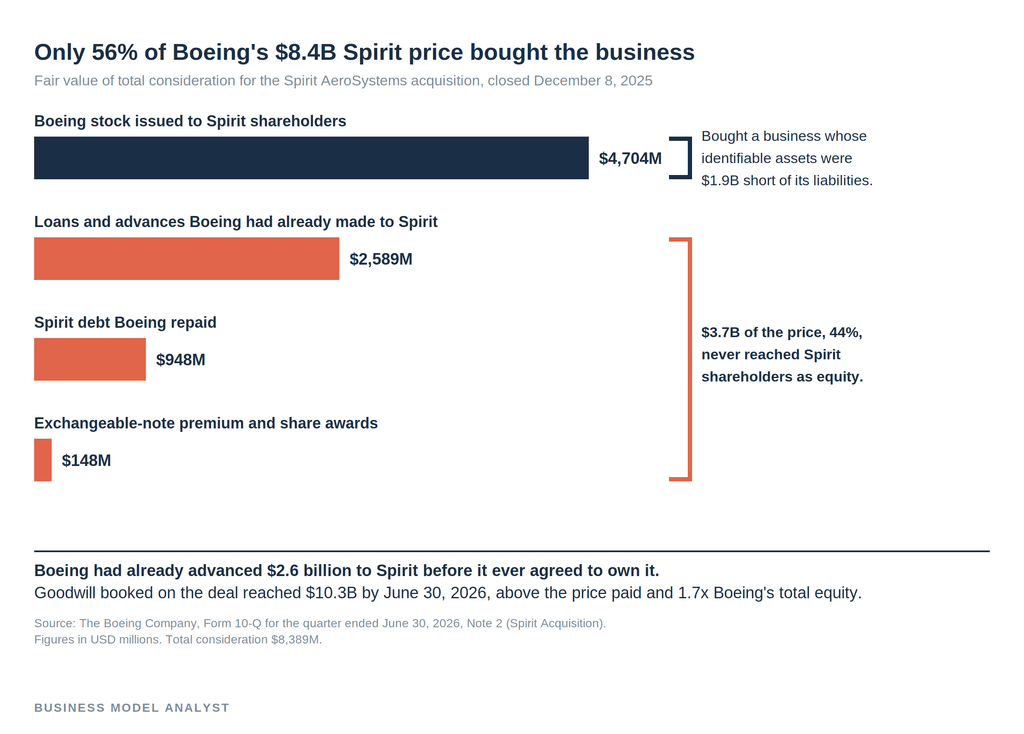
Boeing closed its $8.389 billion purchase of Spirit AeroSystems on December 8, 2025. Six months later its own filings show the acquired assets were worth $1.9 billion less than the acquired liabilities, which pushed goodwill on the deal to $10.278 billion. That is more than the price paid and roughly 1.7 times Boeing’s entire equity. The single largest driver of the change is $1.52 billion of customer contracts priced below what a market participant would have accepted.
Buying a supplier is supposed to be the boring, defensible move. You control the tooling, you control the quality, you stop paying someone else’s margin.
Boeing did that in December, and the numbers coming out the other side describe something less tidy: a company that spent $8.4 billion to take back a factory it sold for about $900 million in 2005, and then spent the following six months finding more liabilities inside it.
The interesting part is not that the deal is expensive. It is where the expense came from.
What Happened
Boeing reported a pretax loss of $339 million for the first half of 2026 on revenue of $46.8 billion, with Commercial Airplanes losing $885 million at the segment line. That is the number on the income statement.
The number that is not on the income statement sits in Note 2 of the June 30 quarterly filing. When the deal closed, Boeing provisionally assigned $9.997 billion of the purchase price to goodwill. By March 31 that figure had climbed to $10.360 billion. By June 30 it settled at $10.278 billion.
Goodwill above the purchase price only happens in one situation: the identifiable liabilities you took on exceed the identifiable assets you got. At closing that gap was $1.6 billion. By midyear it was $1.9 billion.
The main mover was accrued liabilities, which rose from $1.784 billion to $2.202 billion in the allocation. Inside that sits $1.52 billion for off market customer contracts, measured as the present value of the amount by which contract terms deviated from what a market buyer could have obtained. Jonathan Weil at the Wall Street Journal flagged the footnote on September 3.
Because Boeing found the money within twelve months of closing, accounting rules let it park the deterioration on the balance sheet as extra goodwill instead of running it through earnings.
The Backstory
In February 2005, Boeing agreed to sell its Wichita, Tulsa and McAlester operations to the private equity firm Onex. Boeing’s own 8-K described what it was getting: about $900 million in cash, the transfer of certain liabilities, and long term supply agreements that would provide Boeing ongoing cost savings.
Read that last item again. Boeing took part of its payment in the form of cheap parts, forever.
The prospectus Spirit filed when it went public spelled out the mechanics. Spirit became the exclusive supplier for substantially all the products the Wichita division had previously made in house, with pricing on in production models contractually set for years and average prices stepping down as volumes rose. Onex turned roughly $375 million of equity into about $3.2 billion by the time it exited in 2014.
That structure worked for about fifteen years. Then the 737 MAX was grounded, volumes collapsed, and a business built on volume linked price step downs discovered what happens when the volume stops. Spirit lost $2.14 billion in 2024 on $6.32 billion of revenue and finished the year with negative $2.62 billion of equity. Roughly 58% of its revenue came from one customer, on sole source terms, for parts that customer could not buy anywhere else.
At that point the supplier was no longer a supplier. It was a hostage situation with two hostages.
The Plan
Boeing’s stated plan is straightforward and probably correct: bring fuselage production back under one roof, one quality system, one set of incentives. Around 15,000 Spirit employees joined Boeing, Airbus took the Airbus facing work with $439 million of compensation for the trouble, and the FTC cleared the deal with divestitures on the theory that Boeing and Airbus together deliver about 95% of large commercial aircraft.
Boeing says the integration is progressing and calls it central to raising production rates. Nothing in the filings contradicts that operationally.
The financial plan is harder to see. The off market contract liability does not disappear; it amortizes into revenue over time. Boeing disclosed the schedule: $64 million in year one, then $154 million, $162 million, $150 million and $146 million. That is $676 million over five years against a $1.52 billion balance.
Which means fewer than half of those contracts unwind by 2030. The rest is a drag stretching into the 2030s. This is not a one quarter cleanup item. It is a decade long amortization of a pricing decision made in the George W. Bush administration.
The Business Model Angle
A below market supply contract is a loan, not a saving. Boeing booked the savings for two decades. The principal came due in one payment of $8.4 billion, plus a $1.52 billion liability recognized on the way in. Squeezing a sole source supplier does not remove cost from a system. It relocates cost to the balance sheet of the party least able to carry it, and eventually you inherit that balance sheet.
Sole source plus financial distress equals the whole surplus. Once 58% of a supplier’s revenue comes from you and none of its output can be sourced elsewhere, the negotiation is over. The Boeing business model depends on a fuselage arriving in Renton. Spirit knew it, and priced accordingly.
Watch the consideration stack, not the headline price. Only $4.704 billion of the $8.389 billion went to Spirit shareholders as stock. Another $2.589 billion settled loans and advances Boeing had already pushed into Spirit to keep it running, and $948 million repaid Spirit debt. Boeing was already funding this company. The acquisition converted an informal subsidy into a formal one.
Asset light has a settlement date. The 2005 sale was a capital efficiency trade: less fixed asset, more return on the assets remaining. It worked on the metric it was measured against. Twenty one years later Boeing’s total goodwill of $17.6 billion is 2.9 times its $6.1 billion of equity, and $10.3 billion of that goodwill is the accounting record of undoing the trade.
The Risk
The measurement window closes on December 8, 2026. After that, any further bad news about what Boeing bought lands on the income statement instead of the balance sheet. Boeing has already used two quarters of that window to raise the estimate twice, in both directions, which suggests management is still working out what it owns.
There is a second tell in the same filing. Boeing’s Military Aircraft reporting unit carries $1.295 billion of goodwill against a negative carrying value at June 30. The company ran its annual impairment test in April using a qualitative assessment and concluded fair values comfortably exceeded carrying values. That conclusion is now supporting $17.6 billion of goodwill on a balance sheet with $6.1 billion of equity and $9.75 billion of valuation allowances sitting against deferred tax assets.
Meanwhile 737 deferred production costs rose to $13.1 billion from $11.8 billion in six months. The Boeing SWOT analysis picture has not changed much: strong order book, structurally difficult conversion of that book into cash.
The airlines are living inside the consequence. Constrained deliveries from Boeing and Airbus are one of the reasons fares have stayed high after the fuel shock, because nobody can add capacity fast enough to compete the price back down.
Quick Questions
Did Boeing overpay? By the arithmetic in the filing, it paid $8.389 billion for a business with negative $1.889 billion of identifiable net assets. Whether that is overpaying depends on whether you think Boeing had a choice.
Why does goodwill exceed the purchase price? Goodwill is the plug between what you paid and the fair value of what you identified. When identified liabilities exceed identified assets, the plug is bigger than the price. It is unusual and it is a signal.
Does this hit earnings? Not yet. Adjustments made within one year of closing go to goodwill. After December 8, 2026, they go to the income statement.
What is an off market contract? A contract priced away from what an arm’s length buyer would have accepted. Here it is worth $1.52 billion, and it amortizes into revenue over more than a decade.
The Business Model Analyst Take
Boeing did not buy a supplier. It repurchased a decision.
The 2005 sale was priced as a win because the savings were visible and the liability was not. The 2025 purchase is priced as a strategic reintegration because the operations are visible and the contract book is not. Same trade, opposite direction, and the honest number is the one in the footnote: $10.3 billion of goodwill on an $8.4 billion deal, sitting on top of $6.1 billion of equity.
Outsourcing did not make the cost of building a fuselage go away. It made it someone else’s problem for twenty one years, at interest.