
Retail pay-later ran on merchant fees. A landlord will not pay one, so the entire charge lands on the tenant. Run Flex’s published fee stack on a typical apartment and the timing help costs 114% a year.
Buy-now-pay-later was never free. Someone paid, and for a decade that someone was the store. Merchants handed BNPL lenders 5% to 8% of the ticket to close a sale, which bought consumers the 0% APR that made the category politically safe. Rent, electricity and tax bills carry no merchant. Nobody pays a discount fee to receive money they are already owed. So the finance charge moves to the only party left, and the product turns into consumer lending wearing a payments interface.
What Happened
Stacy Cowley reported in The New York Times on 17 August that pay-later lenders now finance household basics. Flex and Zip fund broadband, electricity, health insurance, phone service, mortgage and water bills. Affirm has started advancing some tenants a few extra weeks on rent. Dentists, veterinarians and medical clinics offer instant pay-later financing at the chair, and Intuit began promoting “File Now, Pay Later” loans to TurboTax users who owe money on their return.
Karen Webster of Pymnts called the loans working capital for the modern middle class. Lauren Saunders of the National Consumer Law Center gave the counterweight: the loans answer a real cash shortfall, then leave the borrower short again the following week with fees attached.
The scale numbers in the coverage came from two different Federal Reserve papers, and they do not agree.
The Backstory
Four Fed Board economists published a FEDS Note on 5 June 2026 measuring the whole US BNPL credit book. Acree, Barnes, Bruce and Hannon put 2025 issuance at $156.7 billion across the six largest lenders. Pay-in-4 accounted for $78.3 billion, half the total. The other half, $78.4 billion, came from short and longer-term installment loans. Interest-bearing product totalled $58 billion, and 74% of it sits in that second half.
They also tracked the payer. The 0% APR share of BNPL issuance peaked at 83% in 2020 and 2021. By 2025 it had fallen to 63%. Twenty points of the market moved from merchant-funded to borrower-funded in five years, before rent and utilities entered the mix.
Zhu Wang at the Richmond Fed published the systemic-risk read in February 2026, the one The Times cited for the verdict that the threat is limited. Wang built that estimate by extrapolating the CFPB’s pay-in-4 origination series and arrived at roughly $70 billion.
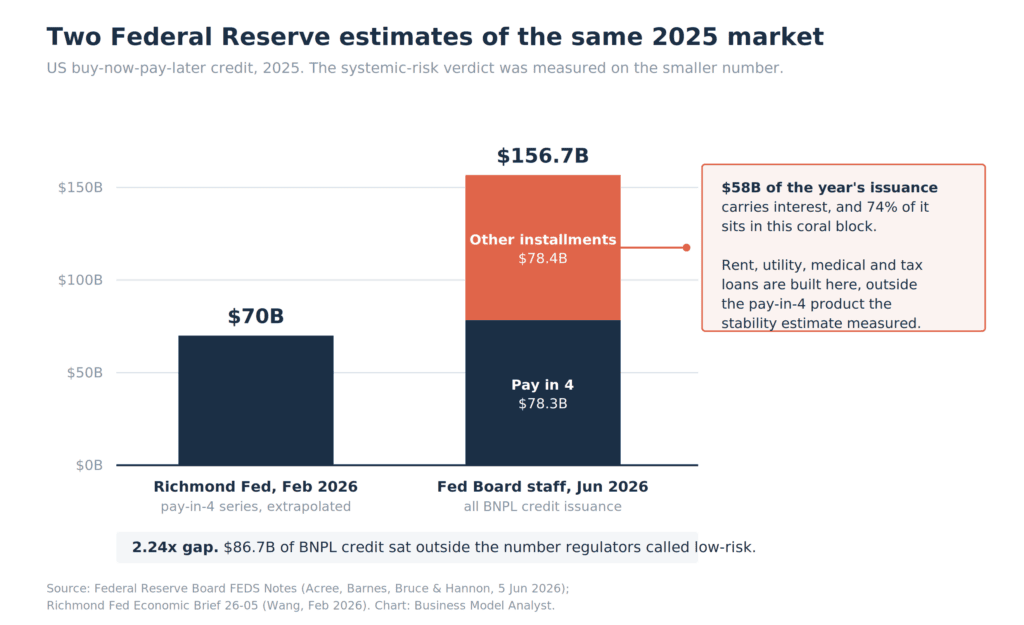
The two papers measure different things, and the difference decides the conclusion. Wang’s $70 billion covers the pay-in-4 product line. The Board’s $156.7 billion covers everything. That leaves $86.7 billion of BNPL credit outside the number regulators called low-risk, and the excluded pile is where the interest lives. Rent, utility, medical and tax loans are built there, not in pay-in-4.
The Plan
Flex, founded in 2019 in New York, has financed close to $40 billion of rent for three million tenants. Its customers carry a median credit score under 600. About a third split rent every month; the rest dip in occasionally. This year the company extended the same machinery to utilities and auto loans.
Ryan Metcalf, Flex’s vice president of public affairs, framed it plainly in The Times: the company cannot solve income or the price of rent, only a timing problem, and he called that harm reduction. Affirm’s John Pitts described its rent pilot as one loan at a time, aimed at gig workers and others with lumpy income, with no second advance until the first clears.
Both companies point to the same defence. Flex charges no late fees and no compounding interest. Affirm caps its APRs at 36% and discloses cost up front. Neither claim is false. Both sidestep the question of who now writes the cheque.
The Business Model Angle
Price the timing. Flex publishes three fees: a $5.99 monthly membership, a processing fee of 0.5% of total rent, and a split fee of up to 3% of the amount borrowed on the second payment, which can run to half the rent.
Zillow put the typical US multifamily asking rent at $1,789 in June 2026. Split that down the middle and Flex advances $894.50.
| Line item | Cost |
|---|---|
| Monthly membership | $5.99 |
| Processing fee, 0.5% of $1,789 | $8.95 |
| Split fee, 3% of $894.50 borrowed | $26.83 |
| Total for one month | $41.77 |
| Cost as a share of the sum advanced | 4.67% |
| Annualised at a 15-day second payment | 113.6% |
| Annualised at a 30-day second payment | 56.8% |
Strip out the membership and processing fees and take the friendliest possible reading, split fee alone across a full 30 days, and the answer is 36.5%. Federal law caps the all-in rate on consumer credit to active-duty servicemembers at 36%, and that calculation counts participation fees. The most generous version of Flex’s headline fee lands on the ceiling. The realistic version lands at triple it.
Now set that beside the merchant-funded model it replaced. Affirm’s 10-Q for the nine months to 31 March 2026 shows $847.6 million of merchant network revenue on $36.1 billion of GMV.
| Take rate | Who pays | Rate | On what |
|---|---|---|---|
| Affirm merchant network revenue | The retailer | 2.35% of GMV | An installment loan running months |
| Flex all-in rent fee | The tenant | 2.33% of rent | Half the money for about 15 days |
Identical price. Opposite payer. Flex collects the same 2.3-odd percent that a retailer pays Affirm, except the tenant pays it, and pays it again in September, and again in October.
A renter who splits every month spends $501.24 a year. That is 28% of one month’s rent, handed over for a service that never reduces the balance by a dollar.
The shift is already visible inside Affirm, where merchants still exist. Interest income over those nine months hit $1.48 billion against $847.6 million of merchant network revenue, a ratio of 1.75 to one. Merchant fees supply 27.4% of revenue, and merchant plus card network together reach 34.1%. At the largest US pay-later lender, on retail, the borrower already funds roughly two-thirds of the business. Move the product to a landlord or a utility and the merchant line goes to zero. For a fuller map of where these revenue lines come from, see how fintechs make money, and for the original merchant-funded design, the Affirm business model and the Klarna business model.
The Risk
The industry’s steelman is stronger than the coverage allows, and it deserves a hearing.
Start with the alternative. Landlords commonly charge 5% of rent as a late fee, roughly $89 on that $1,789 apartment. Flex costs $41.77. For a tenant who is short on the first and flush on the fifteenth, Flex is the cheaper option by half, and it beats an eviction filing by an order of magnitude. Metcalf’s harm-reduction line survives contact with the arithmetic on any single month.
Credit performance may also run better here than in retail. A borrower who loses their job stops paying for the sweater long before they stop paying for electricity. Essentials sit at the top of the household payment queue, which should hold loss rates down. Flex blocks a second advance until the first clears, and Affirm advances one rent loan at a time, so neither lender lets a borrower stack against itself.
Three things cut the other way.
Stacking across lenders stays invisible. A quarter of BNPL users surveyed by LendingTree have carried three or more loans at once, and most pay-later lenders still do not report to the credit bureaus. FICO announced Score 10 BNPL and Score 10 T BNPL on 23 June 2025 for a Fall 2025 release. A year on, The Times reports no release date, because FICO is waiting for lender data to arrive at scale. Every lender underwrites as though it were the only one in the borrower’s wallet.
The regulatory shape has drifted from the products. The CFPB withdrew its 2024 BNPL interpretive rule on 12 May 2025 and said in June 2025 it would not reissue, reasoning that open-end credit-card rules fit poorly because BNPL loans are generally closed-end. Flex does not sell a closed-end loan. It extends a revolving line of credit with a monthly membership fee, which is the open-end shape the Bureau described as absent from the category.
Then there is the collection mechanic. These loans pull from a bank account or debit card on a set date. One mistimed withdrawal on a household with no buffer triggers overdraft fees and knocks over the next payment in the queue, which is the failure mode that turns a $41.77 convenience into a bad month. Households leaning on debt for daily costs are the same ones now pulling home equity to clear credit card balances.
Quick Questions
Is buy-now-pay-later for rent a loan? Yes. Flex operates as a financial technology company, not a bank, with loans and lines of credit issued by Lead Bank or Column N.A. The tenant borrows and repays with fees.
Why can’t the landlord pay the fee like a retailer does? A retailer pays BNPL fees to win a sale it might otherwise lose. A landlord already holds a signed lease and a legal claim on the rent. The fee buys no incremental revenue, so nobody offers it.
Is $156.7 billion large enough to matter? Against roughly $3 trillion of annual US credit card spending, no. The concern is composition and visibility, not size. Growth runs at double digits, and most of the book stays off credit reports.
Does splitting rent help a credit score? Flex reports positive rent payment history to credit bureaus when a user enables it. Building a file through a product costing 28% of a month’s rent each year is an expensive way to buy a score.
What changes if FICO ships the BNPL scores? Lenders would see stacked loans they cannot see today, which should tighten approvals for the heaviest users. That is the cohort using pay-later for electricity.
The Business Model Analyst Take
Watch the payer, not the product. Nothing about the mechanics of splitting a payment changed when BNPL walked from checkout into the utility bill. The revenue model inverted. A merchant-subsidised marketing tool became a borrower-funded finance charge, and the same 2.3% take rate that a retailer treated as customer acquisition cost now arrives as a monthly line in a household budget that was short to begin with.
The regulatory read has not caught up because the two Federal Reserve papers in circulation measure different halves of the market, and the reassuring one measures the half where merchants still pay. When you next see a category declared low-risk, check what the estimate counted. Wang’s $70 billion is honest work on pay-in-4. It just does not contain the rent.
The transferable lesson for anyone building a payments or lending product: your 0% APR is somebody’s line item. Trace which counterparty funds it and ask what that counterparty is buying. When you expand into a category where nobody is buying anything, the subsidy does not shrink. It changes address.