
Bloomin’ Brands raised full-year earnings guidance and the stock jumped 31% on a 1.4% comp. The lever is not traffic. It is a price ladder Outback built so guests would climb it.
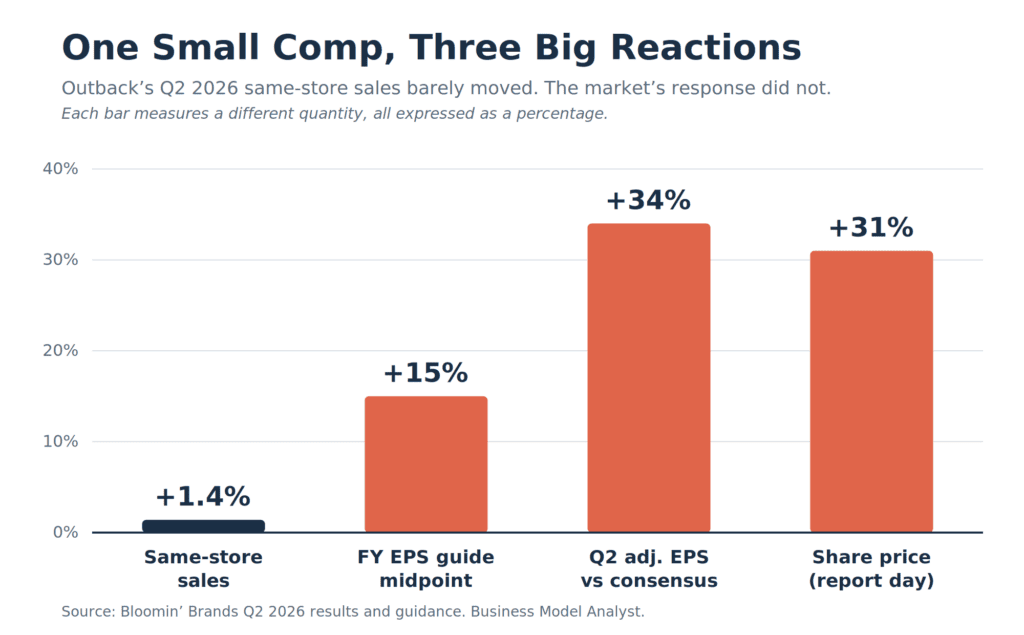
Bloomin’ Brands lifted its full-year adjusted earnings outlook because Outback diners are ordering pricier cuts, premium sides, and desserts. Same-store sales rose just 1.4%, yet the stock popped 31% and the guidance midpoint moved up about 15%. That gap is the story. Outback deliberately added a low entry price so it could sell guests up from it, and because Bloomin’ owns most of its restaurants, it keeps every dollar of that trade-up rather than skimming a franchise royalty on it.
Wall Street heard “customers are trading up” and bid the stock up a third in a morning. Fair enough. But “customers are trading up” makes it sound like something that happened to Outback, a lucky tailwind from a suddenly confident consumer. Read the transcript and it looks more like something Outback did. The chain rebuilt its menu so the cheap option is the front door, not the destination, and roughly six in ten guests walk straight past it into a higher tier. This is menu engineering wearing an earnings beat.
What Happened
Bloomin’ Brands, the parent of Outback Steakhouse, raised its full-year adjusted earnings-per-share guidance to a range of 90 cents to $1, up from 75 to 90 cents. Shares climbed 31% to $11.72 on the news, a violent move for a stock that has spent the past year in the single digits.
The quarter underneath the raise was solid rather than spectacular. Total revenue rose 1.3% to $1.02 billion, edging past the $1.00 billion analysts expected. Net income was $31.3 million, or 36 cents a share, up from $25.4 million and 30 cents a year earlier. Adjusted earnings came in at 39 cents, well ahead of the 29 cents Wall Street modeled. Outback’s U.S. same-store sales grew 1.4%, and every other Bloomin’ brand posted positive comps too.
The interesting detail is in the mix. CEO Mike Spanos told analysts that guests are “trading up more and more into the premium cuts,” and that the reaction has beaten what the company saw when it tested the lineup in 2025. Diners are adding premium sides and desserts, and a redesigned menu pushing steak-and-seafood or steak-and-chicken combos has converted better than expected. Bloomin’ narrowed its full-year U.S. same-store sales guidance to 1% to 2%, up from a wider and lower 0.5% to 2.5%.
The Backstory
To understand why a 1.4% comp is worth celebrating here, you have to remember where Bloomin’ was standing a year ago. This is a turnaround, not a growth story. In early 2024 the company closed more than 40 underperforming restaurants, including every remaining Outback in Hawaii, as part of a financial restructuring. The stock spent much of the last year trading in the $6 to $9 zone, and at one point carried a double-digit dividend yield, the kind of number the market only hands out when it doubts the payout will last.
Spanos, who took over as part of that reset, has been running a straightforward playbook: stop the bleeding on traffic, give value-seeking guests a reason to walk in, and then earn more from each of them once they are seated. The 1.4% comp matters because it is positive, it is broad-based across all four brands, and it is being driven by check size rather than discounting. For a chain that was closing locations eighteen months ago, “guests are spending more per visit and we are raising the year” is a genuine inflection.
The Plan
Here is the mechanism the headlines skip. Outback added lower-priced entry options to its menu, an affordable on-ramp for a nervous consumer. That looks like a value play, the same defensive discounting every casual chain reached for over the past two years. It is not.
The entry price is bait. Spanos said about 60% of guests are consistently trading up out of that entry tier into higher-priced items. The cheap steak exists to get you in the door and anchor your sense of the menu. Once you are reading it, the premium cut, the combo, the add-on side, and the dessert do the real work. This is classic good-better-best pricing, the same architecture that sells you the middle wine on the list and the 256GB phone you did not plan to buy. The low anchor makes the step up feel reasonable, and most people take it.
Crucially, this is margin the company keeps in-house. Bloomin’ owns and operates the large majority of its Outback restaurants directly. Only a handful of states, Arizona, California, Colorado, Nevada, and New Mexico, run through a franchisee, Out West Restaurant Group. So when a guest at a company-owned Outback swaps a sirloin for a ribeye and adds a loaded side, that incremental spend flows into Bloomin’s own restaurant-level margin, not a fixed royalty on someone else’s sales.
The Business Model Angle
This is where the 31% pop stops looking crazy and starts looking like arithmetic.
A restaurant is a high-fixed-cost machine. The rent is signed, the kitchen is built, the servers are already clocked in, the table is already occupied. When that same guest at that same table orders a $32 entree instead of a $24 one, most of the extra eight dollars is not eaten by new cost. It falls through to the restaurant-level margin, and from there to the operating line. That is operating leverage, and it is why a 1.4% same-store sales number can translate into a roughly 15% raise in full-year EPS guidance and a 34% earnings beat against consensus. The comp is small. The financial echo is large, because the incremental dollar arrives at very high margin.
Now put it next to the franchise business model, which is how most of the restaurant industry is built. A pure franchisor sells the brand and collects a percentage of the franchisee’s sales. It captures a slice of the trade-up, but only its royalty slice, and it carries none of the restaurant’s operating leverage in either direction. Bloomin’ chose the harder, heavier path of owning the boxes. That path is punishing when traffic falls, which is exactly why this stock was left for dead. But it is the reason a mix shift like this one lands so hard on the P&L. Owning the restaurant means owning the upside of every upsell.
The contrast with McDonald’s most recent quarter is almost perfect. McDonald’s is a landlord and franchisor that keeps roughly 82 cents of every dollar at the franchisor line while its franchisees absorb a check-led squeeze against falling guest counts. Same macro backdrop of “check up, traffic soft,” opposite ownership structure, opposite winner. At McDonald’s the operator eats the cost and the franchisor stays insulated. At Outback, Bloomin’ is the operator, so it eats the risk and collects the reward. The trade-up narrative is identical across the two companies. Who pockets it is not.
It is also worth naming what this is not. It is not the price-hike engine that just stalled at P&G, where four years of pushing list prices finally hit a volume wall. Outback is not raising the menu across the board and daring you to notice. It is holding a low anchor and letting guests choose to spend more. Trade-up by menu architecture is more durable than trade-up by sticker, because the customer feels like they made the call.
The Risk
Now the cold water, because a 31% one-day move deserves it.
The base was on the floor. This is a re-rating of a beaten-down turnaround stock on a modest beat, not proof of a durable growth engine. A 1.4% comp and a guidance range narrowed to 1% to 2% is stabilization, not acceleration. Some of that 31% is simply short sellers and skeptics repricing a stock they had priced for continued decline.
The next quarter looks worse, not better. Bloomin’ guided to an adjusted per-share loss of 22 to 27 cents for Q3, deeper than the 19-cent loss Wall Street was already expecting. The market cheered the full-year raise and looked straight through the near term, but the near term is still red.
Trade-up is the most fragile revenue there is. The entire thesis rests on a guest who feels comfortable ordering the ribeye. That comfort is the first thing to go in a real downturn. If the consumer wobbles, the 60% who trade up trade back down fast, and Outback is left holding the deliberately low entry price it engineered. Operating leverage runs in reverse just as hard, which is the exact movie that put this stock in the single digits to begin with.
Some of the “premium” may be beef inflation in a costume. Premium cuts carry higher food cost, and cattle prices have been elevated. Part of a rising check can be input-cost passthrough dressed up as consumer strength. If beef costs climb faster than guests will tolerate, the margin benefit of the mix shift compresses.
Quick Questions
Is Outback a franchise? Mostly no. Bloomin’ Brands owns and operates the large majority of Outback locations directly. A franchisee, Out West Restaurant Group, runs the restaurants in Arizona, California, Colorado, Nevada, and New Mexico. That ownership choice is central to why this quarter landed the way it did.
Why did the stock move so much more than sales? Operating leverage. In a high-fixed-cost restaurant, extra spend per guest arrives at very high incremental margin, so a small same-store sales gain multiplies on the way down to earnings, and earnings expectations drive the stock.
What is Bloomin’ Brands besides Outback? It also owns Carrabba’s Italian Grill, Bonefish Grill, and the upscale Fleming’s Prime Steakhouse & Wine Bar. All of its brands posted positive same-store sales this quarter.
Is the trade-up a price increase? Not in the usual sense. Outback kept a low entry price and is selling guests up into pricier items by choice, rather than raising the whole menu. The check grows through mix, not across-the-board list-price hikes.
The Business Model Analyst Take
The tidy version of this story is “confident diners bought expensive steaks and the stock went up.” The truer version is that Outback built a pricing staircase, put a cheap step at the bottom to get you in the building, and designed the rest of the menu so that climbing felt natural. Sixty percent climbed. Because Bloomin’ owns the restaurants instead of franchising them, the company caught the full weight of that mix shift on a high-fixed-cost P&L, and a 1.4% comp turned into a third of the market cap.
That is the lesson worth taking, whether you run a restaurant, a software product, or a Shopify store. Adding a cheaper option is not always a defensive concession to price-sensitive customers. Engineered correctly, the cheap option is a customer-acquisition tool whose whole job is to make the expensive option look like the reasonable choice. The money is not in the anchor. It is in the trade-up, and it only compounds if you own the economics of the upsell instead of licensing them away.
The catch, and there is always a catch, is that the same ownership that magnified this quarter’s good news will magnify the next bad one just as faithfully. Outback did not discover a moat. It discovered leverage. Leverage is wonderful right up until the direction changes.